Transform the mortgage industry with the power of cutting-edge AI technology.

At Zeitro, our mission is to revolutionize the mortgage industry by harnessing the power of cutting-edge AI technology. We aim to empower mortgage professionals and simplify the loan origination process, making it faster, more efficient, and more accessible for everyone involved.

Our vision

We envision a future where the mortgage process is fully automated, delivering a seamless and stress-free experience for all.

About us

‍‍

Zeitro is committed to redefining the future of mortgage origination. Headquartered in Silicon Valley, we serve over 3,000 mortgage professionals across the nation, offering AI-driven solutions that enhance every stage of the mortgage process. Built on a foundation of deep industry expertise and powered by advanced AI technology, Zeitro automates the end-to-end loan origination process, ensuring a streamlined experience for loan officers, borrowers, and lenders alike.

We are passionate about bringing innovation to the mortgage industry, and our goal is to deliver a platform that not only simplifies workflows but also fosters growth for mortgage professionals and satisfaction for borrowers. At Zeitro, technology and human expertise come together to create a smarter, faster, and more reliable mortgage experience.

“Zeitro leverages cutting-edge AI technology to drive the digital revolution in the mortgage industry.”

men image in black suit

Bochen W.

CEO, Zeitro
Resource

Keep up with the latest Zeitro updates

What Income Can Increase DTI Qualification for a Mortgage?

Blog

5 min read
Grey arrow icon pointing right on a dark background
What Income Can Increase DTI Qualification for a Mortgage?
Need to fix a high DTI? Learn what lenders count, from overtime and rental income to grossed-up disability and asset depletion, to qualify for a home loan.

As a loan officer, I often sit with hopeful buyers whose dream homes slip away because their back-end debt-to-income (DTI) ratio is hovering just above 45%. When paying off debt quickly isn't an option, our best strategy is uncovering overlooked, legally permissible earnings. Expanding your qualifying gross monthly income lowers your overall ratio, turning an automatic loan denial into a clear-to-close approval.

Key Takeaways

  • Boosting qualifying gross income lowers your back-end DTI percentage by expanding the denominator.
  • Variable pay like overtime, bonuses, and commissions requires a consistent two-year receipt history.
  • Nontaxable income, such as disability and Social Security, can be grossed up by 15% to 25% to inflate qualifying earnings.
  • Liquid assets can convert into monthly qualifying cash flow via asset depletion programs.
  • Lenders demand verified stability, documentation, and a clear three-year expectation of continuance.

‍

Can You Increase DTI Qualification?

Yes, you can significantly improve your qualification standing. In mortgage underwriting, your DTI is a fraction: total monthly debt obligations divided by gross monthly income. While you want your DTI percentage to go down, you improve your qualification status by pushing the income denominator up. If paying off car notes or student loans isn't feasible, unlocking underutilized, compliant income streams achieves the exact same mathematical result.

Also Read:

‍

Requirements for Lenders to Count Income

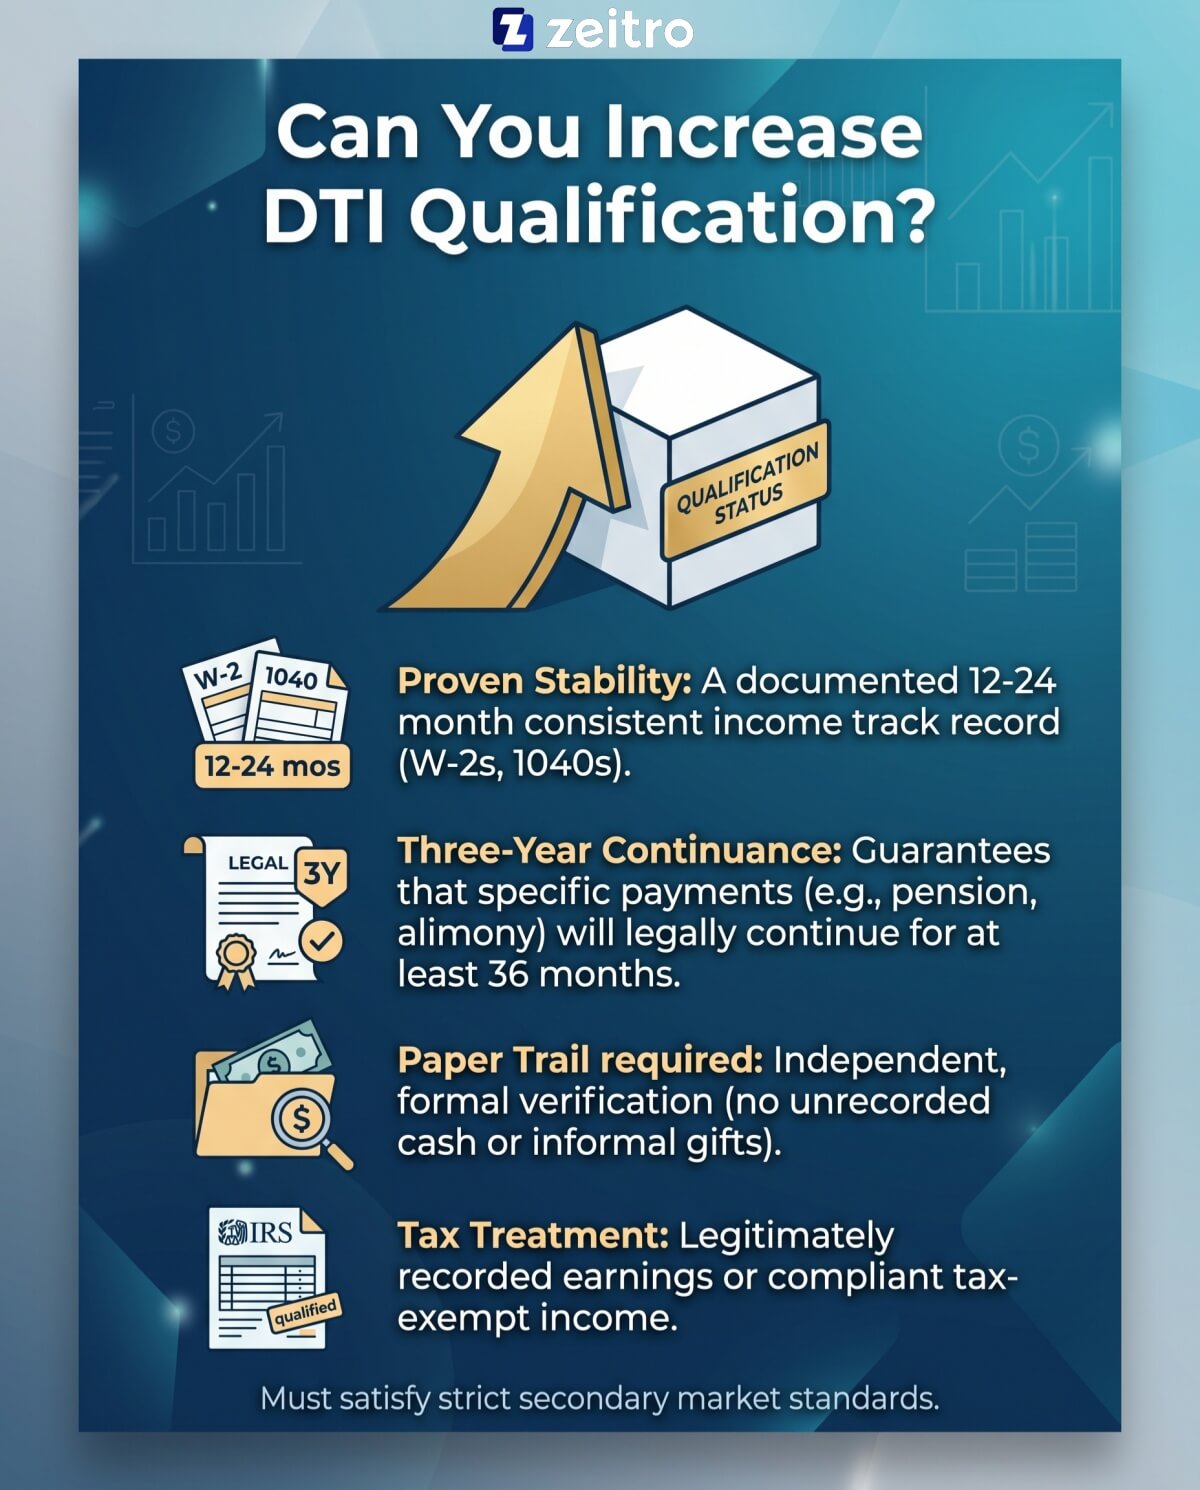
Underwriters never count arbitrary deposits hitting your checking account. Every dollar must satisfy strict secondary market standards established by Fannie Mae, Freddie Mac, or government agencies. To be counted toward your mortgage application, income must meet four baseline tests:

  • ‍Documented Stability: You must prove a consistent track record, typically supported by W-2s, 1040 tax filings, or formal written verifications spanning 12 to 24 months.‍
  • Three-Year Continuance: For certain income types, such as alimony, child support, separate maintenance, and some pension or annuity payments, lenders must document that payments are legally guaranteed or highly likely to continue for at least 36 months from the note date. Other income sources (e.g., Social Security, VA disability, employment income) follow different continuance standards based on eligibility, age, or employment history.‍
  • Independent Verifiability: Paper trails matter. Cash-in-hand arrangements, informal side gigs, or unrecorded family gifts cannot be used to qualify.‍
  • Legitimate Tax Treatment: Earnings must either show on federal returns or qualify under specific agency rules governing tax-exempt earnings.
‍

Requirements for Lenders to Count Income

Qualifying Income Sources Lenders Accept

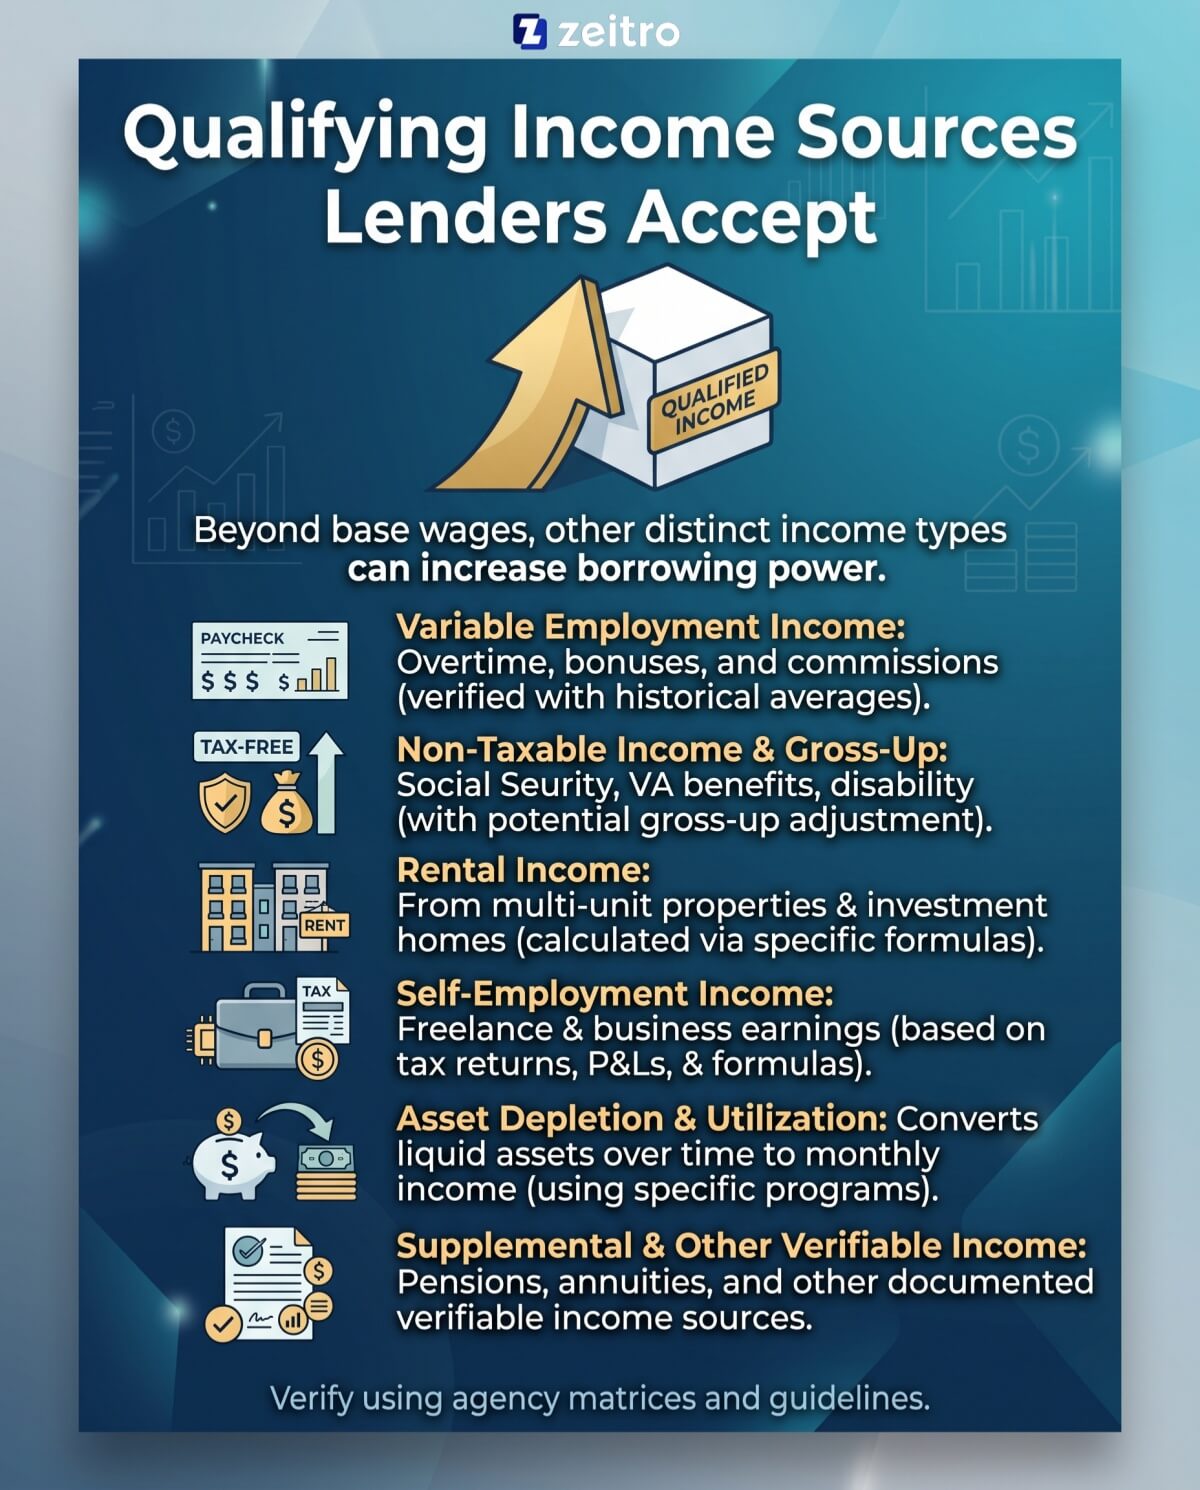
When clients need to suppress an elevated DTI, we review their financial profile beyond base hourly wages. Agency matrices and non-conforming guidelines recognize several distinct income categories that can push your borrowing power over the finish line.

#1 Variable Employment Income (Overtime, Bonuses & Commissions)

If a sizable chunk of your earnings comes from irregular compensation, lenders can include it, but they will not accept your highest recent paystub at face value. Underwriters look for stability across full economic cycles before averaging these funds into your baseline earnings:

  • ‍Two-Year Track Record: Conventional and USDA rules typically mandate 24 continuous months of bonus or commission history with your employer or line of work.‍
  • The 12-to-24 Month Window: FHA or agency guidelines may permit 12 to 23 months if backed by strong compensating factors, like high credit scores or significant cash reserves.‍
  • Declining Earnings Treatment: If variable income (e.g., commissions, bonuses) decreases year-over-year, underwriters typically qualify using the lower recent year's amount. However, if the decline is due to temporary or explainable factors (e.g., market conditions, medical leave), lenders may consider averaging or apply compensating factors per agency guidelines.‍
  • Restricted Stock Units (RSUs): Vested RSUs may be averaged over two years if accompanied by a written verification from the employer confirming future vesting schedules, and only if the shares have been sold and proceeds deposited into the borrower's account. Unvested or unsold RSUs do not qualify as income.

‍

#2 Non-Taxable Income & The "Gross-Up" Advantage

One of my favorite levers for helping clients qualify is the "gross-up" rule. Because standard underwriting measures gross pre-tax earnings, non-taxable funds give you an unfair disadvantage unless adjusted upward. Mortgage guidelines allow us to artificially elevate these tax-free payments to reflect their true purchasing power:

  • ‍The 15% to 25% Boost: Fannie Mae, Freddie Mac, VA, and USDA guidelines allow lenders to gross up tax-exempt income by 25%. FHA guidelines cap the gross-up at 15% unless the borrower's documented effective tax rate justifies a higher adjustment.‍
  • Eligible Payments: On conventional, FHA, and USDA loans, this policy applies to VA disability compensation (grossed up 25% on conventional/USDA, 15% on FHA), Social Security benefits (if non-taxable), and court-ordered child support. Note: VA loans count VA disability income at face value without gross-up.‍
  • No Additional Debt Required: A borrower receiving $2,000 monthly in tax-free disability can be credited with $2,500 in qualifying monthly income under a 25% gross-up (conventional/VA/USDA) or $2,300 under a 15% gross-up (FHA), without taking on new debt or increasing liabilities.‍
  • Minimal Documentation: Many government programs, including VA loans, permit grossing up without requiring personal tax returns, relying solely on your award letter.

‍

#3 Rental Income & Multi-Unit Cash Flow

Real estate holdings can actively reduce your debt ratio if properties generate positive net cash flow. Whether you own an existing rental, purchase a multi-unit primary home, or add an accessory dwelling unit (ADU), lenders apply specific formulas to determine usable rental figures:

  • ‍The 75% Rule: Freddie Mac and Fannie Mae deduct a 25% vacancy and maintenance buffer from gross lease amounts, counting only 75% toward debt relief or income.‍
  • Offsetting Liabilities: If 75% of your rental income exceeds the full principal, interest, taxes, and insurance (PITIA), the surplus directly elevates your qualifying monthly income.‍
  • Landlord Experience Factor: Claiming full net profits on an investment purchase usually requires at least one documented year of property management experience. Otherwise, rent might only offset the payment.‍
  • Short-Term Rentals: Certain Non-QM lenders allow verified Airbnb or VRBO earnings using trailing bank deposits or professional market rent analyses.

‍

#4 Self-Employment & Small Business Income

Self-employed borrowers often write off extensive business expenses to reduce taxes, inadvertently destroying their W-2 equivalent purchasing power. Fortunately, standard underwriting guidelines and alternative documentation loans provide structured paths to recapture that lost borrowing capacity:

  • ‍Tax Add-Backs: On standard two-year tax return reviews, underwriters add back non-cash paper losses, such as equipment depreciation, business depletion, and business-use-of-home deductions.‍
  • Two-Year Operating History: Traditional agency loans demand two full operating tax years, though 12 to 24 months can suffice if prior W-2 work aligns identically.‍
  • Bank Statement Programs: When tax write-offs remain too aggressive, Non-QM lenders review 12 or 24 months of business bank deposits, establishing qualifying income based on average net cash flow.
  • ‍Expense Ratio Adjustments: Specialized programs allow CPA-certified profit-and-loss statements, avoiding standard arbitrary expense haircut percentages and maximizing the final counted earnings.

‍

#5 Asset Depletion & Utilization Programs

High-net-worth buyers, retirees, and individuals between careers often have deep asset reserves but low taxable monthly pay. Asset depletion programs solve this mismatch by mathematically converting accumulated liquid wealth into phantom monthly income streams:

  • ‍Standard Amortization Divisors: Conventional loans follow agency rules—Fannie Mae divides net eligible assets by the loan's amortization term (e.g., 360 months for a 30-year fixed), while Freddie Mac currently uses a 180-month divisor (per Bulletin 2026-10). Non-QM and jumbo programs often use shorter divisors such as 60, 84, or 120 months to generate higher qualifying income.‍
  • Net Asset Calculation: Lenders deduct required down payments, closing fees, and post-closing reserves before running the asset calculation.‍
  • Eligible Financial Accounts: Usable assets include checking accounts, savings, publicly traded stocks, mutual funds, and vested retirement accounts (discounted for early withdrawal penalties if applicable).
  • ‍Hybrid Income Structuring: Several wholesale lenders allow asset utilization to supplement traditional W-2 or pension earnings, providing the extra monthly margin needed to squeeze past a restrictive DTI barrier.

‍

#6 Supplemental & Other Verifiable Income Sources

When standard earnings fall just short of approval thresholds, secondary financial agreements and municipal programs can provide the necessary cushion. We routinely leverage several specialized income streams to pull a client's ratio down:

  • ‍Alimony and Child Support: Recognized by lenders when documented via court order or divorce decree showing at least 6 months of consistent receipt (12 months preferred by many lenders) and at least 3 years of remaining continuance from the note date. FHA may accept 3 months of receipt history if payments are court-ordered.‍
  • Automobile Allowances: Corporate vehicle allowances may be counted as income if documented on paystubs or W-2s, received consistently for at least 12 months, and expected to continue for 3+ years. The associated auto loan or lease payment must be included in monthly liabilities, and lenders may net out documented business-related expenses if applicable.‍
  • Mortgage Credit Certificates (MCC): Through state housing finance agencies, MCCs provide an annual federal tax credit. Lenders may divide the certified annual credit amount by 12 and add it as supplemental monthly qualifying income, subject to program guidelines and borrower eligibility (e.g., first-time homebuyer status).‍
  • Guaranteed Annuities and Trusts: Structured settlements, trust disbursements, and defined benefit pensions qualify seamlessly once documented with continuous payment history and three-year ongoing duration guarantees.
‍

Qualifying Income Sources Lenders Accept

FAQs About Income Increasing DTI Qualification

Q1. Does a higher income lower my DTI?

Yes, absolutely. Your debt-to-income ratio is calculated by dividing monthly recurring debts by gross monthly qualifying income. Because income serves as the mathematical denominator, increasing your recognized earnings while keeping debt balances static naturally drives down your DTI percentage, instantly expanding your mortgage purchasing capacity.

Q2. How to increase DTI qualification?

To strengthen qualification, either reduce your actual DTI or obtain an approval at a higher threshold. You can lower your ratio by grossing up non-taxable benefits, documenting two-year variable pay, or adding an eligible co-borrower. Alternatively, you can secure higher DTI allowances up to 50% by strengthening compensating factors, such as raising your credit score and holding six months of liquid reserves.

Q3. What are common DTI mistakes?

A frequent mistake is assuming gross sales deposits equal mortgage income. Underwriters evaluate net taxable earnings after deductions. Another costly error involves changing pay structures, such as switching from a W-2 salary to 1099 contract work right before applying. Finally, many buyers fail to disclose all deferred debts or open new credit lines, triggering unexpected ratio spikes during final underwriting review.

Q4. How can I lower my debt-to-income (DTI) ratio?

The fastest method to drop your ratio is targeting small revolving debts that carry disproportionately high monthly minimums. Paying off credit card balances eliminates those monthly liabilities entirely from underwriting calculations. If cash is tight, examine student loans to see if an income-driven repayment plan lowers required reporting payments, or utilize non-taxable gross-ups to mathematically expand income.

Q5. Can I get a mortgage with a high DTI?

Yes, many programs accommodate elevated debt levels. Conventional loans via Fannie Mae Desktop Underwriter often permit DTIs up to 45% or 50% with strong credit and reserves. FHA loans frequently allow back-end ratios up to 50% or even higher with automated approval. Meanwhile, VA loans have no rigid ceiling, relying instead on leftover residual income calculations.

Conclusion

Qualifying for a home loan does not mean you must rush to wipe out every liability overnight. By auditing your complete financial picture, from grossed-up disability to two-year bonus averages and rental revenue, you can systematically expand your counted income.

Before settling for a denial or downsizing your expectations, review your W-2s, tax returns, and bank statements with an experienced loan officer to uncover hidden borrowing capacity.

People Also Read

‍

[Tips for Loan Officers] How Can I Lower Borrower DTI?

Blog

5 min read
Grey arrow icon pointing right on a dark background
[Tips for Loan Officers] How Can I Lower Borrower DTI?
Struggling with a high-DTI borrower? Explore 10 expert strategies for mortgage loan officers to cut liabilities, boost qualifying income, and pass AUS.

We have all sat across from a great applicant with steady paystubs and solid reserves, only to watch Desktop Underwriter spit out a "Refer/Ineligible" because their back-end DTI sits at 50.4%.

Losing a deal over a few percentage points is brutal. Luckily, DTI is not static. When we structure a file with the right agency rules, we can pull that ratio down and get our borrower approved.

Key Takeaways

  • ‍Installment paydown thresholds: You can exclude installment debts with ten or fewer remaining payments under agency rules, but watch out for strict lender overlays that require full payoffs.‍
  • Revolving debt realities: Under agency guidelines, the monthly obligation used in DTI is the minimum payment reported on the credit report. If no minimum is reported, lenders typically use 5% of the outstanding balance. Partial paydowns only lower DTI once the credit report reflects a reduced minimum payment, which often requires waiting for the next billing cycle. Paying the balance to $0 before closing is the most reliable way to remove the obligation from DTI.‍
  • Third-party relief: If an outside party (who is not an interested party to the transaction) has made all payments on a non-mortgage debt for the most recent 12 consecutive months with no delinquencies, agency guidelines allow the lender to exclude that monthly payment from the borrower's DTI. This does not legally remove the borrower's liability. It only excludes the payment from qualifying ratios when properly documented.‍
  • Income-side solutions: When debt cannot be cut, add qualifying income using tools like Mortgage Credit Certificates or leverage compensating factors to raise the allowable DTI cap.‍
  • Timing and re-underwrite risks: If additional debt is discovered or income decreases after the underwriting decision, the loan must be re-underwritten when the new DTI exceeds Fannie Mae's allowed tolerances. For DU casefiles, this means resubmitting to DU. For manually underwritten loans, a comprehensive risk assessment is required. Always source payoff funds early and obtain an updated credit supplement before closing to avoid delays.

‍

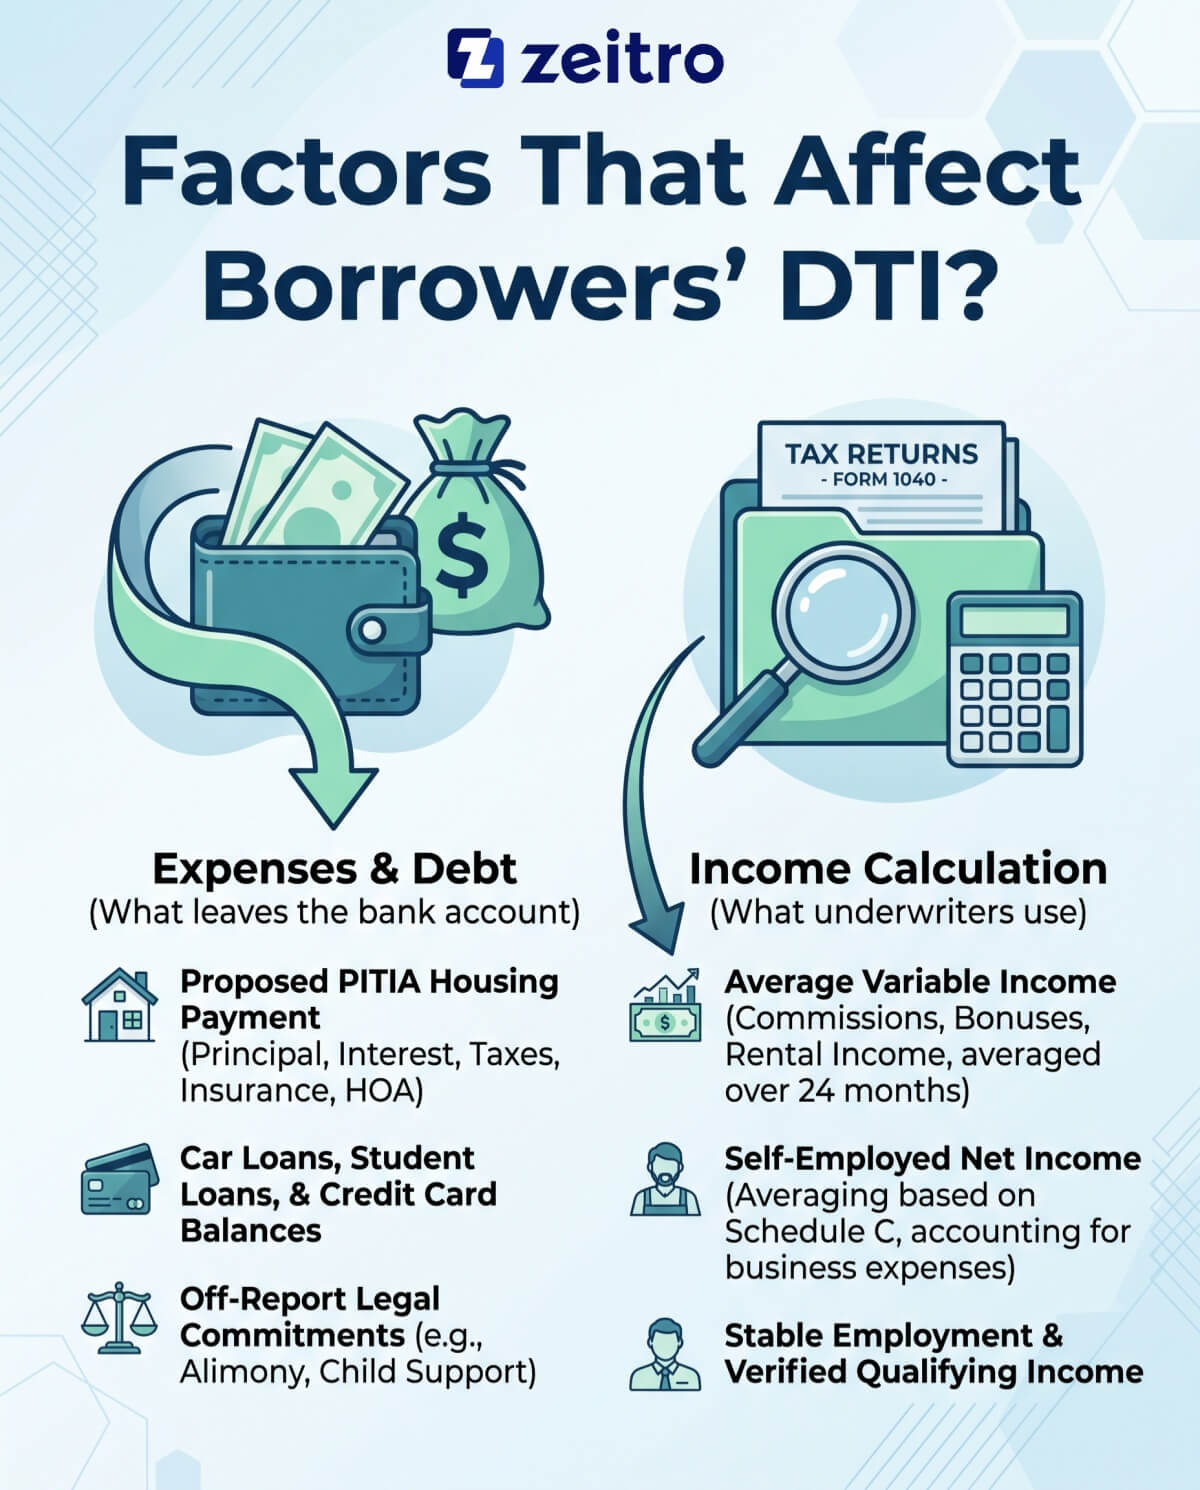
Factors That Affect Borrowers' DTI?

When I review a 1003 loan application, I break DTI into two moving parts: what leaves the borrower's bank account each month and how underwriters calculate their gross monthly earnings. Even minor shifts on either side can swing eligibility.

Here are the primary components that drive the final percentage:

  • ‍Front-end housing costs (PITIA): The full proposed monthly housing bill, covering principal, interest, real estate taxes, homeowners insurance, mortgage insurance, and mandatory HOA dues.‍
  • Back-end recurring liabilities: Non-housing debt appearing on credit reports, such as car notes, student loans, and minimum revolving credit card balances.‍
  • Off-report commitments: Legal obligations like alimony, child support, or IRS installment plans that do not show up on standard credit bureaus.‍
  • Qualifying income adjustments: For self-employed borrowers or those with variable income (commissions, bonuses, rental income), underwriters often use tax returns to calculate a conservative monthly qualifying income, frequently averaging over 24 months and accounting for business expenses as reflected on Schedule C or other applicable forms.

‍

Factors That Affect Borrowers' DTI?

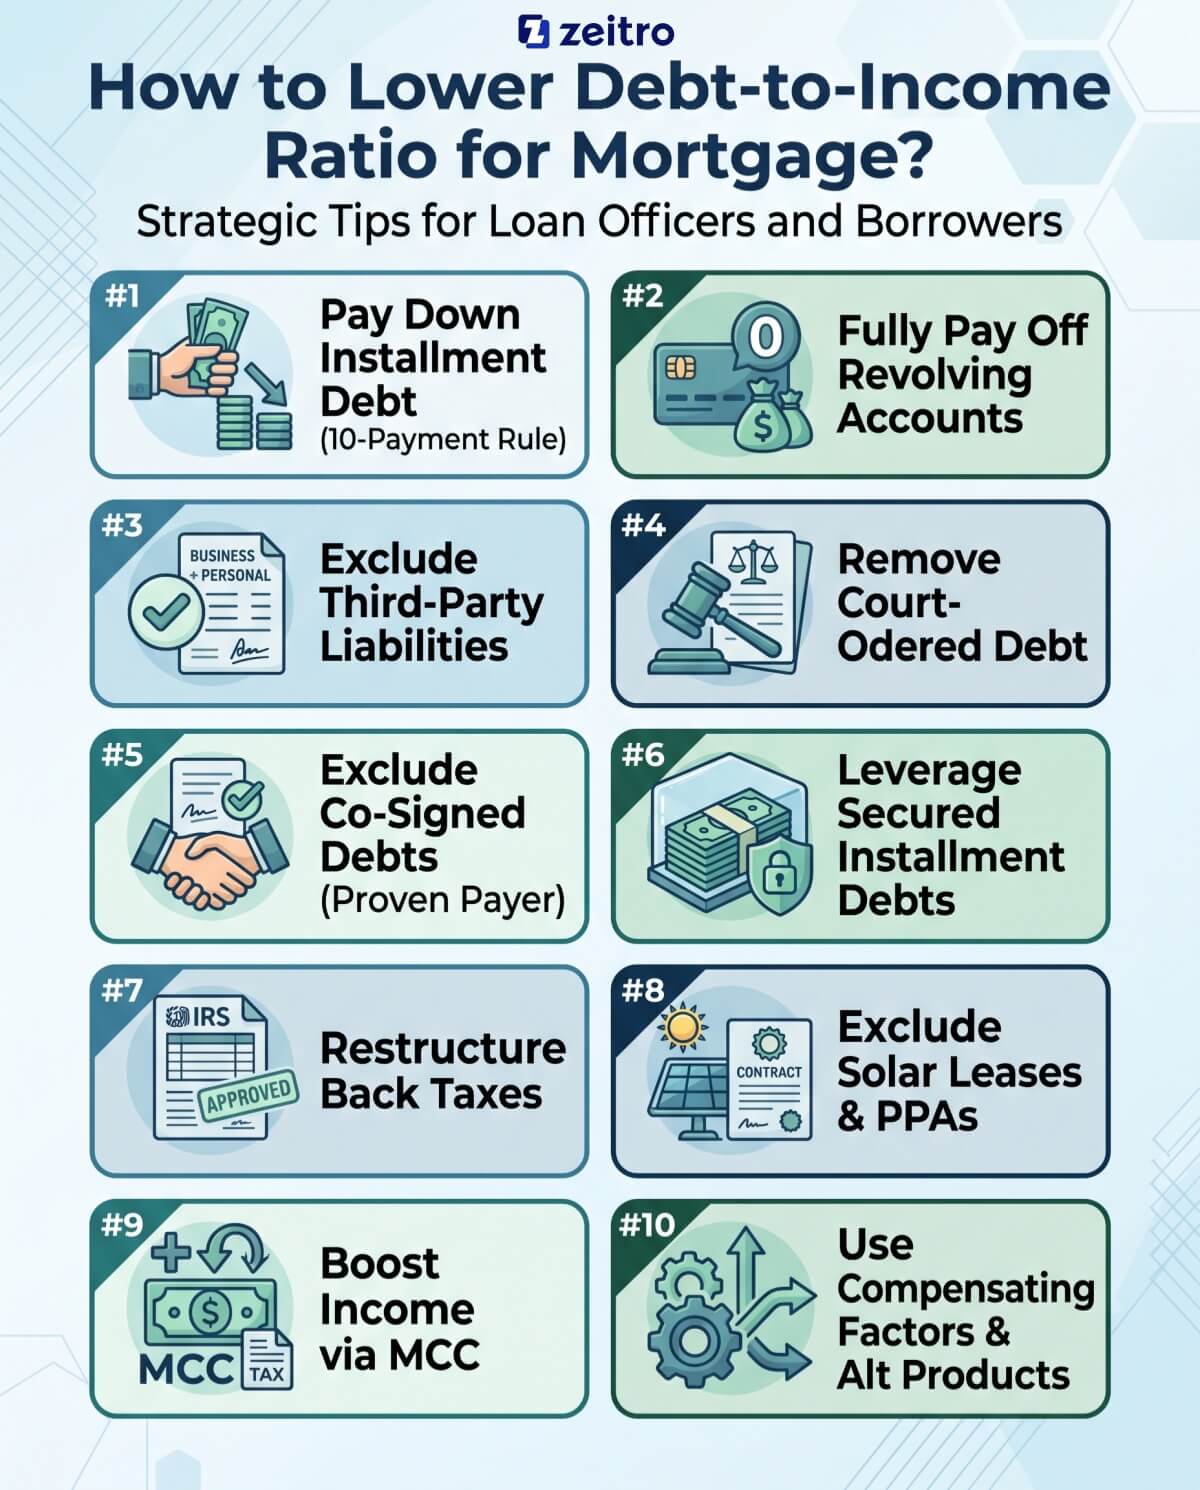
How to Lower Debt-to-Income Ratio for Mortgage?

#1. Pay Down or Pay Off Installment Debts (The 10-Payment Rule)

Under Fannie Mae and Freddie Mac guidelines, an installment loan may be excluded from the borrower's monthly debt obligations if the credit report or loan file documentation verifies that ten or fewer monthly payments remain. However, the payment must still be included if it significantly affects the borrower's ability to meet credit obligations, and automated underwriting findings or lender overlays may require it to be counted.

If a buyer owes $4,000 on a truck with an $800 monthly obligation, putting down $1,600 to bring the balance to eight payments frees up substantial borrowing power.

However, never assume this applies across the board. In my experience, lender overlays often tighten this rule:

  • Certain non-QM and portfolio programs prohibit paydowns entirely, requiring a full payoff to remove the payment.
  • Other lenders only allow the 10-payment exclusion if the initial DTI is already below 40%.
  • You must fully source and season the funds used for the paydown.

Always pull a fresh credit supplement confirming the updated remaining balance before submitting the file to the underwriter.

‍

#2. Completely Pay Off Revolving Accounts Instead of Paying Them Down

A common misconception among rookie loan officers is advising clients to cut their credit card balances in half. Unfortunately, revolving debt rarely works that way in automated underwriting. Underwriters cannot guess what a credit card company's future minimum payment will be after a partial payment, so they rely solely on the minimum stated on the credit report.

To eliminate a revolving liability from DTI:

  • Have the borrower pay off the entire balance prior to or directly at closing.
  • The account does not need to be closed, protecting their average credit age and score.
  • Order a credit supplement or show the payoff line item clearly on the Closing Disclosure.

I always warn borrowers to pay through verified liquid accounts. If they use an unverified gift or unseasoned cash, the underwriter will reject the payoff proof.

#3. Exclude Liabilities Paid by Third Parties or Businesses

Borrowers often carry debts that someone else actually pays, such as an auto loan handled by parents or an equipment loan paid by their company. Both Fannie Mae and Freddie Mac permit excluding these debts from the borrower's ratio under strict conditions:

  • ‍Debts paid by others: You must collect twelve consecutive months of canceled checks or bank statements proving an outside party made every payment. The paying individual cannot be an interested party in the real estate deal.‍
  • Business-paid debts: If an entrepreneur carries a personal loan for business purposes, provide twelve months of business bank statements confirming direct payment, backed by corporate tax returns showing the expense deduction.

A single late payment in that twelve-month window invalidates the exclusion immediately, so verify every statement before pitching this strategy.

#4. Remove Court-Assigned and Divorce-Related Liabilities

Divorce files can be challenging, but they also offer clear opportunities to clean up liabilities. When a court assigns a joint debt, such as a joint mortgage or vehicle lease, to an ex-spouse, that obligation can be legally excluded from your applicant's DTI.

Under both Fannie Mae and Freddie Mac guidelines, when a court order (such as a divorce decree or separation agreement) assigns a joint debt to an ex-spouse, that obligation may be excluded from the borrower's monthly debt obligations even if the creditor has not formally released the borrower from liability, provided the court order is documented in the file. Here is what I make sure to put in the loan package:

  • A certified copy of the final divorce decree or legal separation agreement detailing debt allocation.
  • Recorded deeds or title transfer documentation showing the applicant no longer owns the encumbered property.
  • Verification that no missed payments occurred prior to the transfer.

This allows your client to move forward without being penalized for debts they no longer manage.

#5. Exclude Co-Signed Debts with Proven Primary Payer History

Many well-meaning parents cosign car loans or student debt for their adult children, only to discover it blocks their own home purchase years later. Fortunately, cosigned contingent liabilities can often be scrubbed from the ratio if you can prove the primary borrower is handling it alone.

Agency guidelines and several non-QM programs allow you to exclude the cosigned account if you document that the primary obligor has made all payments on time. To clear this condition smoothly:

  • Gather 12 consecutive months of canceled checks or bank statements directly from the primary debtor, showing that all payments were made on time with no 30-day (or worse) delinquencies during that period.
  • Confirm the payment source account belongs exclusively to the primary borrower, with zero contributions from your applicant.
  • Verify there are zero 30-day delinquencies across the past year.

This simple paper trail can erase hundreds of dollars in ghost payments from your applicant's file.

#6. Leverage Installment Debts Secured by Liquid Financial Assets

When working with affluent borrowers who prefer liquidity over cash purchases, you might encounter personal loans secured by investment portfolios or certificates of deposit. Rather than telling them to liquidate assets to pay these off, tap into Freddie Mac's financial asset exclusion rule.

Under this provision, monthly payments on installment debts pledged against verifiable financial assets can be omitted from DTI entirely, regardless of payment size or remaining term. Keep these criteria in mind:

  • The loan must be held by a regulated financial institution.
  • Eligible collateral typically includes stocks, bonds, mutual funds, or certificates of deposit held at a regulated financial institution. Cryptocurrency and other non-traditional assets are generally not accepted as eligible collateral under agency guidelines.
  • The pledged asset cannot do double duty. You cannot count those same funds toward required down payment or closing reserves.

This guideline keeps high-net-worth deals moving without forcing unwanted asset liquidations or tax events.

‍

#7. Restructure Back Taxes into Approved IRS Installment Agreements

Discovering past-due federal taxes on a client's transcript often causes panic, but it does not have to be a deal-breaker. You do not always need to force a borrower to drain their liquid reserves to pay off a $25,000 tax balance in full.

Both agency and wholesale lender guidelines allow including an IRS installment payment in DTI instead of mandating full payoff, provided you meet these terms:

  • The borrower must produce a formal, approved IRS installment agreement notice.
  • At least one scheduled monthly payment must be documented as completed before closing.
  • The borrower must provide a formal, approved IRS installment agreement, and at least one scheduled monthly payment should be documented as completed before closing. The lender must also verify whether a Notice of Federal Tax Lien has been filed (via IRS transcripts and applicable public records) and ensure any lien is resolved, discharged, or subordinated prior to closing.

Trading a massive five-figure cash drain for a manageable $200 monthly line item saves closing funds while keeping DTI compliant.

#8. Exclude Qualified Solar Panel Leases and PPAs

Solar contracts are increasingly common on property appraisal reports, and their monthly lease payments can easily push an otherwise solid loan over the DTI limit. When an underwriter conditions for an unexpected $180 monthly solar payment, I look directly at the underlying contract terms.

Under Freddie Mac rules, solar panel lease payments and power purchase agreements (PPAs) can be excluded from DTI under specific scenarios:

  • The lease terms include an explicit energy production guarantee that offsets traditional home utility bills.
  • The PPA payment structure charges only for actual power generated, operating like a utility replacement rather than a personal debt obligation.
  • The solar company handles all system repairs and ongoing maintenance.

Request the full solar agreement upfront. If it meets these standards, you can keep that payment out of the back-end calculation.

#9. Boost Qualifying Income via Mortgage Credit Certificates (MCC)

When every debt on the credit report is legitimate and cannot be paid down, switch your focus from reducing debt to expanding qualifying income. For first-time and moderate-income home buyers, a Mortgage Credit Certificate (MCC) issued by a local housing finance agency is a powerful underwriting lever.

Instead of simply acting as an annual tax refund, underwriters can convert this federal tax credit into immediate monthly qualifying income using this formula:

Calculate the monthly MCC income as: (Mortgage Amount × Note Rate × MCC certificate rate) ÷ 12, and add that amount to the borrower's gross monthly qualifying income. Note that the MCC certificate rate is set by the housing finance agency. For IRS purposes, credits with a rate above 20% are generally capped at $2,000 annually, but underwriting follows the agency's MCC income calculation.

For example, increasing qualifying income by the monthly MCC amount directly reduces the DTI ratio without changing the borrower's reported liabilities.

#10. Pivot to Compensating Factors and Alternative Loan Products

If you have exhausted debt exclusions and income adjustments, your final move is expanding the acceptable DTI ceiling through compensating factors or alternative loan products. Automated underwriting engines like DU and LPA can approve ratios up to 50% when offset by robust risk factors.

Consider these strategic pivots:

  • ‍FHA compensating factors: FHA guidelines allow back-end ratios to stretch to 47% or 50% if the borrower shows three to six months of verified reserves, substantial residual income, or minimal housing payment increase.‍
  • Manual underwriting cushions: Document strong credit profiles (740+ FICO) or significant equity contributions to justify manual approvals above standard limits.‍
  • Non-QM options: Transition self-employed borrowers to twelve-month bank statement programs or asset depletion loans, where qualifying income calculations are often significantly higher than tax-return adjusted numbers.

‍

How to Lower Debt-to-Income Ratio for Mortgage?

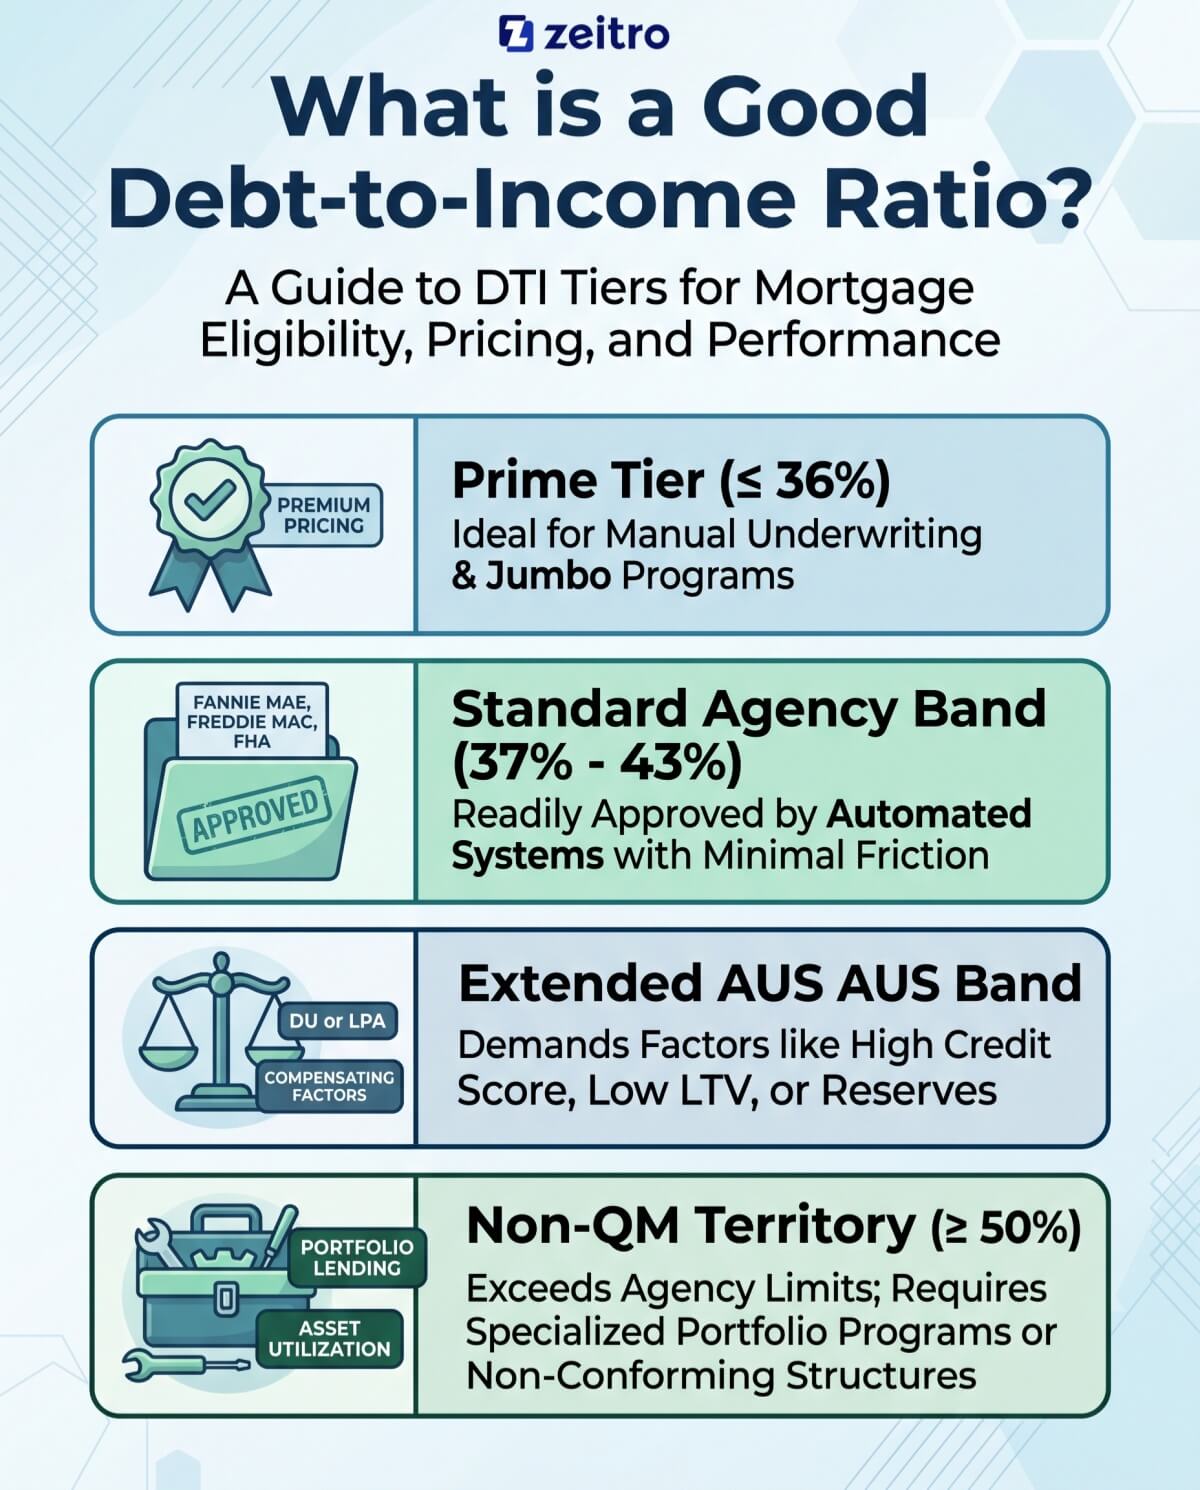
What is a Good Debt-to-Income Ratio?

In the mortgage industry, what qualifies as a "good" DTI depends on whether you are looking through the lens of program eligibility, investor pricing, or long-term loan performance. While higher ratios can get approved, keeping clients within conservative bands provides safety margins against unexpected closing adjustments.

Here is how underwriters view DTI tiers across conventional and government channels:

  • ‍Prime Tier (36% or below): The ideal benchmark for manual underwriting, jumbo programs, and premium interest rate pricing.‍
  • Standard Agency Band (37% to 43%): Readily approved by automated underwriting systems across Fannie Mae, Freddie Mac, and FHA with minimal documentation friction.‍
  • Extended AUS Band (44% to 50%): Achievable through DU or LPA, but demands compensating factors like high credit scores, low LTV, or liquid reserves.‍
  • Non-QM Territory (50% and above): Exceeds agency limits. Requires specialized portfolio lending, asset utilization programs, or higher-rate non-conforming debt structures.

‍

What is a Good Debt-to-Income Ratio?

FAQs About Lowering DTI

Q1. How to Calculate Debt-to-Income Ratio?

To calculate back-end DTI, add the borrower's proposed monthly housing cost (PITIA) to all recurring monthly debt payments, then divide by their verifiable gross monthly income before taxes. Multiply by 100 to find the percentage.

Include minimum credit card obligations, auto loans, student payments, and child support. Exclude ordinary living expenses such as food, utility bills, cellphone plans, and medical insurance premiums. A borrower with $3,000 in total monthly debt payments and $7,500 in gross monthly earnings has a back-end DTI of exactly 40%.

Also Read: [Guide] How to Calculate DTI Ratio for Mortgage?

Q2. What is the Max DTI by Loan Types?

Maximum DTI caps vary significantly depending on the loan program and whether the file is evaluated by an automated engine or manual underwriting:

  • ‍Conventional Loans: Manual underwriting is capped at 36% to 45%, but Desktop Underwriter and Loan Product Advisor regularly issue approvals up to 50% with strong compensating factors.‍
  • FHA Loans: Standard benchmarks are 31/43%, yet automated approvals frequently clear at 46.9/56.9% for well-qualified applicants.‍
  • VA Loans: The VA establishes a soft benchmark of 41%, but has no hard cap. Approvals rely primarily on passing regional residual income tests.‍
  • Non-QM Loans: Portfolio guidelines often accommodate DTIs up to 50% or 55%, depending on liquid asset reserves.

‍

Q3. Can Paying Off Debt Before Closing Trigger a Re-Underwrite or Delay?

Yes, uncoordinated debt payoffs can derail your closing timeline. Under Fannie Mae standards, if additional debt is discovered or income decreases after the underwriting decision and the resulting DTI exceeds the allowed tolerances, the loan must be re-underwritten. For DU casefiles, this requires resubmission to DU. For manually underwritten loans, a comprehensive risk assessment is required.

Furthermore, making last-minute lump-sum payments right before closing raises red flags during final credit refreshes and undisclosed debt monitoring. Underwriters will halt loan docs to demand proof of the transaction and source of funds to verify that no new unapproved credit or borrowed cash was used. Always structure payoffs early, document fund sources, and obtain a clean credit supplement before resubmitting.

Q4. Why Can't Borrowers Simply Pay Down Credit Cards by Half to Qualify?

Revolving accounts determine required monthly obligations based on variable formulas tied to fluctuating statement balances. Underwriters cannot guess what a credit issuer will demand next month if a client pays off only half the balance today. Unless an account is settled to a zero balance, guidelines require using the minimum payment listed on the current credit report.

To reflect a lower minimum payment, the credit report must show the updated amount, which typically requires waiting until the card issuer reports the new balance and minimum payment in the next billing cycle. Lenders then re-pull credit. This timeline often conflicts with closing deadlines.

Final Word

Lowering a borrower's DTI is not about finding loopholes. It is about knowing underwriting guidelines better than anyone else in the room. When an automated engine flags an ineligible ratio, walk through liabilities methodically before walking away from the deal.

Check for third-party payers, explore installment paydown thresholds, and verify investor overlays. Structuring files cleanly upfront turns borderline applications into closed loans and builds real trust with your real estate partners.

People Also Read

‍

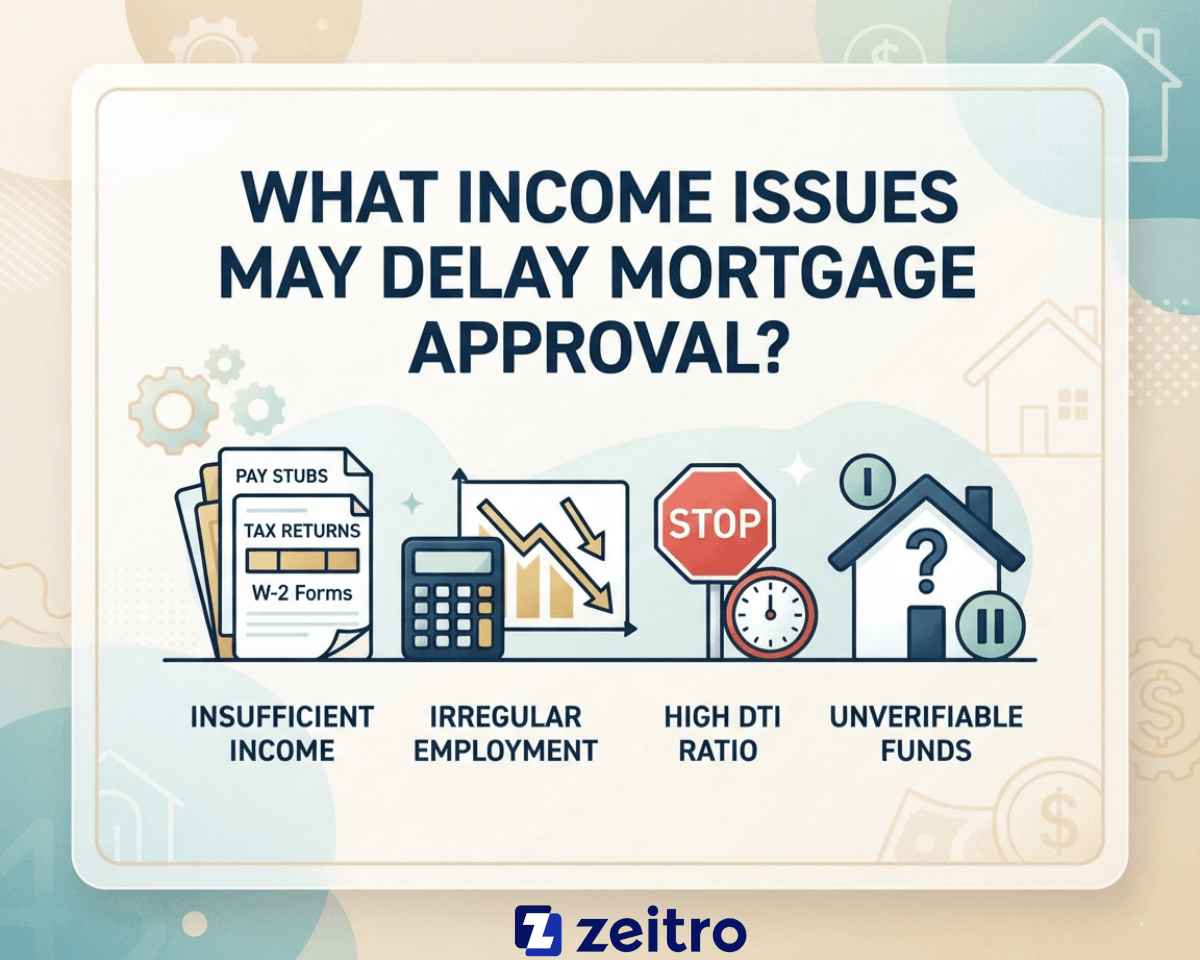
What Income Issues May Delay Mortgage Approval?

Blog

5 min read
Grey arrow icon pointing right on a dark background
What Income Issues May Delay Mortgage Approval?
Description: Struggling with mortgage delays? Learn how to resolve income underwriting issues, from self-employed revenue drops to IRS 4506-C and Non-QM traps.

Few things stall a clean pipeline faster than sudden income conditions from underwriting. When a loan officer faces a conditional suspension or last-minute denial, pinpointing the documentation gap makes all the difference. I have spent years clearing complex files, and this field manual breaks down why income reviews get held up and how you can rescue distressed applications across agency and Non-QM channels.

Key Takeaways

  • Self-employment earnings showing a significant year-over-year decline, often flagged at 5% or more by agency guidelines and frequently scrutinized more closely when exceeding 20%, prompt detailed trend analysis and may lead lenders to use the lower year's income or require additional stabilization documentation.
  • IRS 4506-C transcript hurdles like Code 10 identity locks bring standard underwriting queues to a dead halt.
  • Bank statement loan submissions fail when tax filings are accidentally attached or multiple overdraft events appear.
  • Non-wage streams like child support and trust payouts require verifiable proof of a full three-year continuance.
  • Pre-underwriting documentation checks before running automated systems protect closing dates and prevent costly loan repurchase issues.

‍

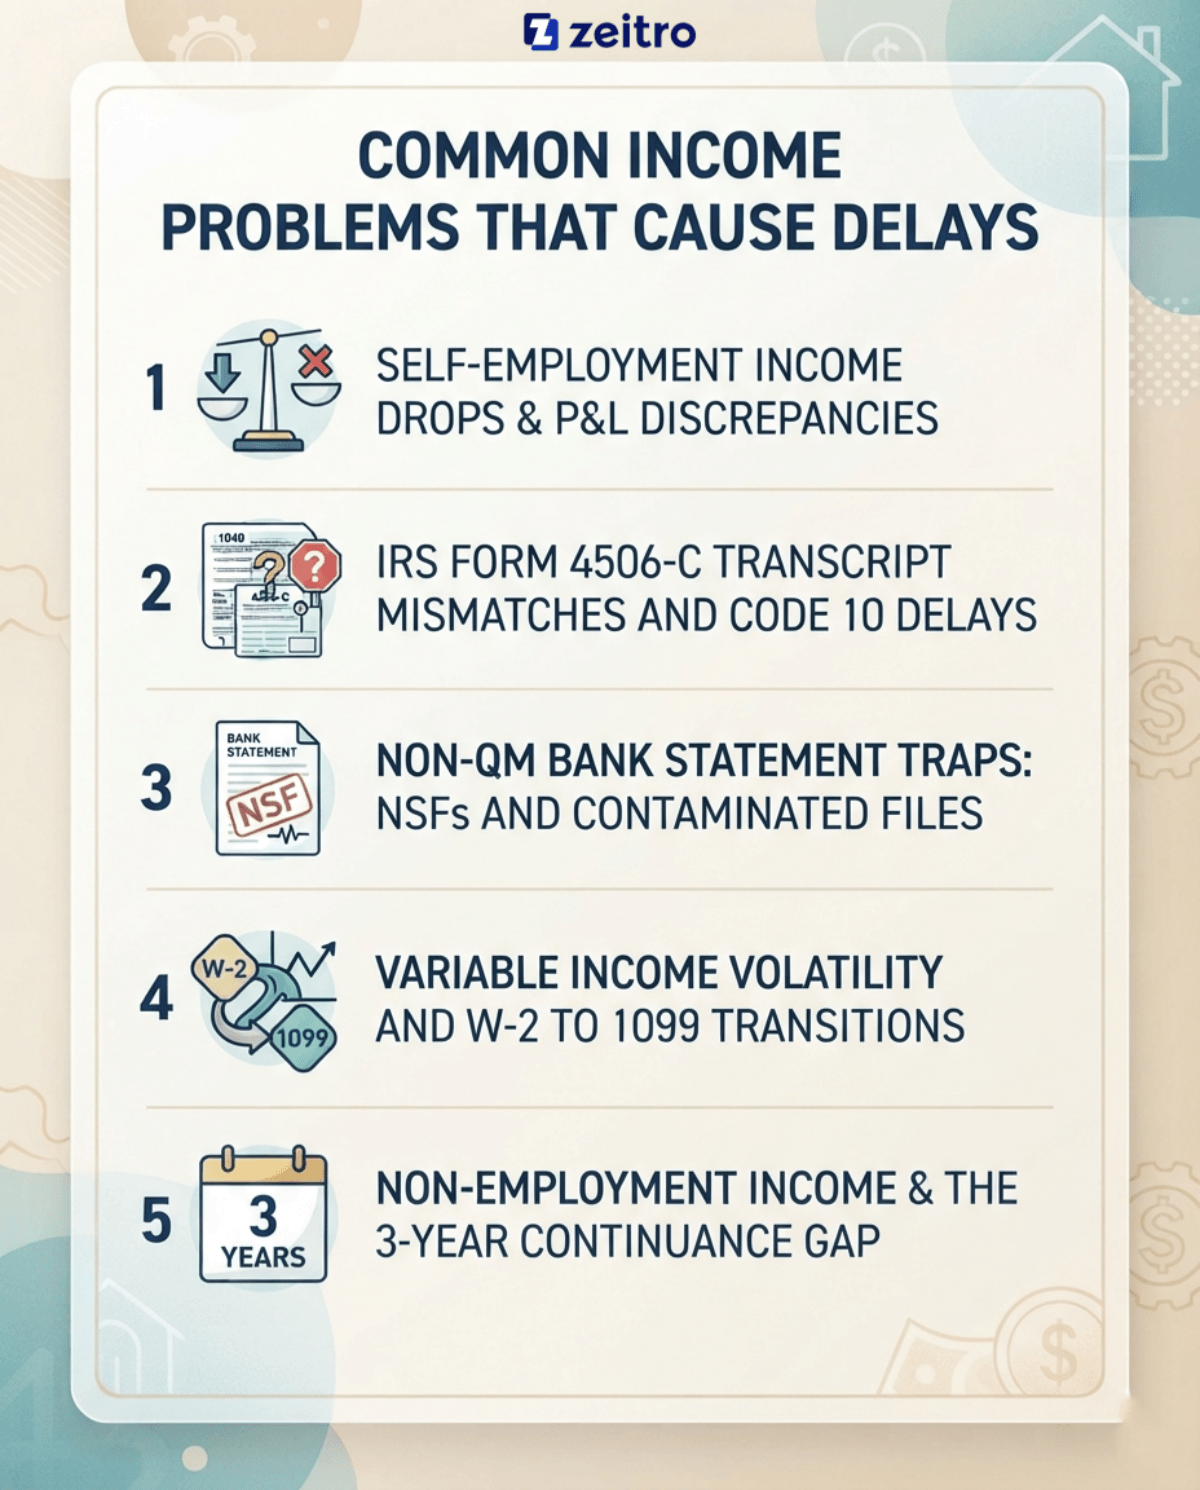
Common Income Problems That Cause Delays

Underwriters rarely reject files just because gross revenue looks tight. Delays occur when stability, paper trails, or guideline alignment fall apart. Here are five recurring traps that freeze files inside credit committee queues:

Self-Employment Income Drops & P&L Discrepancies

Agency guidelines generally require a two-year history of self-employment income, though a shorter history may be acceptable with one full year of tax returns, evidence of prior same-field earnings at the same or greater level, and strong compensating factors.

Trouble begins when the latest tax year reveals a drop greater than 20% compared to the prior filing. In my experience, examiners will instantly throw out multi-year averaging and default strictly to the lowest figure, or suspend the application outright until stability is proven.

Another frequent obstacle arises when an interim profit-and-loss sheet boasts strong margins that filed corporate returns fail to support. Furthermore, if K-1 distributions lack liquid cash reserves inside corporate accounts, underwriters strip those distribution earnings out of qualifying cash flow entirely.

  • Have the CPA prepare an explanatory letter alongside an interim P&L tied directly to recent business account records.
  • Verify corporate balance sheet cash flow to prove distributions do not jeopardize ongoing commercial solvency.
  • Pivot struggling files away from traditional agency guidelines into 12-month or 24-month bank statement programs.

‍

IRS Form 4506-C Transcript Mismatches and Code 10 Delays

Even pristine debt-to-income metrics collapse when official IRS transcripts conflict with submitted client 1040 packages. Underwriters halt reviews immediately if the transcript processing system returns a Code 10, signaling an active identity theft shield on the taxpayer's profile. Similar roadblocks surface if your borrower filed an amended 1040-X that the IRS has yet to formally log into their digital database, or if reported K-1 earnings do not align with individual tax transcripts. When records do not match federal receipts dollar for dollar, processors cannot issue a final clear to close.

  • Order IRS transcripts during initial intake rather than waiting for conditional underwriting stages.
  • Instruct clients flagged with Code 10 to retrieve their own wage and income transcripts via their verified IRS online account, and submit an underwriting escalation package that includes IRS Form 14039 (Identity Theft Affidavit) along with e-filing receipts and any IRS notices of potential identity theft.
  • Provide stamped IRS receipts alongside canceled checks showing cleared tax liability payments for recent amended returns.

‍

Non-QM Bank Statement Traps: NSFs and Contaminated Files

Shifting complex borrowers toward alternative documentation looks straightforward until procedural blunders derail the submission. The most destructive mistake I see is file contamination: mistakenly attaching federal tax returns to a pure bank statement application.

Under many Non-QM bank statement programs, once tax returns or transcripts are included in the file, the loan often becomes ineligible for the bank-statement product and must follow full-documentation underwriting, which requires income to be analyzed based on reported tax write-offs and can significantly reduce qualifying income.

Additionally, bank statement matrices are unforgiving regarding non-sufficient funds (NSFs) and overdraft activity. A pattern of bounced checks suggests severe liquidity trouble, while undocumented intra-account transfers trigger heavy calculation haircuts that erode usable deposits.

  • Scrub upload folders thoroughly to ensure zero tax transcripts or returns touch a bank statement submission.
  • Audit statements line by line to identify NSFs, seeking program exceptions before entering formal queues.
  • Exclude all non-operational deposits, wire transfers, and personal equity infusions from gross calculation totals.

‍

Variable Income Volatility and W-2 to 1099 Transitions

Commission structures, hourly overtime, and annual performance bonuses demand a verified 24-month receipt history before credit systems count them as reliable income. When an applicant recently migrated from standard W-2 employment to independent 1099 contracting, Fannie Mae and Freddie Mac reset the stability clock back to zero, viewing the borrower as an untested startup venture.

If variable pay exhibits a noticeable downward trend over the previous calendar year, examiners bypass standard two-year averaging and restrict calculations strictly to the lower trailing period. Similar scrutiny applies to borrowers employed by direct family enterprises.

  • Request completed written verification of employment forms early, confirming the employer expects variable pay to persist.
  • Base loan qualification exclusively on guaranteed base salary whenever commission records lack required historical depth.
  • Redirect recent 1099 contractors with deep industry background into specialized one-year 1099 Non-QM loan products.

‍

Non-Employment Income & The 3-Year Continuance Gap

Secondary income streams such as alimony, child support, trust distributions, and asset depletion models require stringent proof of longevity. Underwriting guidelines for income sources with a defined expiration, such as alimony and child support, typically require documented receipt (commonly six months, though some programs accept three) and evidence that payments are legally obligated to continue for at least 36 months from the note or application date.

If a dependent turns 18 within that three-year window, child support payments get scrubbed from qualifying numbers. Trust distributions and structured settlements are evaluated based on the governing instrument and the program's asset-depletion or income-continuance rules. If the documentation cannot support a reasonable expectation of continued payments for at least three years, many programs will exclude or limit that income.

  • Review divorce decrees and settlement terms to confirm recipient payments run at least 36 full months past closing.
  • Gather signed trust instruments and current investment balance sheets verifying adequate portfolio liquidity.
  • Obtain formal employer assurances confirming return-to-work dates and job protection for borrowers on temporary medical leave.

‍

Common Income Problems That Cause Delays

Mortgage Income Requirements to Know

Navigating income delays requires knowing precisely which regulatory framework your borrower fits best:

  • ‍Qualified Mortgages (QM – Conventional, FHA, VA, USDA): Built around Ability-to-Repay (ATR) requirements and specific product features. They typically rely on two years of verified income documentation, but agency underwriting may accept shorter histories in limited scenarios (for example, one year of tax returns when supported by strong compensating factors). Strict debt-to-income limits often apply (commonly around 43%–50%, depending on program and overlays). Under FHA's defect taxonomy, income documentation failures can be classified as Tier 1 or Tier 2 defects depending on severity and impact on ATR, potentially triggering indemnification obligations.‍
  • Non-Qualified Mortgages (Non-QM): Designed for borrowers whose legitimate earning power is masked by tax deductions or non-traditional cash flows. These programs accept 12 to 24 months of business or personal bank statements, 1099 declarations, or asset depletion calculations. While they permit debt-to-income limits up to 55%, underwriters focus heavily on minimum liquid reserves and spotless banking conduct rather than tax return write-offs.

‍

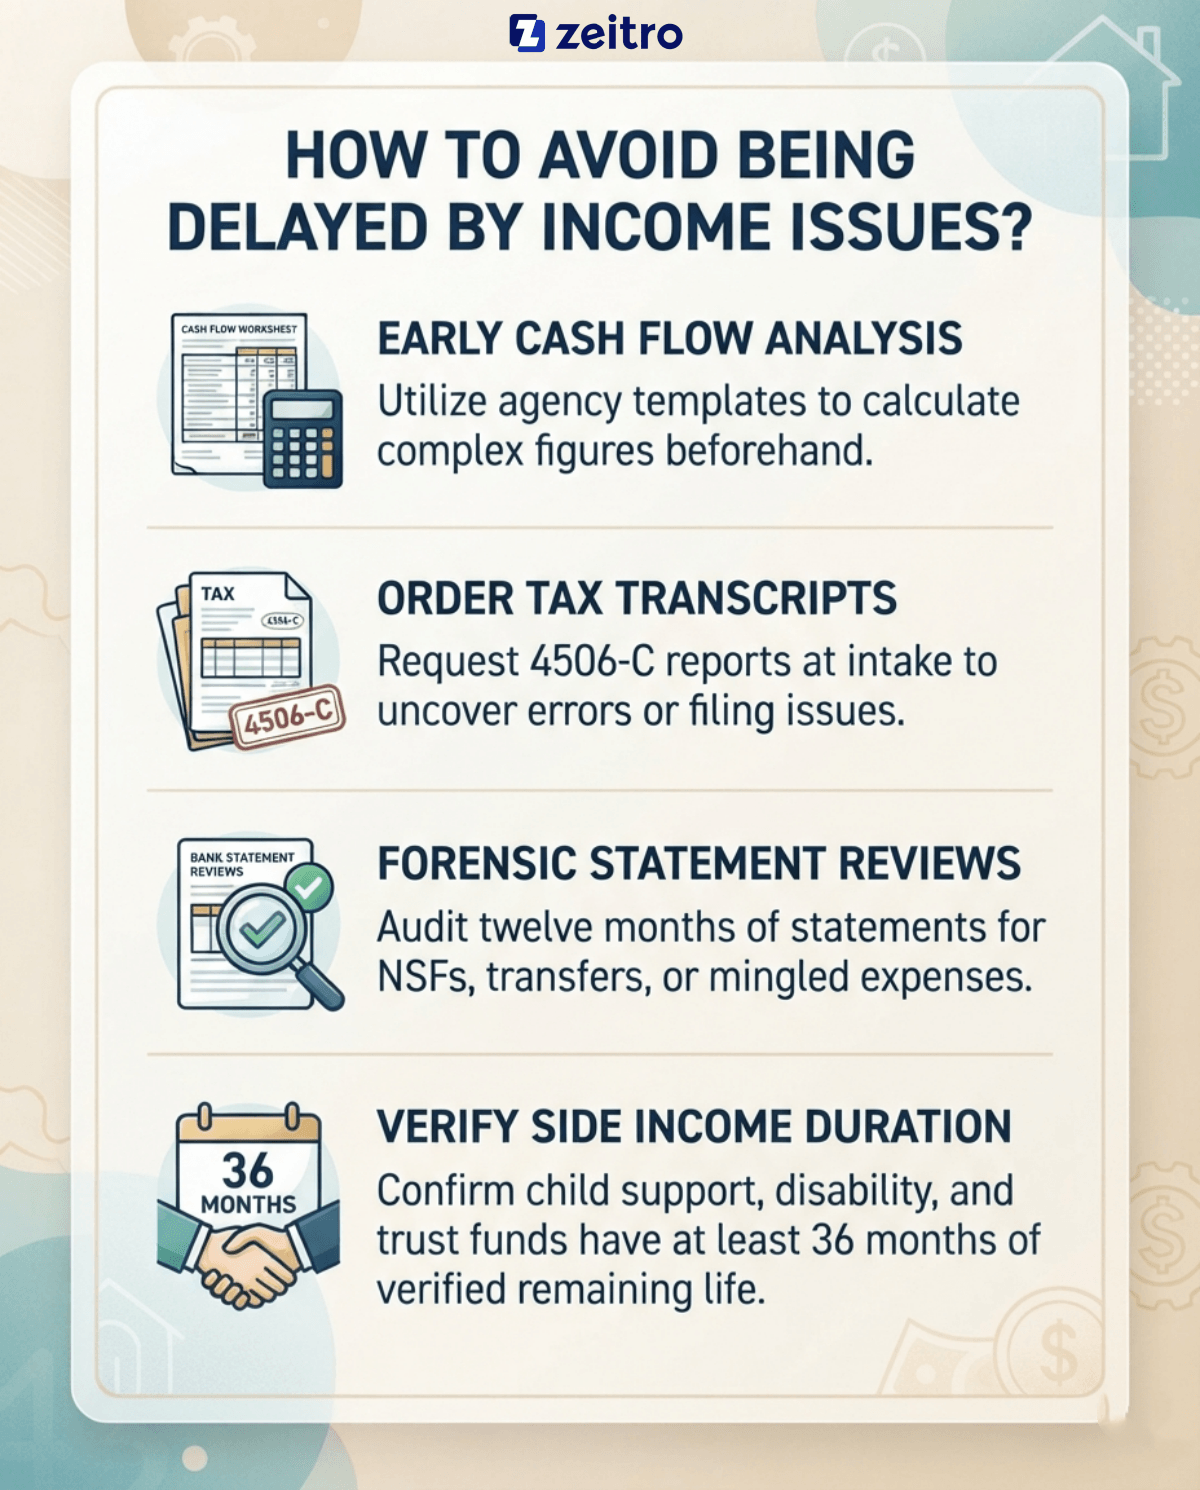
How to Avoid Being Delayed by Income Issues?

Preventing income-related file freezes comes down to rigorous upfront preparation before you ever submit an application to underwriting:

  • ‍Run Early Cash Flow Worksheets: Calculate complex self-employed figures using agency cash-flow analysis templates (such as Fannie Mae Form 1084) prior to running automated underwriting engines.‍
  • Order Tax Transcripts at Intake: Request electronic 4506-C reports immediately to uncover transcript errors, identity fraud blocks, or missing filings before underwriters spot them.‍
  • Perform Forensic Bank Statement Reviews: Audit twelve full months of bank statements for NSF flags, irregular transfers, or mingled business expenses before sending files forward.‍
  • Check the Three-Year Rule on Side Income: Confirm child support decrees, disability payouts, and trust funds have at least 36 months of verified remaining life.‍
  • Isolate Family Business Affiliations: Treat borrowers working for family-owned operations like self-employed principals from day one by gathering complete personal and corporate returns upfront.

‍

How to Avoid Being Delayed by Income Issues?

More Frequently Asked Questions

Q1. How do underwriters treat a greater than 20% decline in self-employment income?

An income drop exceeding 20% signals financial instability to underwriters. Instead of averaging earnings across the past two filing years, examiners will either qualify the borrower using the lowest single year or exclude the self-employment revenue altogether. To save the file, you must provide an interim profit-and-loss statement signed by a CPA alongside recent commercial bank statements proving the company's financial downturn has stabilized.

Q2. Can a borrower qualify if they switched from W-2 to 1099 within the past 12 months?

Under standard agency guidelines, switching from W-2 status to 1099 independent contractor compensation resets your qualifying history, meaning the file fails the two-year stability test. However, you can preserve the deal by routing the borrower into an alternative Non-QM loan product designed for 1099 workers, provided they operate in the identical profession and hold strong prior earnings documentation.

Q3. Why does including tax returns disqualify a borrower from a Non-QM bank statement loan?

Non-QM bank statement programs exist specifically to evaluate business liquidity without penalizing applicants for aggressive paper tax deductions. Once tax filings enter the loan folder, federal ability-to-repay rules force the underwriter to review those write-offs. If those returns show net operating losses, that creates a direct compliance conflict with your bank statement cash flow calculations, immediately voiding program eligibility.

Q4. What is the fastest cure when an IRS 4506-C returns with Code 10?

An IRS Code 10 indicates that an identity theft lock is active on the taxpayer's master record, blocking normal third-party electronic pulls. The quickest remedy is having your client pull their own wage and income transcripts through their verified IRS online account portal. Pair those documents with IRS Form 14039 and e-filing receipts to submit an underwriting escalation package.

Q5. What classifies an income issue as a formal FHA defect requiring indemnification?

Under HUD's defect taxonomy, income documentation failures are categorized by severity and impact on the credit decision. Knowingly submitting misrepresented income figures can constitute a Tier 1 (most severe) defect, while missing essential documentation that prevents validation of effective income may be classified as a Tier 2 defect, depending on materiality and whether the deficiency affected the approval decision. Both categories carry severe institutional penalties, requiring the mortgage lender to execute formal indemnification agreements.

Final Word

Most income delays do not stem from a borrower's inability to pay, but rather from documentation gaps discovered too late in the process. By auditing tax transcripts early, scrubbing bank accounts for red flags, and knowing when to pivot toward Non-QM alternatives, you can protect your closing timelines. Front-load your income analysis today to keep your loan pipeline moving smoothly.

People Also Read

‍

Join the Zeitro

Transform the mortgage industry with the power of cutting-edge AI technology.
Join us
Three people working together at a table with laptops, smiling during a casual meeting_5