

Refinancing a mortgage usually costs 2% to 6% of the loan amount, or about $6,000 to $18,000 on a $300,000 loan. Freddie Mac puts the range at 3% to 6% of the principal, and the CFPB's latest mortgage data show the median refinance in 2023 paid $7,329 in lender and third-party loan costs, including discount points. Title, settlement and government fees alone averaged $2,207 in 2025 (LodeStar), and a common rule of thumb from the CFPB is to refinance only if your monthly savings pay those costs back in about two years.
Mortgage rates have been anything but calm this year. Freddie Mac's weekly survey had the average 30-year fixed rate at a 2026 low of 5.98% in late February; by October 22 it was back up to 7.32%. If you took out your loan near the October 2023 peak, when that average hit 7.79%, or you're paying 8% or more, refinancing can still work in your favor.
Key takeaways:
- Total refinance closing costs run 2% to 6% of your loan amount, or roughly $6,000–$18,000 on a $300,000 loan.
- Title, settlement and government recording fees alone averaged $2,207 in 2025, including state taxes ($1,686 without them), according to LodeStar — and your state's mortgage tax rules can push that much higher.
- Relative to the loan amount, New York, Florida, Oklahoma, Pennsylvania, and Texas are the most expensive states to refinance in; California, South Dakota, and Arizona sit near the bottom.
- Divide your closing costs by your monthly savings to find your break-even point — the month when refinancing starts putting money back in your pocket.
Here's the part that catches people off guard: the rate you see advertised is never the whole story. I've sat with plenty of borrowers who were ready to sign until the "Cash to Close" line landed in their inbox and the mood in the room changed fast.
Refinancing isn't free, and it shouldn't be treated like a formality. Think of it as a small reinvestment in your finances — one where you need to know exactly where the money goes and how long it takes to earn it back. This guide walks through the real cost of refinancing right now, the fees that catch people off guard, which ones you can push back on, and the math that tells you whether the whole thing is worth doing.
Average Cost to Refinance a Mortgage
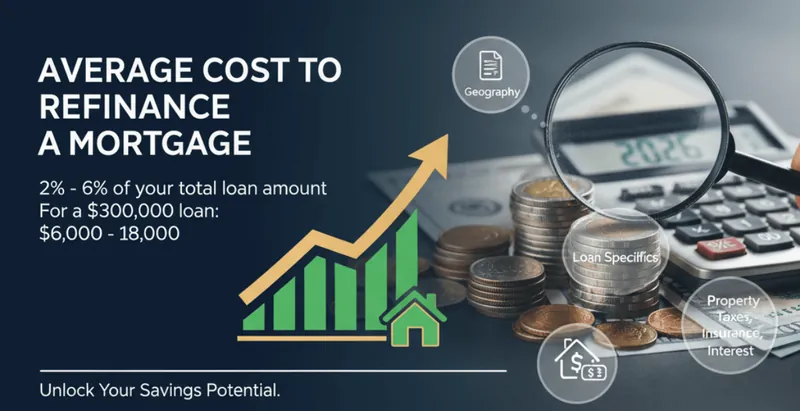
Most homeowners pay somewhere between 2% and 6% of their loan amount to refinance. On a $300,000 loan, that works out to $6,000 to $18,000 in total costs, depending on where you live and what kind of loan you're getting.
Why such a wide gap? Different data sets get quoted side by side, and they're measuring different things. LodeStar Software Solutions, which tracks closing cost data across the industry, puts the national refinance average at roughly $2,207, or about 0.67% of the loan amount, for 2025 — but that figure only counts title, settlement and escrow fees, the lender's title policy, and government recording fees and taxes. It leaves out lender fees, the appraisal and discount points. Freddie Mac's broader 3-6% estimate covers the whole list, from origination and underwriting fees to the appraisal, credit report and title work, which is why it lands so much higher. The CFPB's mortgage data sit in between: the median refinance in 2023 paid $7,329 in lender and third-party costs, including discount points. None of these numbers is wrong; they're just answering different questions.
Location does most of the heavy lifting on the government side. States that charge a mortgage recording tax or a documentary stamp tax on the new loan amount, think New York, Florida, or Maryland, sit well above the national average. California and Arizona, which don't, are among the cheapest states in LodeStar's data, at 0.32% and 0.37% of the loan amount for title, settlement and recording costs.
Refinance Closing Costs: Key Numbers and Sources
These are the figures behind this guide, with the source and year for each.
| Item | Number | Details | Source |
|---|---|---|---|
| Typical total closing costs | 3% to 6% of the loan | Lender, appraisal, credit report, title, recording and other fees | Freddie Mac, Understanding the costs of refinancing |
| Median total loan costs, 2023 refinances | $7,329 | Lender fees, appraisal, title and other third-party services, and discount points; excludes government recording fees and taxes, prepaids and escrow | CFPB, 2023 Mortgage Market Activity and Trends (p. 25) |
| Discount points on 2023 refinances | $3,902 median | 67.7% of refinance borrowers paid some points | CFPB, 2023 Mortgage Market Activity and Trends (p. 25) |
| Title, settlement and recording costs, 2025 | $2,207 average (0.67% of the loan) | $1,686 without recording fees and taxes; based on 202,059 refinance quotes | LodeStar 2025 Refinance Closing Cost Report |
| Most and least expensive states, 2025 | New York 2.06% ($10,553); California 0.32% | Florida 1.36%, Oklahoma 1.13%, Pennsylvania 1.01%; South Dakota 0.35%, Arizona 0.37% | LodeStar 2025 Refinance Closing Cost Report |
| Break-even rule of thumb | About 2 years | Proceed if the lower rate repays your closing costs in roughly two years | CFPB, Your Home Loan Toolkit |
| Escrow refund from your old servicer | Within 20 business days of payoff | Federal rule for any balance left in your old escrow account | CFPB, Regulation X § 1024.34(b) |
| Skipping the appraisal (Fannie Mae loans) | Value acceptance offered by DU | One-unit homes and condos, including cash-out refinances; not 2–4 units, co-ops, manufactured homes or estimated values of $1 million or more | Fannie Mae Selling Guide B4-1.4-10 |
| Cash-out refinance waiting period (Fannie Mae) | 12 months | The mortgage being paid off must be at least 12 months old, and a borrower must have been on title for 6 months | Fannie Mae Selling Guide B2-1.3-03 |
Breakdown of Refinance Costs
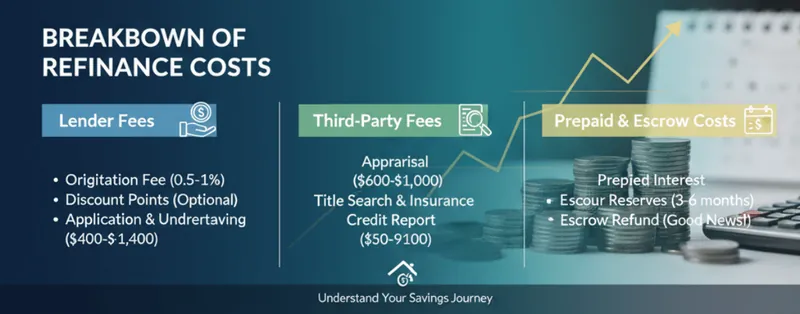
Your Loan Estimate can look like a spreadsheet exported straight into a PDF. To make sense of it, I sort every line item into three buckets: Lender Fees, Third-Party Fees, and Prepaids.
Lender Fees
This is what you pay the mortgage company directly for originating and processing your loan — and it's also where you have the most leverage to negotiate.
- Origination Fee: Usually 0.5% to 1% of the loan amount, or $1,500–$3,000 on a $300,000 loan. This covers the lender's work putting the deal together.
- Discount Points: Optional. Paying an upfront fee to buy down your rate permanently can make sense if you plan to keep the loan for years. Points are common: in 2023, 67.7% of refinance borrowers paid some, and the median amount was about $3,902, according to the CFPB.
- Application & Underwriting Fees: Together these typically total $400–$1,400 — application fees run $75–$500, underwriting adds another $400–$900. Some lenders fold these into a single flat fee instead.
Third-Party Fees
These are pass-through costs. Your lender collects the money but hands it off to outside vendors who verify the property and confirm your legal standing.
- Appraisal Fee ($600–$1,000): Refinancing almost always triggers a fresh appraisal. Costs have crept up in areas with fewer licensed appraisers and steady demand.
- Title Search & Lender's Title Insurance ($400–$900): You won't need to buy Owner's Title Insurance again, but Lender's Title Insurance is required every time you take out a new loan.
- Credit Report Fee ($50–$100): Covers pulling your tri-merge credit report during underwriting.
- Recording Fee ($25–$250): A smaller, often-overlooked charge your county collects to record the new deed of trust. It's easy to miss on the Loan Estimate, but it adds up with everything else.
Prepaid & Escrow Costs
This section confuses more people than any other. Borrowers often feel blindsided by these numbers, but here's the thing — this money is still yours.
- Prepaid Interest: You owe interest from your closing date through the end of that month.
- Escrow Reserves: Your new lender will typically ask you to fund 3–6 months of property taxes and homeowners insurance upfront, based on your county's tax schedule and your policy premium.
If you already have an escrow account with your current lender, don't worry. Federal rules require your old servicer to refund that balance within 20 business days after your old loan is paid off. It's not gone, just temporarily parked somewhere new, but you do need the cash on hand to fund the new account first.
Refinance Closing Costs by State
Where you live changes this bill more than almost anything else. Based on LodeStar's most recent state-by-state refinance data (2025), here's how title, settlement, recording and tax costs stack up as a share of your loan amount:
- New York: 2.06% ($10,553 on average), Mortgage recording tax applies to the new loan
- Florida: 1.36% ($5,250), Documentary stamp tax on the new note amount
- Oklahoma: 1.13% ($2,716), Mostly title and settlement fees on a smaller average loan, plus the state mortgage tax
- Pennsylvania: 1.01% ($2,829), Mostly title and settlement fees ($2,406 before recording and taxes)
- Texas: 0.96% ($3,405), Mostly title and settlement fees ($3,186 before recording and taxes)
- California: 0.32% ($1,672), No mortgage recording tax, spread over the largest average loan ($530,099)
- Arizona: 0.37% ($1,300), No transfer tax on refinances
New York borrowers get one break most guides skip over: a CEMA, short for Consolidation, Extension and Modification Agreement. It's a New York-specific refinance structure that lets you avoid paying the mortgage recording tax again on the portion of your balance that's simply being carried over from your old loan. Not every lender offers it, so it's worth asking your loan officer directly whether your deal qualifies.
Factors That Influence Refinance Costs
No two borrowers pay the same bill, even on identical homes. I've watched neighbors refinance the same floor plan and end up thousands apart. Here's what actually moves the number:
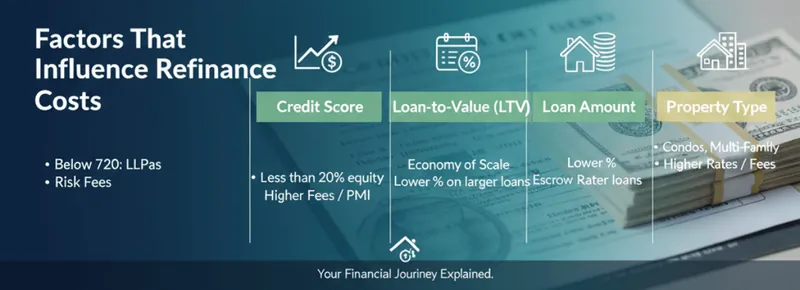
- Credit Score: The single biggest factor. Fannie Mae and Freddie Mac charge Loan-Level Price Adjustments (LLPAs) based on your credit score and LTV — risk-based charges added to your rate or your closing costs, and they get bigger as your score drops.
- Loan-to-Value (LTV) Ratio: Less than 20% equity usually means higher fees, and possibly ongoing Private Mortgage Insurance (PMI).
- Loan Amount: Fixed costs like appraisal and title fees stay roughly the same whether your loan is $150,000 or $500,000, so larger loans often pay a lower percentage overall.
- Property Type: Condos and multi-family properties tend to carry slightly higher rates and origination fees than single-family homes, since lenders view them as carrying more risk.
Real Refinance Cost Examples
Numbers land better with context, so here's how a $300,000 mortgage might play out across three common scenarios. These are illustrative estimates built from typical fee ranges, not quotes pulled from a specific lender.
Rate-and-Term Refinance Example
The Goal: Lower the interest rate and the monthly payment.
- Borrower Profile: 760 Credit Score, Single-Family Home.
- Lender Fees: $2,500
- Third-Party Fees: $2,200
- Prepaids/Escrow: $1,800
- Total Cost: $6,500
Verdict: This is the "cleanest" refinance with the lowest fees.
Cash-Out Refinance Example
The Goal: Take out $50,000 in equity for home renovations.
- Borrower Profile: 740 Credit Score, increased loan balance to $350,000.
- Lender Fees: $3,500 (Higher due to cash-out risk adjustments).
- Third-Party Fees: $2,500
- Prepaids/Escrow: $2,200
- Total Cost: $8,200
Verdict: Cash-out loans are viewed as riskier, so lenders often charge higher origination fees or slightly higher interest rates. Fannie Mae also adds its own LLPA to certain cash-out refinances.
Investment Property Refinance Example
The Goal: Refinance a rental property.
- Borrower Profile: 720 Credit Score, Non-Owner Occupied.
- Lender Fees: $4,500 (Includes "points" to buy down the rate).
- Third-Party Fees: $2,500
- Prepaids/Escrow: $2,500
- Total Cost: $9,500+
Verdict: Investment properties always come with a premium. Expect to pay 0.5% to 0.75% more in rate or fees compared to your primary home.
How to Lower the Cost to Refinance a Mortgage
You're not stuck accepting whatever number your first quote shows. Four strategies actually move the needle on your Cash to Close:
- Ask for an Appraisal Waiver: If Fannie Mae's Desktop Underwriter offers "value acceptance" (its appraisal waiver) on your file, your loan officer can skip the full appraisal — an easy $600–$1,000 saved. It's available on one-unit homes and condos, including cash-out refinances, usually when Fannie Mae already has a prior appraisal of the home on file; 2–4 unit properties, co-ops, manufactured homes and homes valued at $1 million or more don't qualify.
- Negotiate the Reissue Rate: If you bought or refinanced within the last few years, ask the title company about a reissue rate on lender's title insurance. It can cut that premium by up to 40%.
- Boost Your Credit Score: Even a 20-point improvement can bump you into a better pricing tier and shrink those LLPA charges.
- Shop Around the Right Way: Freddie Mac research found that in late 2022, homebuyers who got two rate quotes instead of one could have saved as much as $600 a year, and those who got four or more could have saved more than $1,200 a year. The same logic applies to a refinance. Skip the lead-aggregator sites that hand your number to a dozen cold-callers, and go straight to individual loan officers instead.
This is exactly the gap Bluerate.ai was built to close. It shows personalized rates, fees and loan terms up front and connects you with loan officers near you, so you can compare quotes side by side before you decide. If you're a loan officer, Zeitro's pricing engine prices conventional, government, jumbo and non-QM refinances in one search and lets you send the quote straight to your borrower.
Can You Refinance with No Closing Costs?
Ads promising a "No Closing Cost Refinance" sound too good to pass up. Here's the catch: the fees don't vanish, they just move somewhere else.
- The Trade-off: Your lender covers the $6,000 in closing costs with a lender credit, then charges you a higher rate to offset it — say 6.9% instead of 6.4%.
- When It Makes Sense: If you're planning to sell or move within five years, this can be the smarter play. You keep more cash now, and you won't hold the loan long enough for the higher rate to cost you more than you saved.
- When to Skip It: If this is your forever home, take the lower rate and pay the costs upfront. A 0.5% rate difference compounds into tens of thousands of dollars over 30 years — far more than what you saved at closing.
Refinance Cost vs Savings: How to Calculate the Break-Even Point
Before you sign any paperwork, you must do this one calculation. It determines if the refinance is an investment or a waste of money.
The Formula: Total Closing Costs ÷ Monthly Savings = Months to Break Even
Example:
- Total Closing Costs: $5,000
- New Monthly Savings: $250
- Calculation: $5,000 ÷ $250 = 20 Months
Here's the rule. If you plan to stay in the home longer than 20 months, the refinance is a win. If you think you might move in a year, don't do it. You will lose money. The CFPB's rule of thumb is similar: refinance only if you break even in about two years.
To get the monthly savings number, run your current loan and the new one through Zeitro's free mortgage calculator, which shows the monthly principal and interest for each, and subtract.
Checklist: Ideal Candidates for Refinancing in 2026
Check even one of these boxes, and it's worth getting a quote today:
- Rate Drop: Your current rate sits at least 0.75%–1% above today's market rate (with Freddie Mac's 30-year average at 7.32% on October 22, 2026, that means roughly 8% or higher).
- Credit Improvement: Your score has climbed 50+ points since you bought the home, opening the door to better pricing.
- PMI Removal: Rising home values have pushed you past 20% equity, letting you drop costly mortgage insurance.
- ARM Expiration: Your Adjustable Rate Mortgage is about to reset to a higher rate.
Cost to Refinance Mortgage: FAQs
How much does it cost to refinance a $300,000 mortgage?
On average, for a $300,000 loan, you can expect total closing costs to range between $6,000 and $18,000. This includes lender fees, title work, and your prepaid escrow items. The "sunk costs" (fees that don't go toward your escrow) are typically around $3,000 - $5,000.
Are refinance costs tax-deductible?
Generally, no. Unlike when you buy a home, standard closing costs on a refinance for a primary residence are not deductible. However, if you pay discount points to lower your rate, you can deduct them over the life of the loan. Note: For rental properties, these rules differ, and costs are often deductible as business expenses.
How many times can you refinance a mortgage?
There's no legal cap on how many times you can refinance. Most lenders do require a short waiting period between refinances — often around six months — and some loan types carry seasoning requirements before you can refinance again. For a Fannie Mae cash-out refinance, for example, the mortgage being paid off must be at least 12 months old. Just remember that every refinance comes with its own closing costs, so it only pays off if you clear a new break-even point each time.
Is it better to roll closing costs into the loan?
If you are short on cash, rolling costs into the loan balance is a convenient option. However, be aware that you will pay interest on those costs for the next 30 years. It's better to pay cash upfront if you can afford it to keep your loan balance low.
Why is my refinance quote higher than expected?
If your quote seems high, check the Prepaids section. You might be funding a brand new escrow account for taxes and insurance. Also, if your credit score has dipped or you are taking cash out, lenders may have applied risk-based fees (LLPAs) that drove up the cost.
Final Verdict: Is Refinancing Worth the Cost in 2026?
Refinancing was never about bragging rights over the lowest rate at a dinner party. It's a math problem, and the math has to work in your favor before it makes sense to sign anything.
Rates have moved around plenty this year and are back above 7% this fall, so if you're still sitting on something near 8% or higher, current pricing may well be worth a serious look. Clear your break-even point with room to spare, and the upfront cost becomes a short-term hurdle standing in front of real long-term savings.
One last piece of advice: don't take the first number you're handed. Loan officer compensation structures vary widely, and so do the fees they quote.
That's exactly why I keep pointing people to Bluerate.ai. It lets you compare rates, fees and loan terms up front and connect with loan officers near you before you commit.
Run your numbers, compare a few quotes, and make 2026 the year you finally take control of your mortgage.