

Last Checked and Updated on September, 2026
Many first-time buyers sit across from a mortgage broker, ready to buy their first home, only to get hit with a question that stalls the whole process: "Are you a W-2 employee or a 1099 worker?" If you've ever applied for a loan, you know that particular flavor of panic. Your income classification shapes far more than your tax return; it can decide your approval odds on some of the biggest purchases of your life.
If you're trying to sort this out in 2026, a quick chat with local loan officers for a free consultation can save you a lot of frustration down the road. But before you make any career leaps, let's break down exactly what separates a 1099 Form from a W-2 and figure out which path actually fits you best.
What is a 1099 Form?
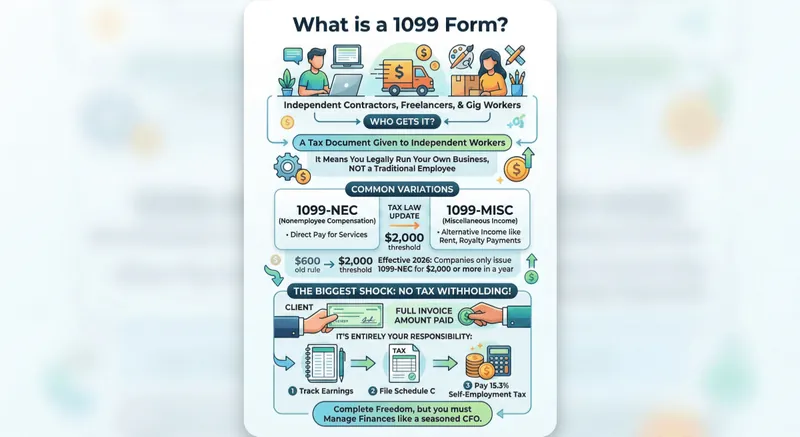
So, what is a 1099 form, exactly? Per IRS guidelines, a 1099 is the tax document sent to independent contractors, freelancers, and gig workers. If you receive one, you're running your own small business in the eyes of the law, not clocking in as someone's employee.
A few versions of this form show up often. The most common is the 1099-NEC, which stands for Nonemployee Compensation and covers direct payment for services. The reporting rule around it just changed, too: starting with payments made in 2026, a business only has to send you a 1099-NEC once your yearly total hits $2,000, up from the $600 threshold that had sat untouched since 1954. The 1099-MISC, on the other hand, handles other income types like rent or royalty payments.
The part that catches newcomers off guard is usually the missing withholding. Clients pay you the full invoice amount, and nobody sets aside a dime for the government. Tracking your own earnings, filing a Schedule C, and covering the 15.3% self-employment tax become entirely your responsibility. You get real independence, but the IRS expects you to manage your money like the business owner you technically are.
What is a W-2 Form?
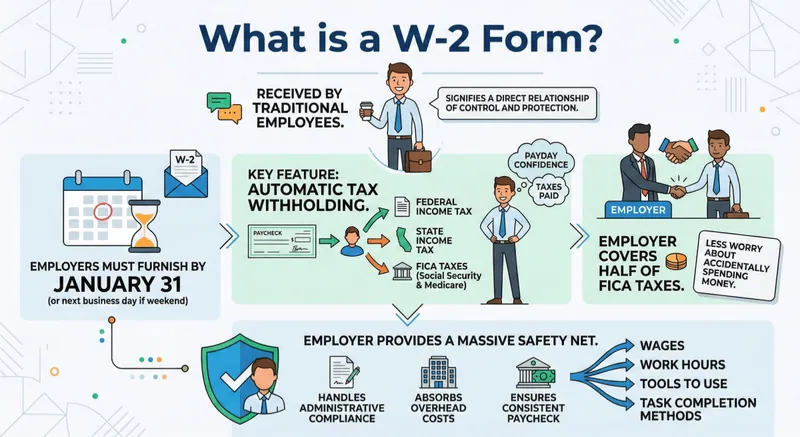
On the other side, getting a W-2 puts you in the traditional employee bucket. Employers have to send W-2 forms out by January 31, or the next business day if that date lands on a weekend. The sheer convenience is genuinely hard to beat.
The defining trait here is automatic tax withholding. Every payday, your employer's payroll system deducts federal and state income tax along with your share of FICA, which funds Social Security and Medicare. You're never at risk of accidentally spending money that belongs to the IRS, and your employer covers half of those FICA contributions on your behalf, a perk contractors simply don't get.
A W-2 also reflects a relationship built on control in exchange for protection. Your company decides your hours, your tools, and how the work gets done. In return for that trade-off, you get a real safety net: the business absorbs overhead, manages the compliance headaches, and keeps your paycheck landing on schedule.
1099 vs W-2: Key Differences Explained
Choosing between these two paths isn't just about how you file taxes each spring. It reshapes your daily routine, your baseline income stability, and your legal standing. Let's walk through the differences that matter most.
Taxes
As a W-2 employee, your tax burden feels fairly light. You cover 7.65% for your half of FICA, while your employer picks up the rest. Independent workers shoulder the full 15.3% self-employment tax alone, since the IRS treats you as both the employee and the employer. That chunk comes out of your net earnings before federal and state income taxes even enter the picture.
There's a ceiling worth knowing about, too. In 2026, the Social Security portion of that tax only applies up to $184,500 in net earnings, the year's wage base. Past that point, only the 2.9% Medicare share keeps going, and once your income crosses $200,000, an additional 0.9% Medicare surtax kicks in. It's a detail that matters most for higher-earning contractors, but it's worth building into your planning either way.
Winner for Tax Simplicity: W-2
Benefits
Corporate perks are often the golden handcuffs that keep people happily tied to a steady paycheck. W-2 status usually unlocks subsidized health insurance, an employer-matched 401(k), paid time off, and sometimes vision or dental coverage. Add it all up, and those extras can be worth tens of thousands of dollars a year. A 1099 contractor doesn't get any of it automatically. Want a week off? You simply stop earning for those days. Need health coverage? You're shopping the open marketplace and paying full premiums out of your own pocket.
Winner for Comprehensive Benefits: W-2
Control
Nothing beats setting your own alarm clock. Contractors work with genuine autonomy, choosing their schedule, their projects, and whether today's office is a coffee shop or a beach halfway around the world. Clients are paying for results, not your physical presence. W-2 employees, meanwhile, follow the company rulebook: your manager sets your hours, your location, and often the method behind the work itself. If creative freedom matters more to you than structure, contracting wins by a landslide.
Winner for Flexibility and Control: 1099
Expenses
This is where independent workers finally get to strike back against the tax code. The deduction for unreimbursed employee business expenses, things like a laptop, home office, or commuting costs, was suspended under 2018 tax law and has now been permanently eliminated at the federal level; a handful of states, including California and New York, still allow a version of it on state returns. Contractors face no such restriction. You can legally write off a share of your home office, internet bill, mileage, software subscriptions, and equipment. Every legitimate purchase lowers your taxable income, and with disciplined record-keeping, those deductions can meaningfully soften the blow of self-employment tax.
Winner for Tax Deductions: 1099
Tax Forms
Filing season as a W-2 employee is refreshingly quick. Import your single wage document, take the standard deduction, and you're often finished in twenty minutes. Self-employed filers face a much heavier lift. You need to gather every income source, complete Schedule C to claim business expenses, and calculate self-employment tax on Schedule SE. To dodge IRS underpayment penalties, you also have to estimate your annual earnings and send quarterly payments four times a year.
Winner for Easy Filing: W-2
Legal Protections
Always plan for the worst-case scenario. If a company lays off its staff, W-2 employees can apply for state unemployment benefits right away. They're also guaranteed minimum wage, overtime pay for long weeks, and workers' compensation if they get hurt on the job. None of that applies to contractors. Lose a major client overnight, and you can't collect unemployment. Spend twice as long as planned on a flat-fee project, and no law requires anyone to pay you overtime. You're carrying the full risk yourself.
Winner for Legal Safety: W-2
Work Type
Your current stage in life often decides the better fit. A W-2 role suits anyone who values predictability, wants to climb a structured career ladder, or needs steady monthly income to support a family without added stress. A 1099 setup, on the other hand, is built for side hustlers, project-based consultants, and people who want their income to scale with effort instead of a fixed salary band. If you've got an entrepreneurial streak, independence usually pays off.
Winner for Entrepreneurial Growth: 1099
W-2 vs 1099 Comparison Chart
Here's a quick side-by-side so you don't have to reread the sections above:
| Category | W-2 Employee | 1099 Contractor |
|---|---|---|
| Tax Rate | 7.65% FICA (employer covers the rest) | 15.3% self-employment tax |
| Withholding | Automatic, every paycheck | None — you set aside your own |
| Benefits | Health insurance, 401(k) match, PTO | Not provided; fully self-funded |
| Control | Employer sets hours and methods | You set your own schedule and process |
| Expense Deductions | Not deductible on federal returns | Deductible through Schedule C |
| Tax Filing | One form, minimal paperwork | Schedule C, Schedule SE, quarterly payments |
| Legal Protections | Unemployment, minimum wage, overtime | None of the above |
| Best Fit For | Stability and predictable income | Flexibility and unlimited upside |
Source: IRS Topic 751 and IRS Self-Employment Tax, checked October 2026.
Other Tax Forms People Often Confuse with W-2 or 1099
A W-2 and a 1099-NEC aren't the only forms floating around at tax time, and it's easy to mix them up. Here's a quick rundown of the ones that trip people up most:
- 1099-R reports withdrawals from a pension, retirement account, or annuity. It has nothing to do with wages or contract work.
- 1099-G covers government payments, most often unemployment compensation or a state tax refund.
- 1099-K reports payments processed through third-party platforms like PayPal, Venmo, or Uber. As of 2026, it only applies once you cross $20,000 and 200 transactions in a year, and it typically shows up alongside a 1099-NEC rather than replacing it.
- 1099-INT and 1099-DIV report bank interest and investment dividends, generally once they reach $10 for the year.
- 1099-B reports stock and other sales through a broker, and 1099-DA, new for digital asset sales starting in 2025, does the same for crypto.
- 1098 reports the mortgage interest you paid during the year. Your lender sends this one, not your employer, and it has no connection to how you earned your income. Your mortgage servicer can also send a 1099: a 1099-INT if your escrow account earned $10 or more in interest, a 1099-C if $600 or more of the debt was canceled, or a 1099-A if the lender took the property back in full or partial payment of the loan or learned it was abandoned.
- 1095-A, B, or C confirm your health insurance coverage; none of them report income.
- Form 1040 is your actual tax return, the document you file with the IRS every year. Your W-2 or 1099 feeds numbers into your 1040; it doesn't replace it.
- W-3 and W-4 get mixed up with W-2 constantly, but neither one is something you personally receive at year-end. A W-4 is what you fill out when you're hired to set your withholding, and a W-3 is a summary your employer files with the Social Security Administration.
Knowing which form applies to your situation saves you from chasing down the wrong paperwork every single tax season.
When Your W-2 and 1099s Arrive, and What to Do If One Is Missing
Employers must send W-2s, and most payers must send 1099-NEC, 1099-MISC, 1099-INT and 1099-DIV forms, by January 31, or the next business day when that date falls on a weekend. Brokers have until February 15 for 1099-B and 1099-DA. Many payers post the form online first, so check the tax documents page of each client portal, payroll service or payment app before waiting on the mail.
If a form still hasn't shown up:
- Ask the payer. For a missing W-2, the IRS says to contact your employer first. If it hasn't arrived by the end of February, call the IRS at 800-829-1040; it will contact the employer for you and send Form 4852, a substitute form you can file using your own estimates.
- Pull a Wage and Income Transcript from your IRS Individual Online Account. It lists the W-2, 1098 and 1099 data that payers filed with the IRS for the current and nine prior years, and current-year data generally starts appearing in the first week of February. A form the payer never filed with the IRS won't be on it.
- Report the income anyway. A missing 1099 doesn't make the money tax-free. Total what each client paid you from your invoices and bank deposits and report it on Schedule C.
Before you hand 1099s to a lender, check that your name and taxpayer ID are right and that the amounts match your deposits. If they don't, ask the payer for a corrected form, since the lender will compare them with your IRS transcripts.
Source: IRS Topic 154, IRS transcript types and IRS General Instructions for Certain Information Returns, checked November 2026.
How Mortgage Lenders Verify Your 1099 Income
Here's where your classification really comes back around: buying a home. If you're on a W-2, a lender mostly cares about your last couple of pay stubs and a quick verification-of-employment call. If you're on a 1099, expect a much closer look. Underwriters typically want two years of tax returns and average your income across that period, which can work against you if last year happened to be your best one yet.
The good news is there are options beyond the standard route. Bank statement loans let qualifying self-employed borrowers use 12 to 24 months of deposits instead of tax returns, and profit-and-loss statement programs offer a similar path for borrowers whose returns don't fully reflect what they're actually earning now. Both fall under Non-QM lending, and both exist specifically because so many 1099 workers get squeezed out by conventional underwriting rules.
This is exactly the kind of guideline detail that used to take hours to track down across dozens of lender rulebooks. Tools like Zeitro Strata now let loan officers upload a borrower's 1099s or bank statements and get an instant, source-backed income calculation, along with guideline answers pulled from over 100 investor rulebooks in seconds. If you're a 1099 worker prepping for a mortgage application, it's worth asking your loan officer whether they have something similar in their toolkit.
FAQs About 1099 Form vs W-2
Q1. Is a 1099 the Same as a W-2?
No. A W-2 reports wages for a traditional employee with taxes already withheld, while a 1099 reports payments made to an independent contractor with nothing withheld at all. They describe two entirely different working relationships, not two versions of the same document.
Q2. Is It Better to Be a W-2 Employee or 1099?
There's no single right answer. If you prioritize peace of mind, reliable benefits, and legal workplace protections, the W-2 path fits better. If you want unlimited earning potential, bigger tax write-offs, and the freedom of being your own boss, 1099 work makes more sense.
Q3. Are 1099 Taxes Higher Than W-2?
Usually, yes. Independent workers pay the full 15.3% self-employment tax alone, while traditional employees only pay 7.65% because their employer covers the rest. That said, contractors who lean into business deductions can meaningfully shrink their taxable base.
Q4. Why Do Companies Use 1099 Instead of W-2?
Businesses often prefer contractors to cut operational costs. Hiring freelancers means skipping health insurance premiums, payroll tax matching, and paid leave, while gaining the flexibility to scale a team up or down quickly.
Q5. What Are the Disadvantages of a 1099 Job?
The biggest drawbacks are unpredictable income and zero paid time off. You also carry the administrative load of quarterly tax estimates, hunting for private health coverage, and facing a noticeably stricter underwriting process when you apply for a mortgage or personal loan.
Q6. How Much Should I Save from Every 1099 Payment?
Most freelancers aim to set aside roughly 25-30% of each client payment. Skip that habit, miss a quarterly deadline, or lose track of your deductible expenses, and you can end up with a painful, unexpected tax bill in April.
Q7. How Much Tax Do I Pay on a 1099?
Beyond your regular federal and state income tax brackets, you owe a flat 15.3% self-employment tax on your net business profit. For example, on $100,000 of net profit, that works out to roughly $14,130, since the tax applies to 92.35% of your net earnings, and half of that amount is deductible from your income tax.
Q8. Can an Employer Force Me to Be a 1099?
No. The IRS applies specific behavioral and financial control tests to determine proper worker classification, and paperwork alone doesn't decide it. If a company dictates your schedule, tools, and methods, you're legally an employee no matter what form they hand you. Getting this wrong isn't a minor slip either: a company caught misclassifying workers can owe back payroll taxes, penalties, and the employer-side FICA contributions it should have paid from day one, with steeper consequences if the IRS decides it was intentional.
Q9. What Happens If I Don't Report a 1099?
The IRS gets its own copy of every 1099 and matches it against your return. When the income that payers reported doesn't match what you reported, it sends a CP2000 notice proposing changes to your tax. Report the income even if the form never arrived.
Q10. How Many Years of 1099 Income Do I Need for a Mortgage?
For a conventional loan, Fannie Mae generally wants a two-year history of self-employment income. A shorter history can work if your most recent signed tax return shows a full 12 months of income from the current business and you previously earned at least as much in the same field or a role with similar responsibilities. If the business has existed for five years and you've owned at least 25% of it for all five, one year of tax returns may be enough (Fannie Mae Selling Guide B3-3.5-01).
Q11. Why Does My Lender Want IRS Transcripts If I Already Sent My 1099s?
Fannie Mae requires each borrower whose income is used to qualify to sign a separate IRS Form 4506-C at or before closing, which lets the lender pull tax transcripts and check them against the returns and forms you provided. The exception is a borrower whose income is all validated through DU's validation service (Fannie Mae Selling Guide B3-3.1-02).
Final Word: When to Use Which?
At the end of the day, a W-2 offers real safety and structure, while a 1099 hands you freedom and unlimited upside. The right choice comes down to what season of life you're navigating right now.
That said, your classification matters even more once you're ready to buy a house. Lenders won't settle for a quick glance at a pay stub if you're self-employed; they'll dig into years of returns and want to understand exactly how your income holds up. Want to know how your 1099 income affects your home-buying eligibility? Check out Zeitro to verify current mortgage guidelines for contractors and self-employed borrowers. Getting ahead of the paperwork now means your dream home doesn't slip away over a technicality later.