Written by
Eric
Share this article


Subscribe to updates
Last Checked and Updated on September, 2026
f you're a loan officer or broker in today's market, you already know the "guideline grind." Non-QM and niche products aren't optional anymore, they're how deals get done. Non-QM securitizations hit a record $20.9 billion in the third quarter of 2025, according to Morningstar DBRS, nearly double the volume from the same period a year earlier. We're all working more complex files than we used to.
I've spent hours scrolling through 500-page PDFs hunting for a single overlay. It kills momentum, and it kills deals. Before I get into the tool I now use to verify mortgage eligibility in seconds, let's cover what actually determines eligibility in the first place, because knowing the "what" makes the "how" click a lot faster.
What Determines Mortgage Eligibility?
Every underwriter, human or AI, is weighing the same handful of factors. Here's how they typically break down:
- Credit score. Requirements vary by loan type. Conventional loans usually want 620 or higher, FHA will go as low as 580 (or 500 with 10% down), and VA loans have no hard federal minimum, though most lenders set their own floor around 580-620. Non-QM products like DSCR or bank statement loans often start closer to 660-680.
- Debt-to-income (DTI) ratio. Conventional loans can stretch to around 45-50% with strong compensating factors through automated underwriting, FHA allows up to 50% in many cases, and VA leans more on residual income than a hard DTI ceiling.
- Loan-to-value (LTV) and down payment. Conventional financing typically starts at 3-5% down, FHA at 3.5%, and VA or USDA can reach 0% down for eligible borrowers. Non-QM and DSCR loans usually require 20-25% down. For context, the 2026 baseline conforming loan limit sits at $832,750 in most counties, rising to $1,249,125 in high-cost areas, per the FHFA. Go above that and you're typically shopping for a jumbo loan instead.
- Income and employment history. W-2 borrowers lean on pay stubs and tax transcripts. Self-employed borrowers often need two years of returns, or can use Non-QM alternatives like 12- or 24-month bank statements or a profit-and-loss-only program.
- Reserves and assets. Lenders like to see a cushion, usually somewhere between two and six months of PITI, depending on loan type and whether the property is a primary residence, second home, or investment.
None of these boxes exist just to slow you down. Together, they're how a lender predicts whether a borrower can actually repay the loan, and getting even one assumption wrong can turn a strong file into a painful decline.
Why Do You Need to Determine Mortgage Eligibility?
In my experience, speed to lead is only half the battle. Speed to answer is what actually closes deals. Sorting out eligibility upfront isn't just about compliance boxes. It protects your most valuable asset: time.
Margins made that painfully clear in 2025. Per-loan profits for independent mortgage banks swung from a $28 loss per loan in the first quarter to a $1,201 high in the third, averaging $443 for the full year, according to Mortgage Bankers Association data. When margins move like that, you simply can't afford to burn "green time" on a file underwriting is going to reject anyway.
Sorting eligibility early helps in a few concrete ways:
- Build instant authority. When I can tell a self-employed borrower exactly why they qualify for a Bank Statement loan on the first call, I win their trust right away.
- Cut down on fallout. Misreading a DSCR or ITIN guideline leads to dead files and frustrated real estate agents.
- Maximize throughput. Top producers aren't necessarily smarter, they're more efficient. Filtering out non-starters in seconds means you spend your energy on files that actually close.
Also Read:
- Best AI Mortgage Underwriting Software for Loan Professionals
- Max DTI for Mortgage: Requirements By Loan Types

How to Determine Mortgage Eligibility Using Zeitro Strata?
When I first tried Zeitro Strata, it changed how I work. It's an AI-native assistant built specifically for the complexity of this industry, and it doesn't guess. It cross-checks over 1,000 guidelines from 100+ investors, including names like AAA Lending, Freedom Mortgage, and HomeXpress.
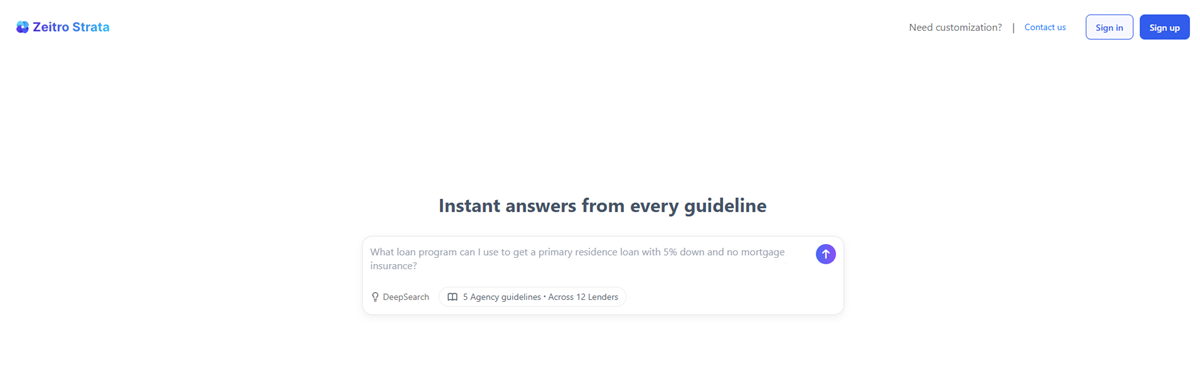
Here's how I use it to get answers in real time:
- Define your scope. I start by selecting the specific guidelines or investors I want to search. On a tricky Non-QM case, I'll tag "Asset Utilization" or "Foreign National" to narrow things down.
- Ask your scenario. I type in questions the way I'd ask an account executive. For example: "What's the max LTV for a 680 FICO borrower using 12-month bank statements on a primary residence?"
- Review cited answers. Within seconds, Strata returns a precise answer, and every one comes with a citation. I can click through to see the exact paragraph in the lender's manual, which keeps me confident I'm quoting something accurate.
- Go deeper with "Explain." When a guideline is dense, I use the Explain feature. It re-analyzes the source and breaks down the logic, which has saved me more than once on complex vesting or income-layering questions.
What Else Can Zeitro Do for You?
Beyond guideline verification, Zeitro's ecosystem has quietly replaced several tools I used to pay for separately. It's a full-stack setup for the modern originator.
- GrowthHub: I use this to run a branded microsite. It's built for SEO, so it helps me capture organic leads by showcasing my expertise and live rates in a clean, professional format.
- Digital 1003 (POS): This has changed the borrower experience for me. It's a mobile-friendly application that calculates DTI in real time and exports data in FNM 3.4 format, which my processors genuinely appreciate.
- Pricing Engine: I can pull accurate quotes for both QM and Non-QM products in seconds. Applying custom overlays directly in the engine means the quote I give is the quote a borrower actually gets.
FAQs About Determining Mortgage Eligibility
Q1. What credit score do I need to qualify for a mortgage?
It depends on the loan type. Conventional loans generally start at 620, FHA can go as low as 580 (or 500 with a 10% down payment), and VA loans have no federal minimum, though lenders usually apply their own floor. Non-QM programs, like DSCR or bank statement loans, tend to start higher, often 660-680.
Q2. What DTI ratio do lenders look for?
Most conventional loans top out around 45%, though automated underwriting can push that to 50% with strong compensating factors like extra reserves or a higher credit score. FHA allows up to 50% in many cases, while VA weighs residual income more heavily than a fixed DTI ceiling.
Q3. How accurate is the AI when reading these guidelines?
It's built on source transparency. Unlike a general-purpose AI, Zeitro Strata links every answer to a specific investor's PDF, so you can verify the source yourself in one click instead of taking its word for it.
Q4. Does it support complex Non-QM products?
Yes, and this is where it really shines. It covers DSCR, ITIN, Bank Statement, P&L-only, and Asset Utilization scenarios across 100+ investors.
Q5. How often are the guidelines updated?
Continuously. As lenders release new announcements or revise their manuals, Strata indexes that data so you're never working off a stale PDF.
Q6. Can I use it for free?
Yes, Zeitro offers 3 free queries a day, which is enough to test a few tough scenarios before deciding whether to upgrade.
Q7. Is the data secure for my borrowers?
Yes. Zeitro is SOC 2 Type II certified, meeting enterprise-grade standards for protecting financial data.
Conclusion
The mortgage landscape keeps shifting, and the loan officer who still relies on manual guideline research is falling behind. Since folding Zeitro Strata into my daily workflow, I've saved over 7 hours per loan file, closed loans up to 20% faster, and closed roughly 30% more loans overall.
Whether you're untangling a Foreign National file or just need a quick answer on FHA overlays, knowing exactly what determines eligibility, and being able to verify it in seconds, is a real competitive edge. Don't let your "green time" get eaten up by PDF research. I'd recommend visiting Zeitro to see how these tools can help you close faster and build a more resilient business.