Written by
Eric
Share this article


Subscribe to updates
Last Checked and Updated on August, 2026
If you've been originating loans as long as I have, you know that finding the exact maximum Debt-to-Income (DTI) ratio in 2026 feels like hitting a moving target. Every single loan program and investor overlay seems to have its own strict ceiling. It is complex, time-consuming, and honestly, a massive headache for loan officers trying to pre-qualify borrowers quickly.
Instead of digging through hundreds of pages of PDF guidelines, I now use Zeitro Strata AI. It's a free, AI-powered mortgage assistant that instantly cross-checks different lender guidelines to give you exact max DTI requirements in seconds. Let's break down the 2026 standards and how you can stop wasting time on manual lookups.
Why Does a Maximum DTI Even Exist?
Debt-to-income ratio is simply the math lenders use to judge whether someone can realistically carry a new mortgage payment on top of what they already owe. It's not arbitrary paperwork — it exists for a few concrete reasons:
- Risk control. A lender that ignores DTI ends up holding loans that default at a much higher rate, which eventually gets passed on to everyone through tighter credit.
- Ability-to-Repay compliance. Under the CFPB's Ability-to-Repay rule, originators are legally required to verify a borrower can afford the payment before closing the loan.
- Investor eligibility. If you want to sell the loan to Fannie Mae, Freddie Mac, or a private investor, the file has to land inside whatever DTI band that buyer will accept.
Typical Maximum DTI by Loan Type
Keep in mind, these baseline limits often change depending on specific lender overlays. But based on the 2026 landscape, here is the standard breakdown of maximum DTI by loan type:
- Conventional: 36% - 45%, can stretch up to 50% with strong compensating factors and DU/LPA approval.
- FHA Loan: 43%, with an automated underwriting system (AUS) approval and strong compensating factors, it can hit 50% or even up to 56.9%.
- USDA Loan: 29%, front / 41% Back, Strict limits, but the Guaranteed Underwriting System (GUS) might push it slightly higher.
- VA Loan: 41%, benchmark, No hard legal cap. VA cares more about meeting the Residual Income requirement.
- HELOC: 43% - 50%, varies heavily by the specific bank or credit union.
- Jumbo Loans: 43%, highly conservative. Rarely allows exceptions above this line.
- Non-QM Loan: 50% - 55%+, extremely flexible. Programs like DSCR don't even use personal DTI.
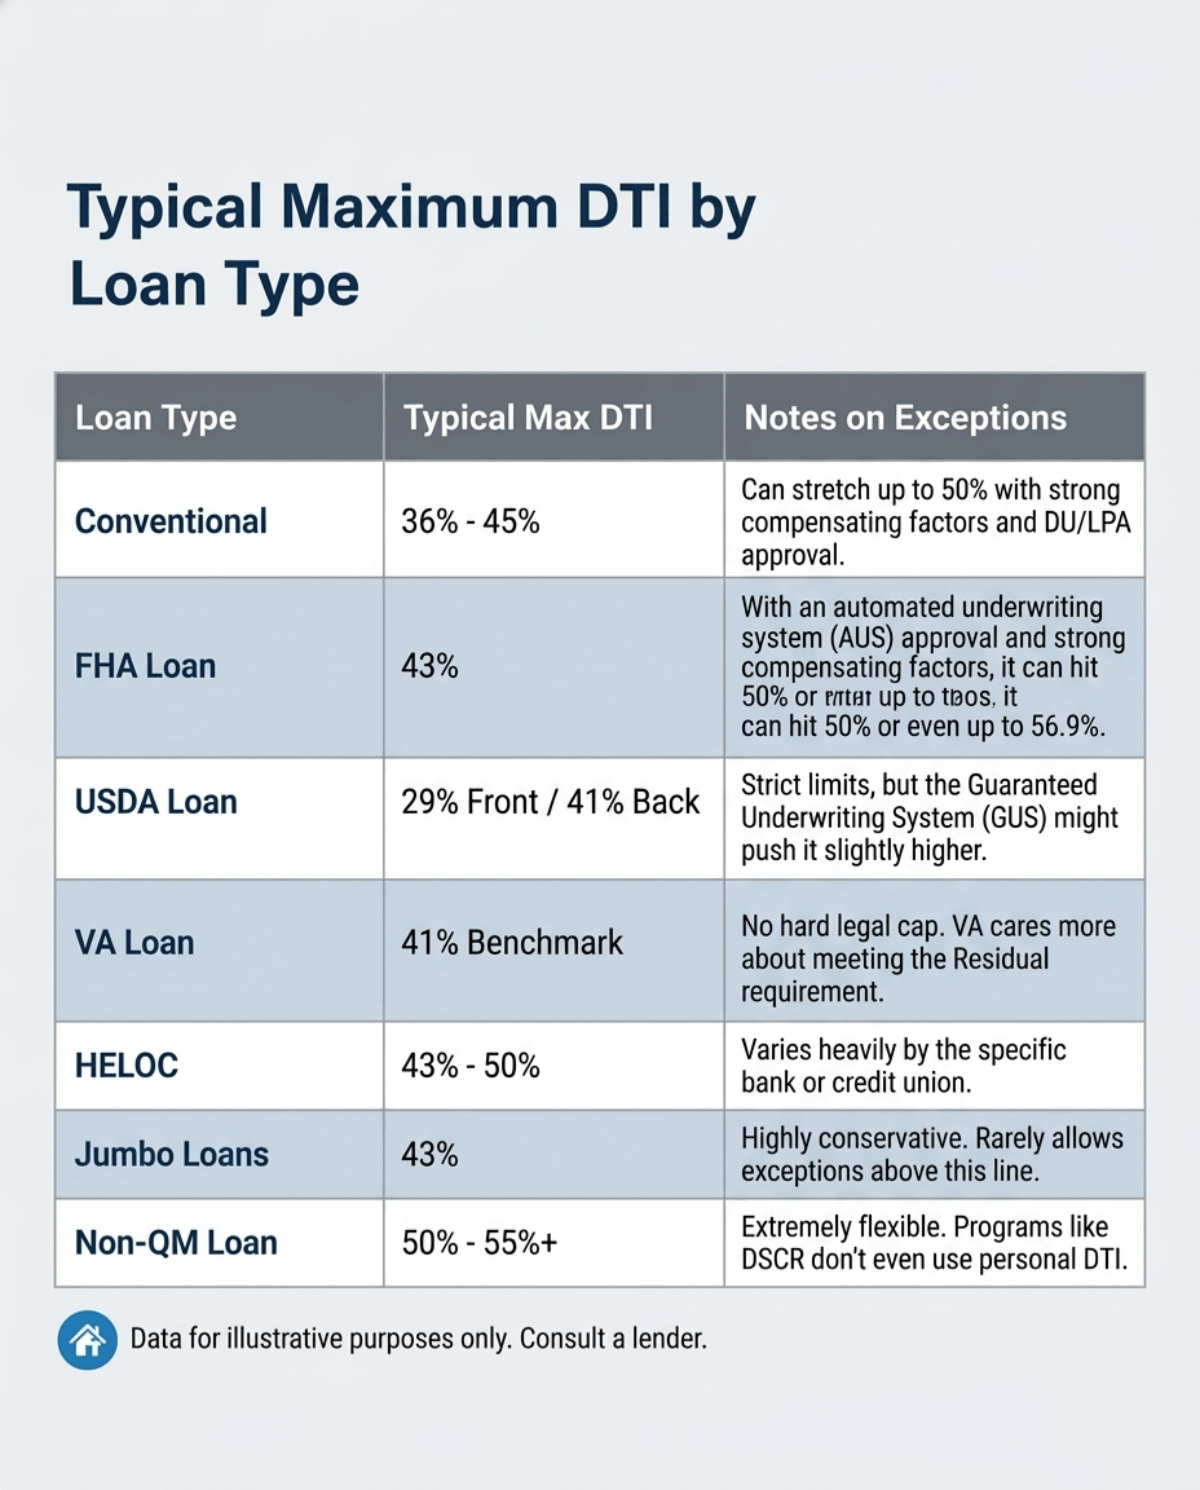
As you can see, the spread is massive. A borrower who gets denied for a Jumbo might easily slide into a Non-QM product if you know where to look.
Fannie Mae vs. Freddie Mac: What DU and LPA Actually Allow
This is the part most articles gloss over, and it's the question I get asked the most. Fannie Mae and Freddie Mac don't publish a single DTI ceiling — they publish three, and which one applies depends entirely on how the loan gets underwritten.
For a manually underwritten Fannie Mae loan, the baseline max is 36%. Meet the credit score and reserve thresholds on Fannie Mae's Eligibility Matrix, and that can stretch to 45%. Run the same file through Desktop Underwriter (DU), and an "Approve/Eligible" finding can support a DTI as high as 50% — DU is weighing the whole risk picture, not just the ratio, so a strong FICO score or healthy reserves can carry a file that a spreadsheet alone would reject.
Freddie Mac works on a similar structure through its own automated system, Loan Product Advisor (LPA). Manually underwritten Freddie Mac loans typically cap around 43–45% depending on the product, while an LPA "Accept" recommendation can clear DTIs up to 50% in solid risk classes. Neither GSE guarantees approval at that top ceiling — it's a possibility, not a promise — but it explains why two borrowers with identical debt loads can get completely different answers depending on which system reviewed the file.
Is There Still a 43% DTI Rule?
Borrowers ask me this constantly, usually because they read it somewhere years ago and it stuck. Here's the short version: the hard 43% DTI cap for Qualified Mortgages went away in 2021.
Before that, general Qualified Mortgages were capped at 43% DTI, with an exception (the "GSE Patch") that let Fannie Mae- and Freddie Mac-eligible loans skip that cap entirely. When the patch expired, the CFPB replaced the DTI test with a price-based standard instead. Under the current rule, a loan qualifies for QM safe harbor status as long as its APR doesn't exceed the Average Prime Offer Rate by more than 2.25 percentage points — DTI is still something every lender documents and considers, but it's no longer the line that determines Qualified Mortgage status on its own. Plenty of lenders still treat 43% as an internal comfort zone out of habit, which is part of why the number refuses to die.
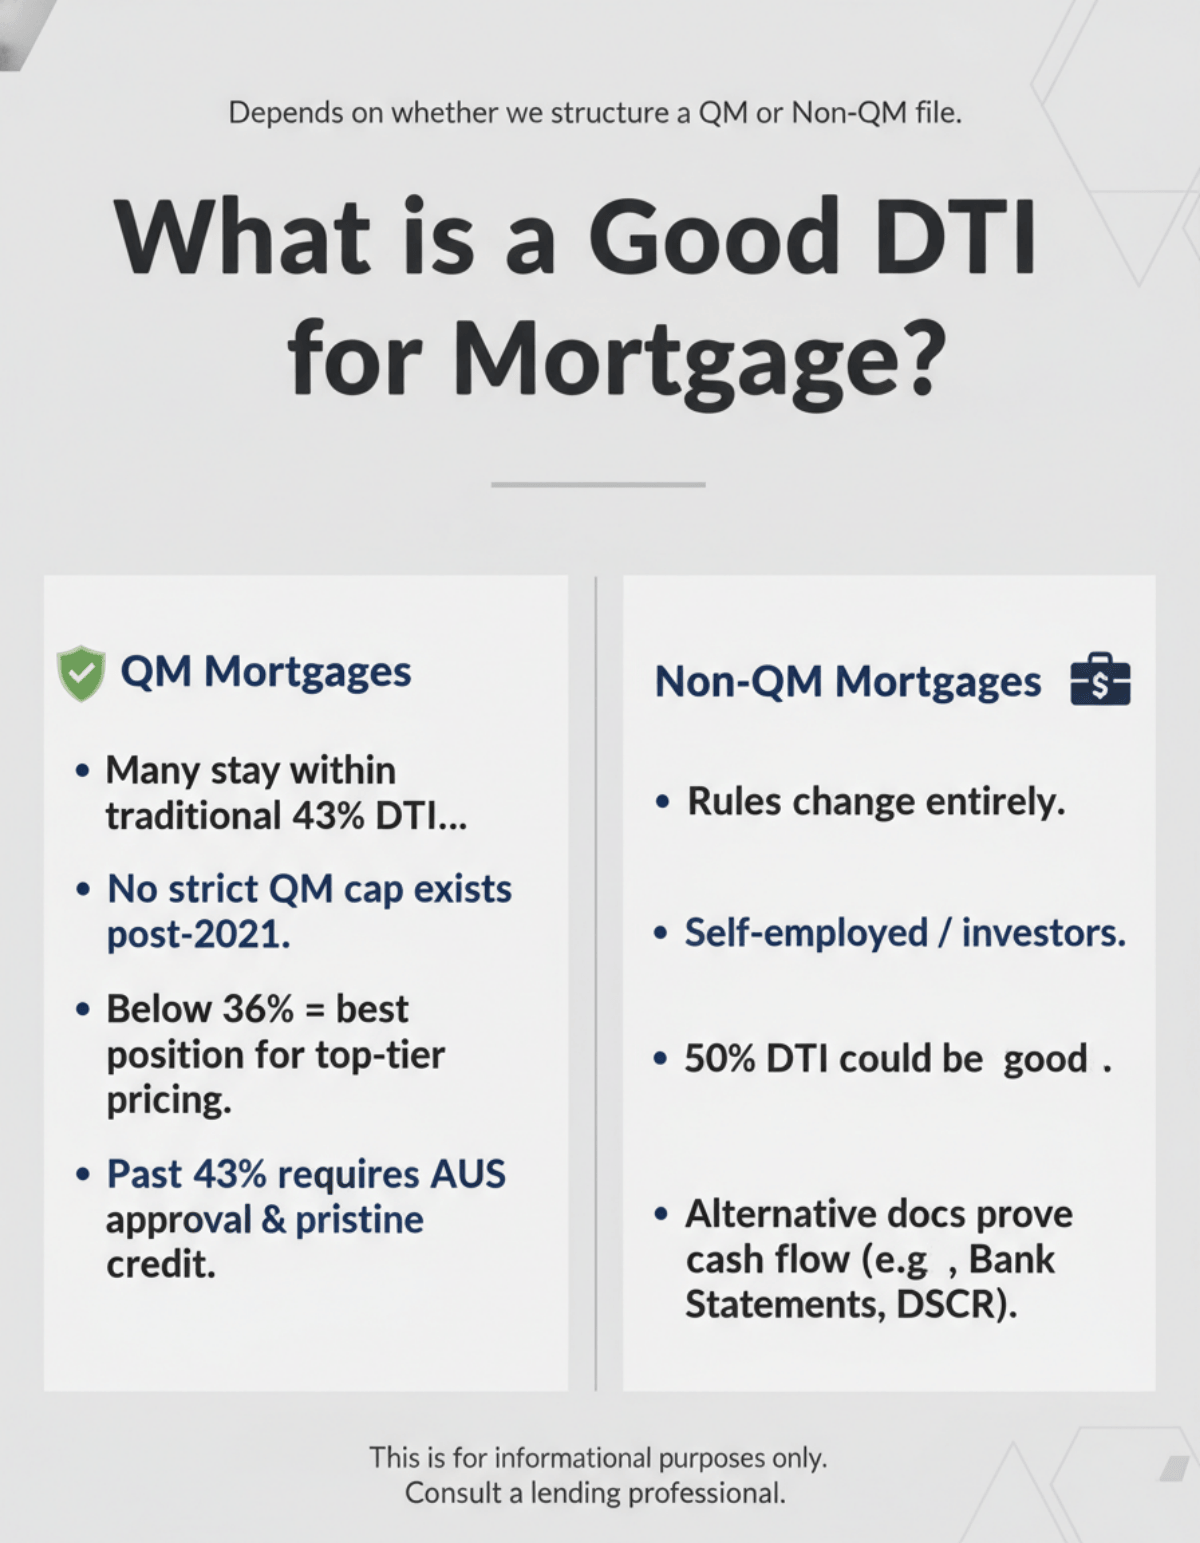
What is a Good DTI for Mortgage?
When a client asks me, "What's a good number?", my answer always depends on whether we are structuring a QM (Qualified Mortgage) or a Non-QM file.
- QM Mortgages: Many stay within traditional 43% DTI for conservative underwriting, though no strict QM cap exists post-2021 revisions. If your borrower stays at or below 36%, they are in the best position for top-tier pricing and a smooth clear-to-close. Pushing past 43% usually requires automated underwriting approvals and pristine credit.
- Non-QM Mortgages: The rules change entirely here. For self-employed borrowers or real estate investors using Asset Utilization or Bank Statement programs, a "good" DTI could easily be 50%. Since these products fall outside standard ATR guidelines, lenders rely on alternative documentation to prove cash flow rather than traditional backend ratios.
Front-End vs. Back-End DTI, in Plain English
These two terms trip up even experienced buyers, so it's worth a quick, direct answer. Front-end DTI only counts your future housing payment — principal, interest, taxes, insurance, and any HOA dues — against your gross monthly income. Back-end DTI adds everything else: car payments, student loans, credit cards, and any other recurring debt, on top of that housing payment. When someone quotes you a single DTI figure for a mortgage, they almost always mean the back-end number, since that's the one most guidelines are built around.
What Actually Moves Your DTI Ceiling
A published guideline is rarely the final word. A few variables shift the real ceiling for any given borrower:
- Compensating factors. A high credit score, a sizable down payment, or several months of cash reserves can convince an underwriter to approve a ratio above the standard cutoff. For FHA specifically, common accepted factors include verified cash reserves, a minimal increase in housing payment compared to current rent, documented residual income, or additional income that isn't otherwise counted toward qualifying.
- Lender overlays. This is the one that catches originators off guard most often. Fannie Mae might technically allow 50%, but your specific wholesale lender's internal policy could hard-stop at 45% regardless of what the GSE permits.
- Automated underwriting outcomes. A DU or LPA "Approve/Eligible" finding frequently unlocks a higher threshold than manual underwriting ever would, because the system is evaluating the full file rather than one ratio in isolation.
- Program-specific quirks. USDA loans lean on credit score to decide the underwriting path — a 640+ score typically routes through the automated Guaranteed Underwriting System, while anything lower usually means manual review with tighter ratios. VA loans skip a hard DTI ceiling almost entirely in favor of residual income tables that vary by region and household size, which is why a 41% DTI VA file and a 55% DTI VA file can both close without issue.
- Loan size. For 2026, the standard conforming loan limit is $832,750 in most counties and $1,249,125 in high-cost areas. Anything above that threshold falls into jumbo territory, where DTI tolerance tightens considerably regardless of how strong the rest of the file looks.
Quoting a single number to a borrower before checking the exact investor guide is how pre-approvals fall apart mid-transaction — I've seen it happen to good loan officers who just trusted their memory instead of double-checking.
Tip: How to Check DTI Guidelines Quickly and Accurately?
Memorizing overlays across dozens of investors isn't realistic, and I stopped trying years ago. These days I run scenarios through Zeitro Strata AI, a free AI-powered guideline assistant built specifically for mortgage professionals.
Strata has indexed more than 1,000 guidelines across mainstream and niche investors — Conventional, FHA, USDA, VA, DSCR, Bank Statement, Asset Utilization, ITIN, Foreign National, and more — from lenders including AAA Lending, AD Mortgage, Freedom Mortgage, and CMG Financial, with new sources added regularly. Type a question in plain English (or Chinese), and its DeepSearch feature cross-checks over 100 investors at once, cutting what used to be a 30-minute manual lookup down to a matter of seconds. Every answer comes with a citation you can trace back to the source page, and if something still isn't clear, the Explain feature breaks it down further. The free Explorer plan includes 10 daily queries, which covers most of what a busy origination day throws at you.
Strata also handles a few adjacent headaches: upload a pay stub or tax return and it will estimate qualifying income automatically, and it can look up Area Median Income figures or match a borrower to Down Payment Assistance programs available in their state.
Beyond Strata, Zeitro's broader platform covers the rest of the origination workflow:
- GrowthHub: Launch a branded personal microsite on Bluerate that improves local search visibility and captures leads directly from borrowers browsing rates in your area.
- Digital 1003 (POS): Let borrowers pre-qualify themselves, calculate DTI instantly with AI, and export completed applications in FNM 3.4 format for a clean handoff to your LOS.
- Pricing Engine: Pull live rate quotes across both conventional and Non-QM products, with overlay adjustments built in.
Loan officers using the platform report saving roughly 20 hours a month, while account executives and underwriters see closer to 18 hours saved per month — mostly from not re-verifying guidelines they've already looked up twice before.
Frequently Asked Questions about MAX DTI
Q1. What is the 33% mortgage rule?
It's a traditional front-end ratio guideline suggesting that your total monthly housing expenses, including principal, interest, taxes, and insurance, should not exceed 33% of your gross monthly income. Sticking to this rule helps ensure borrowers remain comfortable and aren't "house poor."
Q2. What is the 28 DTI rule?
The classic 28/36 rule states that a maximum of 28% of your gross monthly income should go toward housing expenses, while no more than 36% should go toward all total debt obligations combined, including car loans and credit cards.
Q3. What is the maximum DTI for better mortgage?
To secure the most competitive interest rates and ensure a highly favorable underwriting decision, you should aim for a total DTI of 36% or lower. Lenders view this range as low-risk, which translates to better pricing and fewer required compensating factors.
Q4. Is 39 DTI too high?
Not at all. A 39% DTI is considered a very safe and acceptable range in the mortgage industry. It easily falls under the maximum limits for Conventional, FHA, VA, and USDA loans, usually without needing any extra compensating factors.
Q5. Is 35% of income too much for a mortgage?
If 35% is your front-end housing ratio, it is slightly elevated but manageable. However, if 35% represents your back-end total debt ratio, it is actually an excellent, healthy financial position that will easily qualify for almost any loan program.
Q6. Is 42 DTI bad?
No, a 42% DTI is incredibly common. It sits right below the standard 43% cap used by many lenders. You will comfortably qualify for FHA and VA loans, and most Conventional loans will approve it as long as your credit score is decent.
Q7. Which loan programs allow the highest DTI?
Non-QM products — particularly Bank Statement and Asset Utilization programs — tend to allow the most room, often up to 50% or higher. DSCR loans go a step further and skip personal DTI entirely, basing approval on the property's rental income instead.
Q8. Which loan programs have the strictest DTI limits?
Jumbo loans are typically the tightest, usually capped near 43% with little room for exceptions, since these loans exceed conforming loan limits and carry more risk without government or GSE backing.
Conclusion
There isn't a single maximum DTI number for 2026 — there's a range that shifts based on loan type, underwriting system, and the specific investor buying the file. The job isn't memorizing every overlay; it's knowing where to look fast enough that a borrower doesn't lose a rate lock while you're digging through PDFs.
If manual guideline lookups are eating into your day, Zeitro is worth a look. The free Explorer plan gets you daily AI guideline queries, pricing engine access, and your own personal site — no cost to start, no reason to keep guessing on DTI limits.
People Also Read
- Mortgage Guidelines: What Are They? How to Verify?
- Non-QM Loan Guidelines: How to Check and Verify with AI Accuracy
- Best Mortgage Underwriter Certifications: Everything to Know Here
- Best Mortgage Underwriter Training Online: Improve Your Expertise
- What is Mortgage Eligibility Checker? Best Tool to Verify Guidelines
- [Guide] How to Calculate DTI Ratio for Mortgage?
- [Solved] What Debt-to-Income Ratio is Needed for a Mortgage?