

Sky-high prices and massive upfront cash requirements can be terrifying. But before you even tour a property, knowing the best first-time home buyer programs is absolutely vital.
It's easy to miss out on thousands of dollars in free grants simply by not knowing where to look. This guide breaks down reliable federal options and down payment assistance funds. These resources can seriously lower your upfront costs, secure better rates, or even provide direct cash help.
Key Takeaways
- Government-backed options shine: FHA, VA, and USDA loans offer the lowest barriers to entry, especially if your credit isn't flawless.
- Zero to low down payments are real: You don't need 20%. Many programs require only 0% to 3.5% down.
- Free money exists: National and local grants can cover your closing costs without needing repayment.
- Credit and DTI matter most: Your debt-to-income ratio and FICO score dictate which specific programs you actually qualify for.
Why Is It Important to Learn Programs First?
Jumping into house hunting without exploring financial aid is a huge mistake. Sellers and real estate agents won't hand you this information. You have to do the legwork yourself. Researching first gives you major advantages:
- Lower upfront costs: You can significantly reduce your initial cash outlay for closing fees and down payments.
- Better interest rates & terms: Government-supported options often secure more favorable lending terms than standard conventional mortgages.
- Broader qualification criteria: You might easily get approved even with limited income or a spotty credit history.
If you skip this step, you risk leaving thousands in "free money" on the table that could have made your dream affordable.
Top First-Time Home Buyer Programs
Federal and government-supported mortgages should be your first stop. They drastically reduce the friction of getting approved. The sections below compare the top choices by breaking down their target audience, minimum down payment ratios, and credit score requirements so you can find your match.
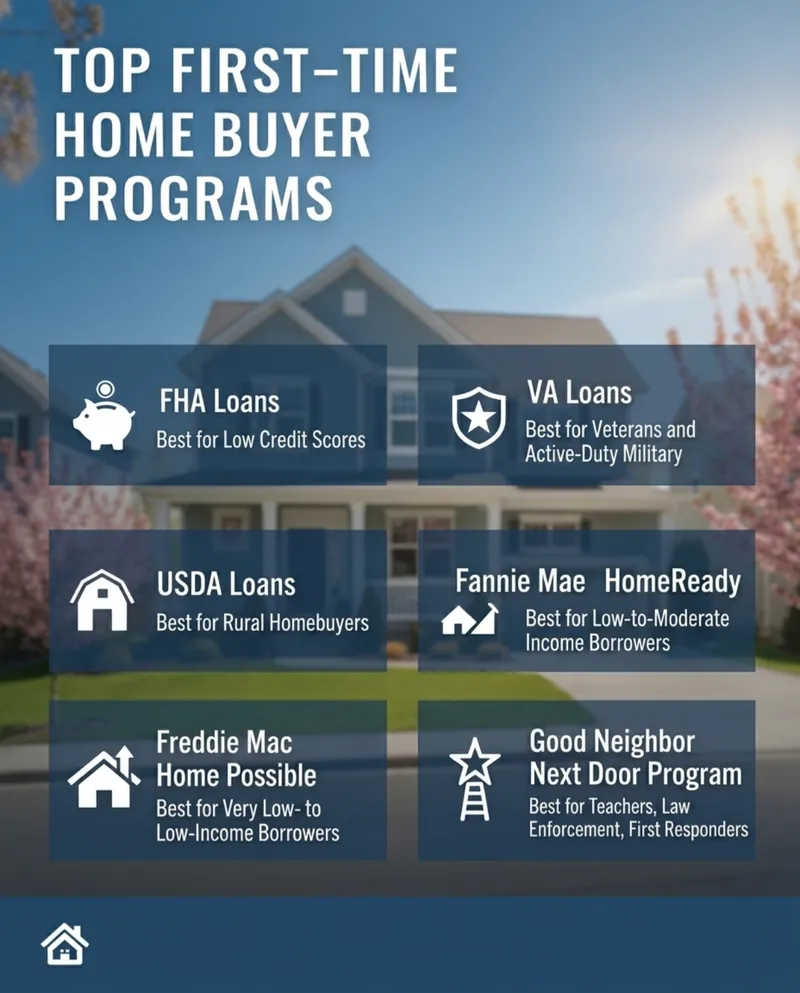
FHA Loans - Best for Low Credit Scores
For buyers with a few dings on their credit report, the Federal Housing Administration (FHA) loan can be a lifesaver. This government-backed mortgage is specifically designed to help buyers who might not qualify for traditional bank products. It's easily one of the most forgiving paths to homeownership.
Requirements include:
- Minimum Credit Score: You need at least a 580 FICO score for maximum financing. Scores between 500 and 579 still qualify, but require more cash upfront.
- Minimum Down Payment: Just 3.5% (for 580+ scores), or 10% for lower scores.
- Income/Location Limits: None.
- Mortgage Insurance: You must pay both an upfront Mortgage Insurance Premium (MIP) and annual premiums, regardless of your down payment size.
VA Loans - Best for Veterans and Active-Duty Military
If you have served in the military, stop looking elsewhere. The Department of Veterans Affairs backs the VA loan, which is arguably the most powerful mortgage product in the United States. This earned benefit completely removes the biggest hurdles of buying property.
Requirements include:
- Minimum Credit Score: The VA sets no official minimum, though most private lenders look for at least a 580 to 620.
- Minimum Down Payment: Absolutely 0% down is required.
- Income/Location Limits: No strict income limits, but you must have a valid Certificate of Eligibility (COE) proving your military service.
- Mortgage Insurance: No private mortgage insurance (PMI) is required, but you will pay a one-time VA funding fee upfront.
USDA Loans - Best for Rural Homebuyers
You don't have to buy a farm to get a USDA loan. Backed by the U.S. Department of Agriculture, this program actually covers many suburban neighborhoods located just outside major cities. It is meant to develop rural communities while making housing highly affordable for standard families.
Requirements include:
- Minimum Credit Score: Most lenders require a minimum FICO score of 640 for automated approval.
- Minimum Down Payment: 0% down payment required. You can finance the entire purchase price.
- Income/Location Limits: Your household income must fall within the USDA income limits for your area, which are typically set at or below about 115% of the area median income, depending on your county and household size.
- Mortgage Insurance: You pay an upfront guarantee fee and an annual fee, which are typically cheaper than standard FHA premiums.
Fannie Mae HomeReady - Best for Low-to-Moderate Income Borrowers
HomeReady is a conventional loan backed by Fannie Mae that competes directly with FHA. What stands out about this option is its flexibility. You can actually count rent from a roommate or relative who has lived with you for the past 12 months (boarder income, up to 30% of your qualifying income) to help you qualify. It's brilliant for younger buyers or multigenerational households.
Requirements include:
- Minimum Credit Score: No set minimum when Fannie Mae's Desktop Underwriter approves the loan. A manually underwritten loan needs at least 620, and more at higher loan-to-value ratios. Lenders can set a higher floor of their own.
- Minimum Down Payment: Just 3% down. Moreover, the funds can entirely come from gifts or grants.
- Income/Location Limits: Your income must be at or below 80% of your local Area Median Income (AMI).
- Mortgage Insurance: PMI is required since you are putting down less than 20%, but unlike FHA, you can cancel it once you build enough equity.
- Debt‑to‑Income: Your DTI is generally capped around 45%, though some lenders may allow slightly higher ratios under specific conditions.
Freddie Mac Home Possible - Best for Very Low- to Low-Income Borrowers
Similar to HomeReady, the Home Possible program is backed by Freddie Mac. This conventional mortgage is tailored to help buyers with limited funds finally break into the housing market. It's slightly stricter on credit but offers fantastic rate breaks and reduced insurance costs.
Requirements include:
- Minimum Credit Score: No set minimum when Freddie Mac's Loan Product Advisor accepts the loan; a manually underwritten one-unit fixed-rate purchase needs at least 660. Lenders can set a higher floor of their own.
- Minimum Down Payment: Only 3% down is required, and sweat equity (doing repairs yourself) can sometimes count toward this.
- Income/Location Limits: Your income cannot exceed 80% of your local AMI.
- Mortgage Insurance: PMI is mandatory but is offered at discounted rates. Like HomeReady, it can be canceled once your home equity reaches 20%.
- Debt‑to‑Income: Your DTI is generally capped at around 45%, though some lenders may allow slightly higher ratios under specific conditions.
Good Neighbor Next Door Program - Best for Teachers, Law Enforcement, First Responders
If you work in public service, this HUD-sponsored initiative is practically a steal. The Good Neighbor Next Door program encourages community revitalization by offering eligible properties at a massive discount. Officers and teachers can buy beautiful homes for literally half their appraised market value.
Requirements include:
- Minimum Credit Score: Usually follows standard FHA guidelines (580+), as you will likely use an FHA loan to finance it.
- Minimum Down Payment: With an FHA loan, you only need a $100 down payment.
- Income/Location Limits: You must buy a home in a HUD-designated "revitalization area."
- Mortgage Insurance: Standard FHA MIP applies.
- Special Condition: You must commit to living in the home as your sole residence for exactly three years.
Top Down Payment & Closing Cost Assistance
Down Payment Assistance (DPA) includes forgivable loans or direct grants that help cover your initial cash burden. We strongly advise layering these programs with your primary mortgage. Here is a breakdown of the best national funds and bank-specific grants available right now.
Before comparing amounts, check how the money is structured, because that decides what you owe later:
- Grants: Money you never repay, as long as you follow the program's rules.
- Forgivable second mortgages: A lien that is forgiven over time if you keep living in the home. Sell or refinance before the term ends and you may have to repay part of it.
- Deferred-payment second mortgages: No monthly payment, but the balance comes due when you sell, refinance or pay off the first mortgage.
- Repayable second mortgages: A low-rate second loan with its own monthly payment.
On a conventional loan, Fannie Mae's Community Seconds rules cover the three loan structures when the second comes from an eligible provider such as a government agency, HFA, nonprofit or employer. They allow a combined loan-to-value of up to 105%, and the second's rate can't be more than 2 percentage points above your first mortgage rate. If payments are deferred for at least five years, the lender can leave the second loan out of your DTI. With a shorter deferral, the payment that starts later is counted.
State and Local Housing Finance Agency (HFA) Programs - Best for Localized Grants
Before looking at national banks, check your local Housing Finance Agency (HFA). State and city governments want you to settle down in their area, so they frequently distribute localized grants that are incredibly generous and easier to win than federal money.
Requirements include:
- Assistance Amount: Varies wildly by city. Some offer a flat $10,000, while others provide 3% to 5% of your purchase price.
- Repayment Terms: Many are true grants that never need repayment. Others are "silent seconds" that are forgiven after staying in the house for 5 to 10 years.
- Eligibility: Typically restricted to true first-time buyers within specific county limits. You usually have to complete a local homebuyer education class to qualify.
National Homebuyers Fund (NHF) - Best for Flexible Down Payment Assistance
The National Homebuyers Fund is a fantastic nationwide option that bridges the gap when local city grants run dry. It operates across most states and pairs seamlessly with standard FHA, VA, USDA, or conventional mortgages. A big plus of this fund is that its income caps are surprisingly forgiving.
Requirements include:
- Assistance Amount: You can receive up to 5% of your total mortgage loan amount to use toward your down payment or closing costs.
- Repayment Terms: The assistance comes as either a direct grant or a three-year forgivable loan (meaning if you stay three years, it is wiped out completely).
- Eligibility: You do not have to be a strict first-time buyer, but you must meet NHF's income limits and credit requirements, which typically require a minimum FICO score of 640 and a debt‑to‑income ratio around or below 45%.
Chenoa Fund - Best for FHA Borrowers Needing DPA
If you are leaning toward an FHA loan but cannot scrape together that 3.5% minimum cash requirement, the Chenoa Fund is your answer. Administered by a federally chartered government agency, this program specializes in secondary financing specifically for FHA borrowers who need a push.
Requirements include:
- Assistance Amount: Typically provides 3.5% or 5% of the purchase price, perfectly covering your FHA minimum requirement.
- Repayment Terms: Depending on your income, the assistance is either a fully forgivable loan after 36 months of on-time mortgage payments, or a repayable secondary loan with a 10-year term.
- Eligibility: You need a minimum credit score of 600, using the middle of three FICO scores (or the lower of two if only two scores are available). Your debt‑to‑income (DTI) ratio is also heavily scrutinized, usually capped around 45% to 50%.
Bank of America Down Payment Grants - Best for BoA Customers in Eligible Areas
Large private banks have stepped up their community investments, and Bank of America currently runs one of the most aggressive grant programs. If you are buying in their targeted geographic markets, this is literally free money that instantly boosts your purchasing power.
Requirements include:
- Assistance Amount: The Down Payment Grant offers up to $10,000 or 3% of the home's purchase price (whichever is less). They also have an America's Home Grant offering up to $7,500 for closing costs.
- Repayment Terms: This is a true grant. It does not need to be repaid, though it might be considered taxable income.
- Eligibility: You must be a first‑time homebuyer (no homeownership of a principal residence within the past three years), finance your primary mortgage directly through Bank of America, meet local income caps, and buy in specific eligible census tracts.
Chase Homebuyer Grant - Best for Chase Customers in Select Markets
Similar to BoA, Chase Bank offers its own localized incentive program. Buyers can use this specific grant to aggressively buy down their interest rate, which lowers their monthly payment. It is a highly practical option if you already bank with Chase.
Requirements include:
- Assistance Amount: Provides up to 3% of the home's purchase price or a fixed maximum amount (often between $2,500 and $5,000), whichever is lower, depending on the property's location and the specific Chase program.
- Repayment Terms: This is a grant that does not need to be repaid, but it may be considered taxable income by the IRS. You should consult a tax professional to understand how it affects your tax return.
- Eligibility: You must meet Chase's specific debt-to-income and credit guidelines. You also have to use a qualifying Chase mortgage product (like their DreaMaker loan, or a standard FHA/VA loan) and purchase a primary residence in an approved census tract. Homebuyer education may also be required.
How to Apply for Down Payment Assistance
Assistance is usually requested through a participating mortgage lender rather than on your own. The usual order:
- List the programs for your address. Start with your state HFA, then your city and county housing offices. Fannie Mae's Calculators & Tools page also links to a national DPA program search.
- Choose a lender the program has approved. Many HFAs only fund loans made through participating lenders. CalHFA, for example, makes all of its loans through loan officers it has approved and trained. Ask each lender which programs it can offer before you apply.
- Finish homebuyer education early. Most programs want a completion certificate before closing. Fannie Mae's HomeView course is free online and meets the education requirement for most mortgages.
- Get your income documents ready. The program checks your household income against its own limit, using the same pay stubs, W-2s, tax returns and bank statements your lender collects.
- Allow extra time. The lender submits the assistance request alongside your mortgage, and the funds go toward your down payment and closing costs at closing. A second approval can add time, so build a cushion into your contract's closing date.
Tips for Choosing the Best First-Time Homebuyer Loan
Choosing the right financial product is intimidating, but organizing your approach makes it manageable. Buyers who prepare early always get the best deals. Keep these actionable tips in mind before signing anything:
- Calculate overall affordability: Don't just obsess over the down payment. Look at your total monthly budget, factoring in hidden costs like property taxes, homeowner's insurance, and emergency maintenance.
- Check and improve your credit score: Pull your credit report at least six months prior. Dispute any errors and pay down high credit card balances to boost your FICO score.
- Shop around and compare lenders: Never accept the very first offer. Compare Loan Estimates from at least three different institutions to find the lowest APR and closing costs.
- Consult loan officers or housing counselors: Reach out to a HUD-approved housing counselor for free, unbiased advice on local assistance programs.
FAQs About Best First-Time Home Buyer Programs
Q1. What qualifies you as a first-time home buyer?
Surprisingly, you don't have to be a literal first-timer. Under most federal and state guidelines, you qualify as long as you haven't owned a principal residence within the past three years. If you previously owned but sold it three years ago, you are eligible again. Fannie Mae's definition also counts a displaced homemaker or single parent as a first-time buyer if their only ownership in the past three years was a home owned jointly with a spouse.
Q2. Can I buy a house with zero down payment?
Yes, absolutely. Both VA loans (for eligible military personnel) and USDA loans (for buyers in qualifying rural or suburban areas) allow you to finance 100% of the purchase price. Some local credit unions also offer zero-down conventional products, though they are much rarer.
Q3. Do first-time home buyers get better interest rates?
Not exactly directly, but practically yes. Government-backed programs like FHA or HomeReady let you access highly competitive interest rates even if your credit profile isn't perfect. Conventional loans would charge you a massive premium for the same lower credit score.
Q4. Are down payment assistance grants taxable?
Sometimes, yes. While you never have to pay the actual grant money back to the lender, the IRS might consider certain down payment grants as gross income. We highly recommend consulting a certified tax professional to understand exactly how a grant impacts your tax return.
Q5. Can I apply for multiple first-time home buyer programs?
Yes, this is called "stacking." You can easily combine a primary government loan (like an FHA mortgage) with a local HFA grant and a seller concession. Layering these resources is the smartest way to completely wipe out your out-of-pocket closing expenses.
Q6. Is there a 3% down conventional loan without an income limit?
Yes. Outside HomeReady and Home Possible, both Fannie Mae (standard 97% LTV purchase) and Freddie Mac (HomeOne) allow 3% down with no income cap, as long as at least one borrower is a first-time homebuyer. The loan must be a fixed-rate mortgage on a one-unit primary residence, and if every borrower is a first-time buyer, at least one must complete homeownership education before closing.
Q7. What is the minimum down payment on a $300,000 house?
It depends on the loan program and, for FHA, your credit score:
| Loan Program | Minimum Down Payment | On a $300,000 Home |
|---|---|---|
| VA or USDA | 0% | $0 |
| Conventional 97% LTV, HomeReady or Home Possible | 3% | $9,000 |
| FHA, credit score 580 or higher | 3.5% | $10,500 |
| FHA, credit score 500 to 579 | 10% | $30,000 |
Closing costs come on top of these amounts, which is where DPA and seller concessions help most.
Final Word
Buying your first property is a monumental financial milestone, but it doesn't have to drain your entire life savings. As we've explored, the right programs can bridge the gap between renting and owning, even if you lack a 20% down payment or perfect credit. Just remember, there is no single "best" program out there—only the one that perfectly aligns with your personal financial reality.
Now is the time to take action. Start by checking your current credit score, organizing your income documents, and reaching out to a local mortgage broker for a pre-approval. Don't leave free money on the table. Go claim the assistance you deserve and unlock the door to your new home!