

A loan officer helps people apply for loans and evaluates their finances to decide, or recommend, whether they qualify. A mortgage loan officer, also called a mortgage loan originator (MLO), finds borrowers, explains loan options, collects and checks income, asset and credit documents, takes the loan application and stays with the file through underwriting to closing. Loan officers earned a median $76,690 a year in May 2025, and mortgage loan officers must be licensed by their state through NMLS (20 hours of education, the SAFE MLO Test with a 75% passing score, and background and credit checks) or, at banks and credit unions, registered with NMLS.
Have you ever looked at a house, wondering how people afford it, or sat across from someone at a bank and thought, "What do you actually do all day?" I get that question a lot. When I tell people I'm a loan officer, they often picture someone stamping "APPROVED" or "DENIED" on a stack of paper like a cartoon banker.
The reality is a lot more hands-on. Being a loan officer isn't just about math. It's part detective work, part hand-holding, part project management. Whether you're weighing this as a career move in 2026 or you're just curious what the job actually involves, here's the honest version, the good parts, the hard parts, and the paycheck.
Key Takeaways
- The median loan officer salary was $76,690 in May 2025, but commission-based earners routinely clear six figures once they build a pipeline.
- The SAFE MLO exam has a 75% passing score, and only about 53% of candidates pass on their first attempt.
- The job runs on five recurring tasks: prospecting, consultations, financial qualification, application processing, and closing.
- Employment is projected to grow just 1% from 2025 to 2035, yet about 17,100 openings open up every year, mostly from retirements and people leaving the field.
- AI is reshaping the busywork side of the role, not eliminating the license itself, since federal law (the SAFE Act) requires anyone who takes mortgage applications and negotiates loan terms for pay to be a licensed or registered loan originator.
What is a Loan Officer?
Put simply, I'm the bridge between a borrower's dream and the bank's money. A loan officer, sometimes called a mortgage loan originator (MLO) in the housing world, helps people apply for loans and evaluates their finances to figure out what they qualify for.
You'll find loan officers in commercial banking and consumer lending too (think auto loans), but most of the activity, and most of the earning potential, sits in mortgage lending. We work inside commercial banks, credit unions, and independent mortgage companies, and the day-to-day looks a little different depending on which of those you land in.
Let's talk about the average salary of a loan officer, since that's probably why you clicked. According to the Bureau of Labor Statistics, the median annual wage for loan officers was $76,690 as of May 2025. That figure is useful as a baseline, but it doesn't tell the full story.
Here's why: this is a sales role at its core. Producers who work primarily on commission can clear $100,000 to $200,000 or more in a strong year, while someone treating it like a passive nine-to-five will likely fall well short of the median. If you're a people person who also doesn't mind spreadsheets, and you can handle pressure without losing your cool, this line of work rewards that combination.
Also Read:
- Mortgage Underwriter vs Loan Officer: Which Career Is Best?
- 11 Best Loan Officer Schools for Newbies: Online & Local
Loan Officer Job: Key Numbers and Sources
These are the official pay, job and licensing numbers for loan officers, from the Bureau of Labor Statistics and NMLS, the system every mortgage loan originator is licensed or registered through.
| Item | Number | Source |
|---|---|---|
| Median annual wage | $76,690 ($36.87 an hour), May 2025 | BLS Occupational Outlook Handbook |
| Pay range | Lowest 10% under $39,430; highest 10% over $153,180 | BLS Occupational Outlook Handbook |
| Number of jobs | 283,000 (2025) | BLS Occupational Outlook Handbook |
| Job outlook | +1% from 2025 to 2035, about 17,100 openings a year | BLS Occupational Outlook Handbook |
| Typical entry-level education | Bachelor's degree | BLS Occupational Outlook Handbook |
| Pre-licensing education (mortgage loan originators) | 20 hours of NMLS-approved courses | NMLS Education FAQ |
| SAFE MLO Test | 120 questions (115 scored), 190 minutes, 75% to pass, $110 | NMLS MLO Testing Handbook |
| SAFE MLO Test first-time pass rate | 53% (as of December 31, 2024) | NMLS Test Performance Information |
| Continuing education | 8 hours every year to renew the license | NMLS Education FAQ |
What Does a Loan Officer Do in Real Estate?
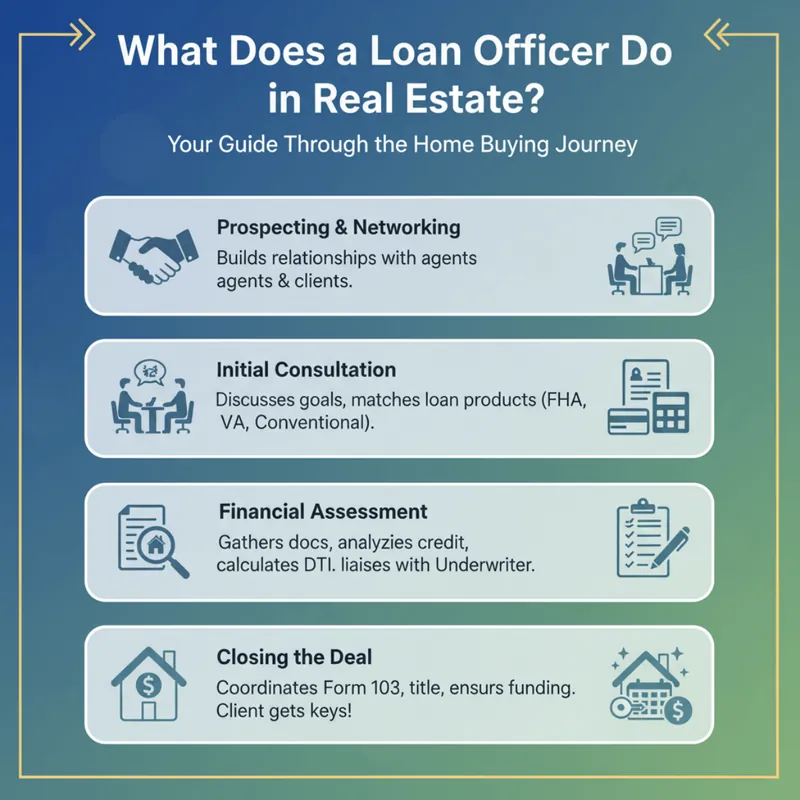
This is the core of the job. If you join this industry, here's what your week will genuinely look like. It comes down to five duties of loan officers that repeat on a loop.
Prospecting and Building a Pipeline
I don't sit at a desk waiting for the phone to ring. A big chunk of my week goes into relationships, meeting real estate agents, builders, and past clients to keep referrals flowing. No new business means no paycheck, so in 2026 that also means staying visible on social media and keeping a consistent digital presence.
The Initial Consultation
This is where the listening skills come in. I sit down with clients, or hop on a video call, to understand their goals. Are they chasing a lower monthly payment? Buying their first home? I need to match them with the right product, whether that's a conventional loan, an FHA loan for someone with a thinner credit file, or a VA loan for a veteran.
Financial Assessment and Qualification
Now I put on the detective hat. I collect the paperwork, W-2s, tax returns, bank statements, run their credit, and calculate their debt-to-income (DTI) ratio. Get this step wrong and the whole file can unravel weeks later, right when everyone least wants surprises. My job is to pre-qualify them accurately so they can shop for a home with real confidence.
The Application and Processing
Once a buyer finds a house, we complete the Uniform Residential Loan Application (Form 1003). I gather every required document and hand the file to a processor, but my involvement doesn't stop there. I field questions from the underwriter, the person making the final call, and if they need a letter explaining a large bank deposit, I'm the one chasing that down from the client, fast.
Closing the Deal
This is the payoff. I coordinate with the title company to make sure funds wire on schedule. When the client finally gets their keys, and I get that "thank you" text along with the commission check, every stressful moment feels worth it.
Pros and Cons of Being a Loan Officer
Like any relationship, my relationship with this career has its ups and downs. Here is an honest look:
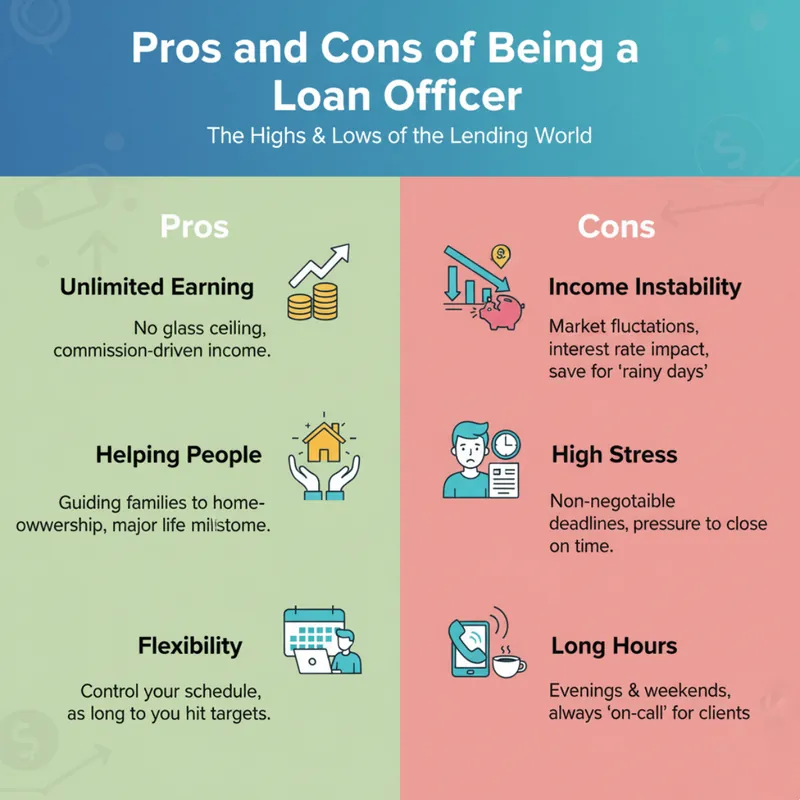
Pros:
- Unlimited Earning Potential: There is no glass ceiling. If you close more loans, you make more money. It's that simple.
- Helping People: There is a genuine emotional reward in helping a family buy their first home. You are part of a major life milestone.
- Flexibility: I control my schedule. If I need to go to the dentist or pick up my kids, I can, as long as I am hitting my numbers.
Cons:
- Income Instability: If interest rates spike, like they did a few years ago, or the market slows down, your income drops. You have to be good at saving money for rainy days.
- High Stress: Deadlines are non-negotiable. If a loan doesn't close on Friday, a family might have nowhere to sleep. That pressure falls on you.
- Long Hours: Real estate happens on weekends and evenings. You will likely be answering calls at 8 PM on a Tuesday or during Sunday brunch.
How to Become a Loan Officer?
If you are still reading and thinking, "I can do this," here is your roadmap. Unlike becoming a doctor or lawyer, you don't need years of grad school, but you do need a MLO license.
- Meet Basic Requirements: You generally need to be 18 years old and have a high school diploma.
- Pre-Licensing Education: You must complete 20 hours of NMLS (Nationwide Multistate Licensing System) approved education. This covers federal law, ethics, and lending standards.
- Pass the SAFE MLO Exam: This is the big hurdle. It's a tough test with a national pass rate that often hovers around 50-60%. You need a score of 75% to pass.
- Find a Sponsor: You cannot hold an active license on your own. You must be hired or sponsored by a lender or mortgage broker to activate your license.
For a deeper dive into these steps, I recommend checking out this guide on how to become a loan officer.
What Skills Does a Loan Officer Need?
The license gets you in the door, but skills keep you in the room.
- Communication: You must be able to explain complex financial terms like "amortization" or "escrow" in plain English.
- Sales & Persuasion: You are selling yourself as much as the money. Why should they trust you over an online algorithm?
- Attention to Detail: One wrong digit on a social security number can delay a closing by days.
- Tech Savviness: This is non-negotiable now. In 2026, the old-school LOs are retiring. The new generation uses technology to speed up the boring stuff.
Efficiency is the name of the game. I use a CRM (Customer Relationship Management) system to track every lead so no one falls through the cracks. If you want to know what tools the pros are using to automate follow-ups and stay organized, take a look at the best CRM for loan officers. Using the right software is often the difference between closing 5 loans a month and closing 15.
Loan Officer Outlook in 2026
So, is it too late to get in? Not at all, but the landscape has shifted.
According to the BLS, employment for loan officers is projected to grow just 1% from 2025 to 2035. That sounds sluggish, but it still adds up to about 17,100 job openings every year, mostly because older officers are retiring or moving out of the field.
Mortgage rates stayed between about 6% and 6.7% from January through August 2026, then climbed past 7% in late September; Freddie Mac's 30-year average was 7.32% on October 22, 2026. In September, NAR counted 4.6% more homes for sale than a year earlier, but existing-home sales were running 2.2% below last year. It's less of a dramatic rebound and more of a slow, bumpy normalization. Lenders are also getting pickier about who they hire. They want loan officers who are self-sufficient and comfortable with technology. The "order taker" era is over. What's replacing it is the "expert advisor" model, where the loan officer who pairs automation with real relationship skills consistently outperforms the ones still doing everything by hand.
Bank Loan Officer vs. Independent Mortgage Broker
One thing a lot of newcomers miss is that "loan officer" isn't one single job description. Where you work changes how you're paid, what products you can offer, and how much independence you have.
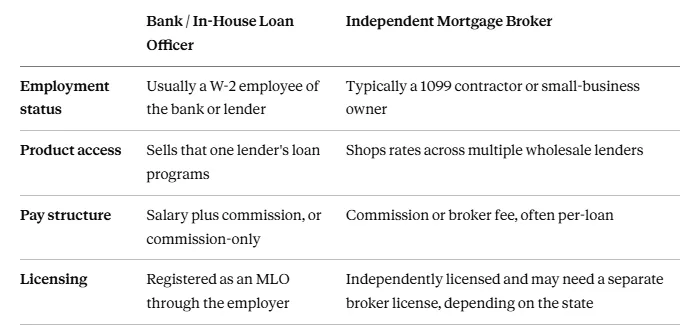
Neither path is objectively better. Working inside a bank gives you a built-in referral base and brand recognition, while going independent gives you more control over pricing and which lenders you place a loan with, at the cost of building your own book of business from scratch. There's also a separate track entirely for commercial loan officers, who work with business borrowers on things like equipment financing or commercial real estate rather than residential mortgages, and the day-to-day looks quite different from what's described above.
Will AI Replace Loan Officers in 2026?
This question comes up constantly, and the honest answer is: partly, but not the way people assume. AI is already handling a lot of the repetitive work, clearing routine conditions, drafting first responses, chasing documents, flagging missing paperwork, faster than any human could.
What AI can't do, at least not legally, is replace the license itself. Under the SAFE Act, any individual who takes a residential mortgage loan application and offers or negotiates its terms for pay has to be a state-licensed or federally registered loan originator. And under the Equal Credit Opportunity Act and Regulation B, a lender still has to give a declined applicant the specific principal reasons for the denial; "you didn't meet our internal standards" or a failing score on a scoring system isn't enough. Those rules keep a licensed, accountable person at the center of every mortgage, no matter how much of the paperwork gets automated around them.
In practice, this means the loan officers who struggle aren't losing deals to a chatbot directly. They're losing deals to other loan officers who respond faster, follow up more consistently, and use AI tools to reclaim hours they used to spend on data entry. That's exactly the gap platforms like Zeitro are built to close, handling the repetitive backend work so you can spend your time where it actually counts: with the client. Zeitro is an AI mortgage workstation, with lead capture, a digital point of sale, your pipeline and loan files, a pricing engine and Zeitro Strata guideline AI in one platform; when the file is ready, it goes to your LOS as FNM 3.4 or straight into Encompass.
Frequently Asked Questions
Q1. .Is a Loan Officer a Sales Job?
Yes, at its core. You're evaluating finances and processing paperwork, but your income depends almost entirely on how many loans you close, which makes prospecting and client relationships just as important as the underwriting math.
Q2. Do Loan Officers Work Weekends?
Regularly, yes. Real estate transactions don't stop at 5 PM on Friday, so open houses, buyer questions, and time-sensitive underwriting conditions often land on evenings and weekends.
Q3. How Do Loan Officers Get Paid?
Most earn a commission, commonly a small percentage of the loan amount, sometimes on top of a modest base salary. Lenders themselves make money through origination fees and the spread between what they charge borrowers and what it costs them to fund the loan, and a portion of that gets passed to the loan officer as commission.
Q4. What's the Difference Between a Loan Officer and a Mortgage Broker?
A loan officer typically works for one bank or lender and sells that company's products. A mortgage broker is independent and can shop a borrower's loan across multiple wholesale lenders to find better pricing, usually in exchange for a broker fee or commission.
Q5. What Career Paths Can a Loan Officer Advance To?
Many start as a junior loan officer or loan officer assistant handling support work, then move into a full producing role. From there, experienced originators can grow into senior loan officer or executive loan officer positions, take on team leadership, or branch out into commercial lending entirely.
Conclusion
Being a loan officer is one of the few careers where you can earn a CEO-level income without a CEO-level degree, if you're willing to put in the work. It takes hustle, thick skin, and a genuine interest in helping people through one of the biggest financial decisions of their lives.
If you're just starting out, my honest advice is to embrace the technology early instead of drowning in paperwork. Tools like Zeitro can automate the repetitive heavy lifting, so your clients stay happy and your pipeline stays full. See how it works for loan officers and brokers. In this business, your efficiency is your income. Good luck out there.