Written by
Eric
Share this article


Subscribe to updates
Last Checked and Updated on September, 2026
When I first started originating loans, my daily routine felt like a never-ending cycle of chasing down borrower documents, manually checking guidelines, and worrying about deals slipping through the cracks. If you're a loan professional handling a growing book of business, you know exactly what I mean.
Without the right system, the origination process quickly turns exhausting. After helping a handful of small brokerages move off spreadsheets and onto real pipeline software over the past couple of years, I've seen firsthand how much time a good stack gives back to a team. In this guide, we break down the best mortgage pipeline management software for 2026, built to automate your workflow, cut hours of manual data entry, and help you close more loans. Let's dive in.
Key Takeaways
- AI is the new standard: Modern tools use AI to slash guideline lookup and pre-qual times, not just organize your contacts.
- Choose based on scale: Individual LOs need flexible, low-commitment tools, while enterprise banks lean on heavy-duty legacy systems built for volume.
- You don't have to replace your LOS: Most modern POS and CRM platforms sit on top of your existing loan origination system through an API, giving you real-time pipeline visibility without a full system migration.
- Automation equals revenue: Seamless point-of-sale (POS) and CRM platforms noticeably lift borrower application completion rates.
Benefits of Using Mortgage Pipeline Management Software
Upgrading your tech stack isn't about having a flashy dashboard. It changes how you manage your entire day. Here's what you actually gain:
- Faster Pre-Qualifications: Automated income and DTI calculations mean you can hand a borrower an accurate quote in minutes instead of days.
- Higher Close Rates: Integrated CRMs keep leads from going cold by triggering follow-ups the moment a borrower shows intent.
- Fewer Manual Errors: Letting software auto-fill the 1003 form and sync it with your backend cuts down on the small mistakes that turn into costly compliance headaches.
- Better Borrower Experience: Modern portals let clients upload sensitive documents securely from their phone, keeping them engaged instead of frustrated.
- Real-Time Pipeline Visibility: A live view of every loan's stage, open conditions, and document gaps means files stop stalling quietly in someone's inbox.
6 Top-Rated Loan Pipeline Management Software
To find the right fit, we compared these platforms on feature depth, integration reach, and real-world value for U.S. lenders. Here are our top six picks for modernizing your mortgage pipeline management.
#1 Zeitro - Best for SMBs and Individuals
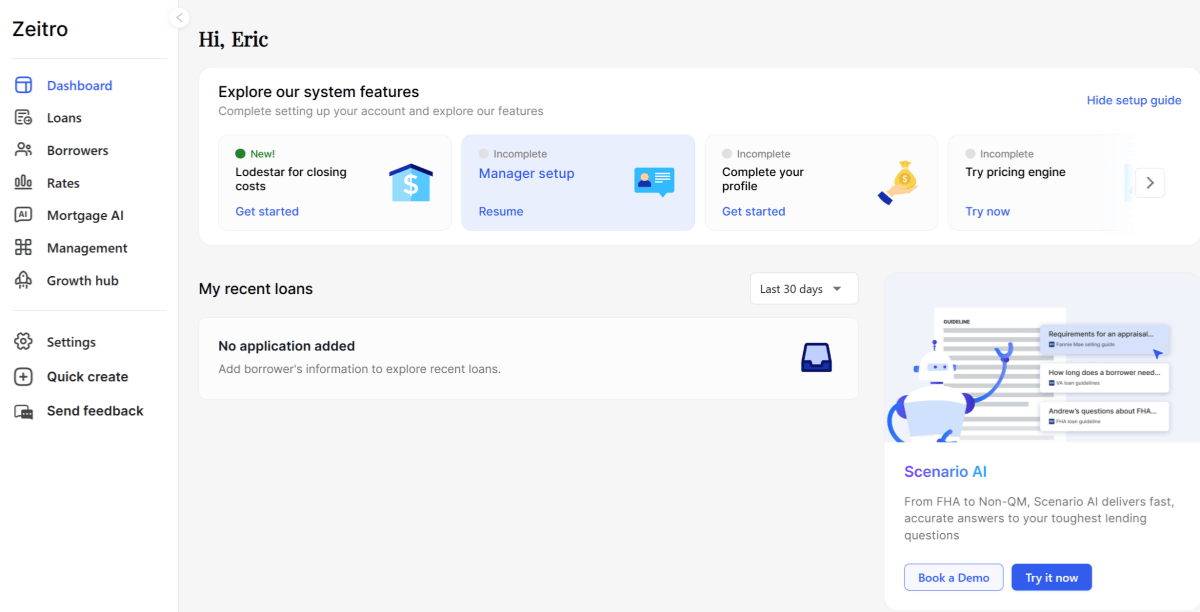
Zeitro is a specialized AI mortgage agent built for U.S.-based loan officers, brokers, and wholesale lenders. Serving over 10,000 users, it acts as a dedicated digital assistant that takes on the heavy lifting of the origination process.
Instead of digging through lender manuals, Zeitro's Strata AI checks Conventional and Non-QM guidelines in seconds, drawing from over 1,000 guidelines across 100+ investors so answers stay current as programs change. It helps underwriters save more than 18 hours a month, while loan officers get back 20+ hours. With pre-qualifications delivered 2.5x faster, users often see a 30% jump in closed loans. The Explorer tier is free with 3 guideline queries a day, and the paid Individual plan starts at roughly $8 a month for unlimited access.
- Zeitro Strata AI: A guideline assistant that answers Conventional and Non-QM questions instantly, citing its sources so you can double-check the answer yourself.
- Digital 1003 (POS): Automates the borrower application, calculates DTI with AI, and exports the data in MISMO 3.4 (ULAD) format, the industry-standard structure lenders now expect for URLA data.
- Pricing Engine: Delivers competitive rate quotes for both traditional and harder-to-place Non-QM products in real time.
- GrowthHub: A branded personal microsite that captures organic search traffic and helps you manage incoming leads — a lighter-weight companion to a full CRM rather than a replacement for one.
Why Choose: It's the strongest choice for SMBs and individual LOs who want serious AI automation without a big monthly commitment, especially since the Explorer tier costs nothing to try.
#2 Floify - Best for Point-of-Sale (POS) Automation
Floify has earned its reputation as a powerhouse in the point-of-sale space. Backed by Porch Group, this platform is built to smooth out the entire front end of the pipeline. If your team constantly chases down bank statements and W-2s, this tool takes that job off your plate.
We appreciate how it bridges the gap between borrower and loan team. A secure, intuitive web portal cuts down application abandonment because borrowers can see exactly what's still needed and upload it right from their phone.
- Dynamic Apps: Tailors the 1003 questions to the loan type, whether it's a HELOC or Non-QM, stripping out irrelevant fields to speed up completion.
- Automated Workflows: Sends automatic email and SMS nudges when a document is missing.
- Floify Verify: A native income and employment verification tool powered by Argyle that can cut verification costs by 60-80% compared with legacy providers, without adding a separate vendor to manage.
- Seamless Integrations: Connects with major loan origination systems (LOS) to push data across securely.
Why Choose: Floify fits teams that want to aggressively tighten up front-end document collection and improve the borrower experience without overhauling their LOS.
#3 Aidium - Best for Mortgage CRM and Lead Conversion
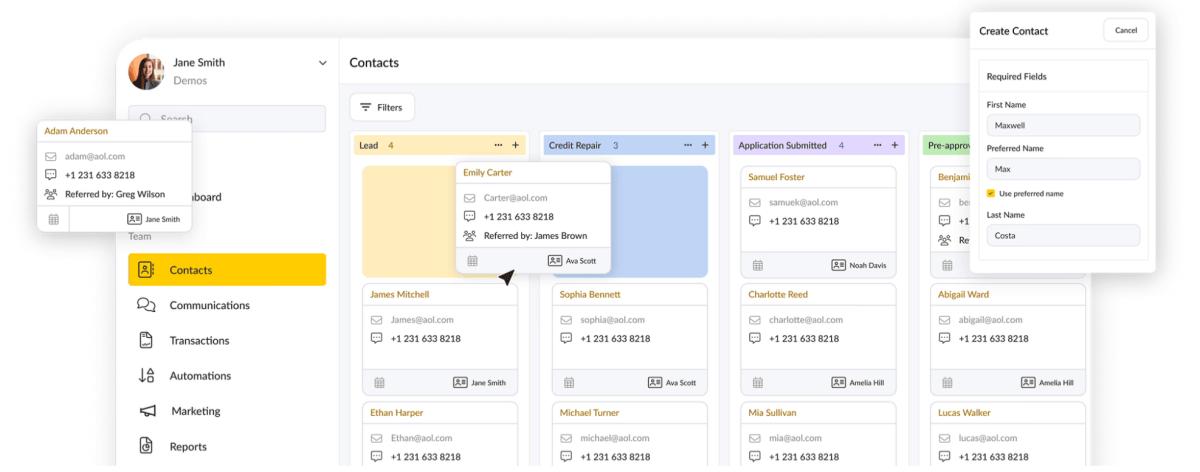
Aidium is a CRM platform built specifically for the mortgage industry. Keeping a pipeline full takes constant lead nurturing, and that's exactly where this software earns its keep.
Instead of guessing who to call next, Aidium organizes your contacts and surfaces your highest-value prospects. It works as an engagement hub that unifies marketing and compliance workflows, so you can spend more time building relationships with borrowers and referral partners.
- Smart Lead Routing: Captures new leads and routes them to the right loan officer based on rules you set.
- Automated Campaigns: Pre-built email, SMS, and ringless voicemail drip sequences tailored to each loan stage.
- Aidium Intelligence: Uses AI to flag when a past client is likely ready to refinance or buy again.
- Partner Tracking: Monitors referral networks so you always know which Realtors are actually sending business your way.
Why Choose: Aidium is the go-to pick for brokerages and mid-sized lenders that live and die by marketing automation and lead conversion.
#4 Blend - Best for Enterprise Cloud Banking and Seamless Application
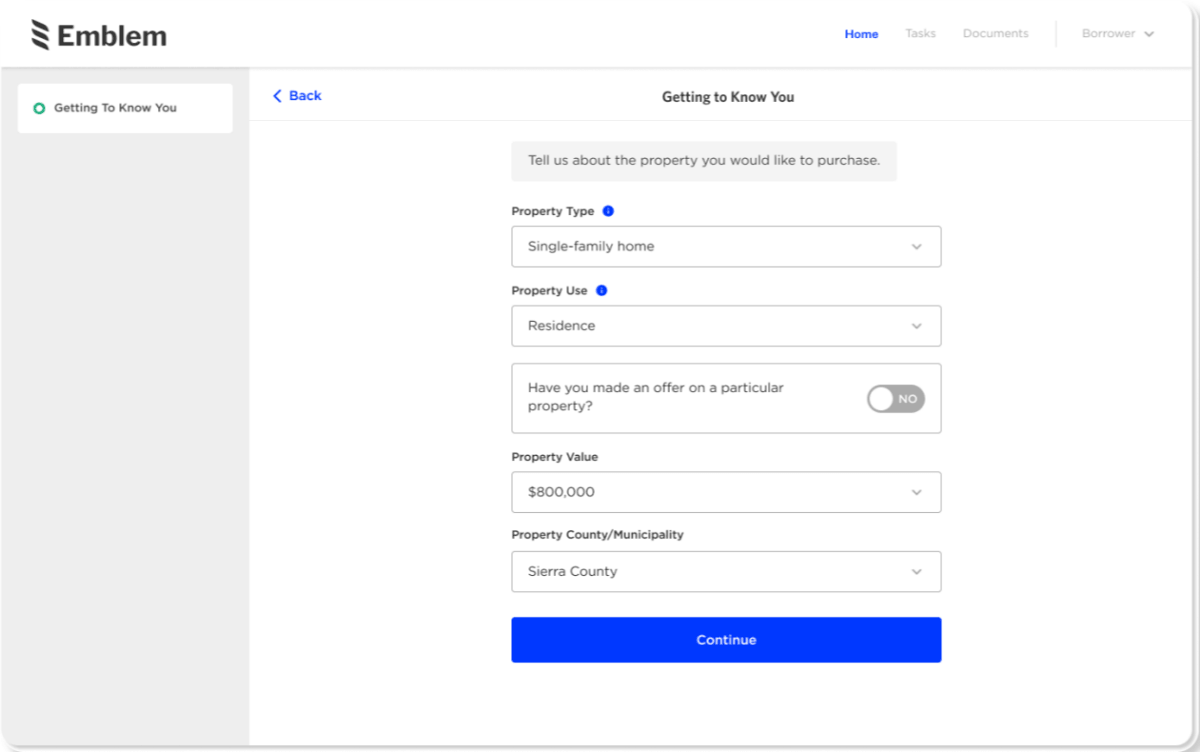
Looking at the enterprise sector, Blend is undeniably part of the infrastructure powering modern banking. Used by 18 of the top 50 U.S. mortgage originators, this cloud-based platform handles massive volume, connecting every step from application to closing.
What sets Blend apart is a frictionless, omnichannel borrower experience. Financial institutions can offer a fully digital journey whether a client is applying for a mortgage, a home equity line, or a new deposit account.
- Omnichannel Application: Borrowers can start on their phone, pause, and finish on a desktop or with a loan officer, without losing progress.
- Instant Data Verification: Connects directly to payroll and banking institutions to verify assets and income on the spot.
- Blend Autopilot: Launched commercially in mid-2026 after a four-month preview across more than 25,500 loans, this agentic AI tool automates document review and pre-underwriting checks, helping lenders shave off up to a few hours per loan and several days off the cycle time.
- Enterprise Scalability: Built to handle the regulatory and volume demands of large credit unions and national banks.
Why Choose: Blend suits well-funded, enterprise-level banks that need a sophisticated, multi-product digital banking environment.
#5 nCino Mortgage Suite - Best for Mobile-First Origination
Formerly known in the industry as SimpleNexus, the nCino Mortgage Suite brings the loan origination process straight to a smartphone. For loan officers who are constantly out meeting Realtors or working open houses, being tied to a desktop is a real disadvantage. The platform now touches roughly a quarter of all U.S. residential loan originations, a scale that reflects how many lenders have leaned into mobile-first origination.
nCino solves the mobility problem with a genuinely capable mobile app that unites loan officers, borrowers, and real estate agents in one collaborative space. This doesn't just speed up cycle time — it noticeably improves transparency for everyone involved.
- Co-Branded App: Lets LOs and Realtors share a branded mobile app so everyone stays current on loan status.
- Mobile Pre-Approvals: Originators can run credit and issue pre-approval letters straight from their phone, even on a weekend.
- Integrated eClose: Supports hybrid and fully digital closings so borrowers can review and sign disclosures from anywhere — a feature that's become table stakes for platforms competing in the digital closing space.
- Incentive Compensation: Built-in tracking for LO commissions, replacing messy payroll spreadsheets.
Why Choose: It's a strong match for mobile-heavy originators and teams that lean heavily on real estate agent partnerships.

#6 Encompass - Best for Comprehensive End-to-End LOS
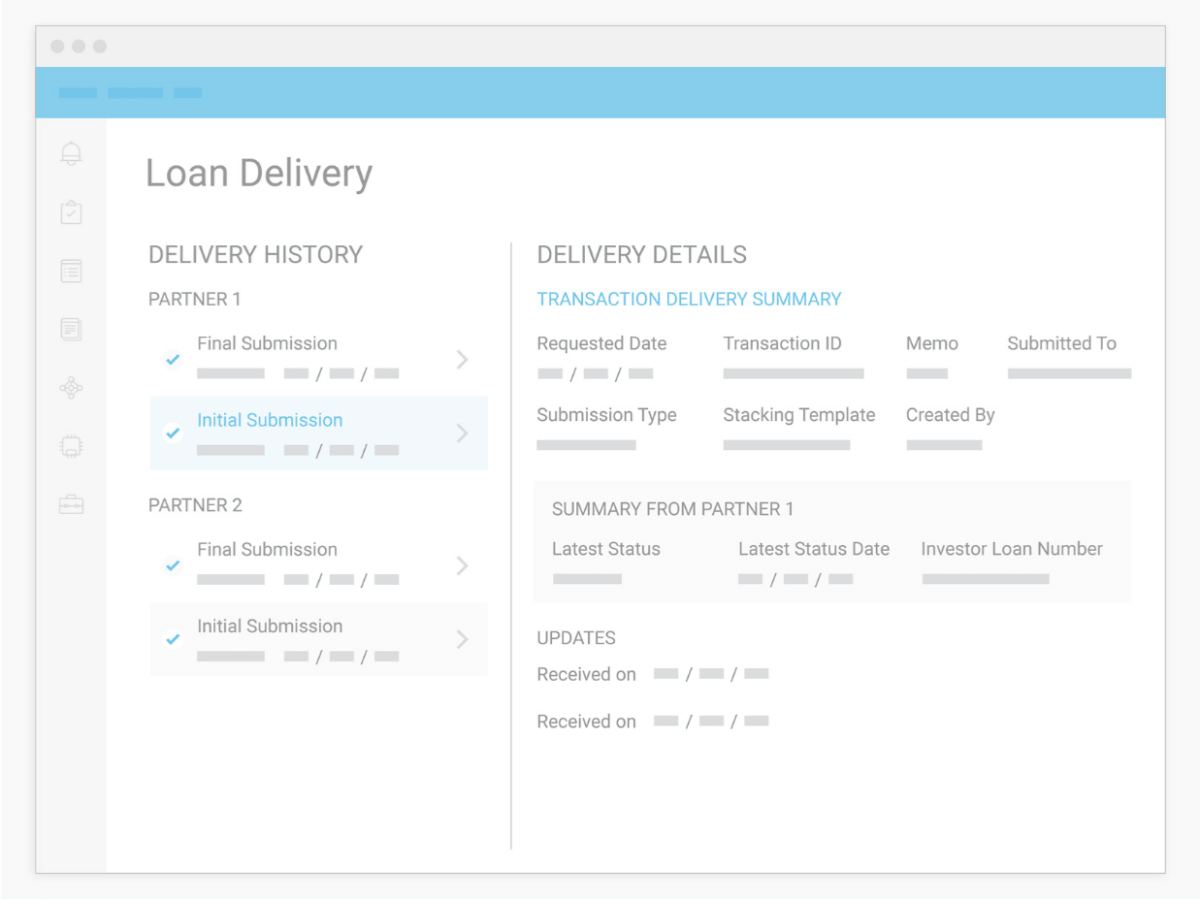
It's impossible to talk about mortgage pipelines without mentioning Encompass by ICE Mortgage Technology. Holding roughly 50% of the U.S. loan origination system market, Encompass is the dominant player in this category and functions as the central brain for most large lending operations.
While it has a reputation for being complex to configure, its depth is hard to match. From application intake through underwriting, closing, and secondary market delivery, Encompass keeps everything organized and compliant under one roof.
- End-to-End Coverage: Manages processing, underwriting, and post-close delivery natively without jumping between systems.
- Robust Compliance Engine: Automatically handles TRID timing, HMDA data collection, and state-specific licensing and disclosure requirements, which matters a lot for larger lenders juggling multi-state compliance and audit reporting.
- Massive Integration Ecosystem: Connects with nearly every major POS, CRM, and pricing engine on the market.
- Customizable Business Rules: Lets administrators build highly specific internal workflows tailored to a lender's exact process.
Why Choose: Encompass is the go-to for mid-to-large independent mortgage banks (IMBs) that need a heavy-duty, fully compliant backbone.
How to Choose Your Mortgage Pipeline Software?
Picking the right tool feels overwhelming until you focus on your actual bottlenecks. Before signing a long-term contract, walk through these core pillars:
- AI Capabilities: AI-driven features aren't optional anymore. Look for tools that automate DTI calculations or answer complex guideline questions instantly, the way Zeitro does.
- Integrations Without a Full Migration: Your POS, CRM, and LOS need to sync to avoid double data entry. The good news is you rarely have to rip out your existing LOS to get better pipeline visibility — most modern POS and CRM tools, including Zeitro, Floify, and Aidium, connect to Encompass and other major systems through an API rather than replacing them.
- Budget & Scalability: Match the price tag to your size and volume. A solo broker can thrive on a flexible freemium model, while a lender scaling from a couple hundred to several hundred loans a month needs a platform that adds visibility without forcing you to add headcount.
- Security & Compliance: Confirm the platform meets financial encryption standards and supports the audit trails, TRID timing, and state licensing tracking your compliance team actually needs.
FAQs About Best Mortgage Pipeline Management Software
Q1. What is mortgage pipeline management software?
It's a digital platform lenders and brokers use to track and manage loans through their entire lifecycle, from the initial borrower application and document collection to underwriting, compliance checks, and final funding.
Q2. How much does loan pipeline software usually cost?
Pricing varies a lot based on scale. Solo originators can start with flexible plans around $8 a month on platforms like Zeitro. Enterprise-grade systems built for large banks, on the other hand, can run into the thousands of dollars monthly once you factor in implementation and support fees.
Q3. Can AI improve my mortgage pipeline management?
Absolutely. AI cuts down on manual "stare and compare" work. It can calculate borrower income instantly, extract data from W-2s, and answer obscure Non-QM guideline questions in seconds, trimming real hours off the approval process.
Q4. What's the difference between a Mortgage POS and an LOS?
A Point-of-Sale (POS) is the front-end interface where borrowers apply and upload documents. The Loan Origination System (LOS) is the backend engine where your team handles underwriting, compliance, and secondary market delivery.
Q5. Is it secure to use cloud-based mortgage software?
Generally, yes. Reputable mortgage platforms follow strict data security standards, including bank-level encryption, SOC 2-type compliance audits, and multi-factor authentication, all of which meaningfully reduce the risk of a breach. No system can promise zero risk, so it's worth confirming a vendor's specific security certifications before you commit sensitive borrower data to it.
Q6. Can I add pipeline visibility software without replacing my existing LOS?
Yes, and for most lenders this is the more realistic path. You don't need to migrate off Encompass or another LOS just to get real-time visibility into loan stages, open conditions, and document gaps. Modern POS and CRM tools, including Zeitro, Floify, and Aidium, connect to your existing LOS through an API and layer pipeline tracking, borrower risk signals, and automated alerts on top, so your ops team gets a centralized view without the disruption of a system-wide switch.
Q7. What's a good alternative to nCino Mortgage Suite?
It depends on what you need nCino for. If you're after the same mobile-first, agent-collaboration experience, Blend is a comparable enterprise-grade option with a stronger digital banking suite behind it. If your priority is a heavier compliance and audit trail, especially across multiple states, Encompass is generally considered the more feature-complete system of record. For smaller teams that mainly want nCino's mobility without the enterprise price tag, pairing a lighter POS like Zeitro or Floify with a dedicated CRM can cover similar ground.
Q8. Does Zeitro include CRM features?
Not exactly. Zeitro is built around AI guideline research, a digital 1003 application, and a pricing engine, with GrowthHub adding a lead-capturing personal microsite on top. It doesn't replace a full CRM's contact management, drip campaigns, or referral tracking. If you need that layer, it pairs well with a dedicated CRM like Aidium alongside Zeitro's guideline and POS tools.
Conclusion
Managing a healthy mortgage pipeline doesn't have to mean working endless nights and weekends. The right software eliminates tedious manual data entry, keeps you compliant, and gives borrowers a noticeably better experience. To recap:
- Zeitro: Best for individuals and SMBs who want powerful, affordable AI handling guidelines and POS tasks.
- Floify: The go-to for secure, front-end borrower document collection.
- Aidium: Top choice for CRM, lead nurturing, and marketing automation.
- Blend: Ideal for large, enterprise-grade digital banking operations.
- nCino: Best for originators who need a genuinely useful mobile app in the field.
- Encompass: The heavy-duty LOS for complete end-to-end management.
If you're not sure where to start, try a risk-free option first. Zeitro offers a free tier that lets you see how much AI can change your daily workflow before you commit to scaling up.
People Also Read
- Best AI Mortgage Underwriting Software for Loan Professionals
- Should Mortgage Lender and Broker Build In-House AI Tools?
- Best CRM for Mortgage Brokers: Choose As Required
- 8 Best Non-QM Mortgage Lenders: Which to Choose?
- Best Mortgage Loan Officer Training: Which to Pick?
- Mortgage Pipeline Hedging 101: Complete Guide & Strategies