Written by
Eric
Share this article


Subscribe to updates
Last Checked and Updated on August, 2026
Spend ten minutes on the r/loanoriginators subreddit and you'll feel the tension immediately. Someone posts, "I've dialed 500 numbers this week and still haven't taken a single application." Another asks, "Is this business even survivable anymore?" If you're a new loan officer, that feast-or-famine anxiety probably sounds familiar. Maybe you're staring at a phone that hasn't rung all day, wondering whether it's worth draining your savings on a batch of leads that might never convert.
I've sat exactly where you're sitting. I remember needing just one closing to cover next month's bills. The good news is that the grind doesn't last forever once you build the right foundation. The loan officers who are thriving in 2026 aren't necessarily working more hours than everyone else — they're combining old-fashioned relationship building with digital tools that didn't exist a few years back. This guide walks through both halves of that equation, so you can survive your first year and start building a pipeline that keeps feeding itself.
Here's the short version before we dig in: mortgage leads come from three main channels — your referral network (agents, past clients, other professionals), digital marketing (your website, social media, video, and email), and paid or purchased leads (PPC ads and lead services). The strongest producers usually blend all three rather than betting everything on one.
People Also Read:
- [Proven] How to Generate Mortgage Leads for Free? 6 Methods
- Best Mortgage Loan Officer Training: Which to Pick?
- 8 Best Non-QM Mortgage Lenders : Which to Choose?
- Are Mortgage Rates Expected to Go Down in 2026? Expert Forecasts
- Best CRM for Mortgage Brokers: Choose As Required
- 8 Best Mortgage Lead Management Software: Efficiency Matters
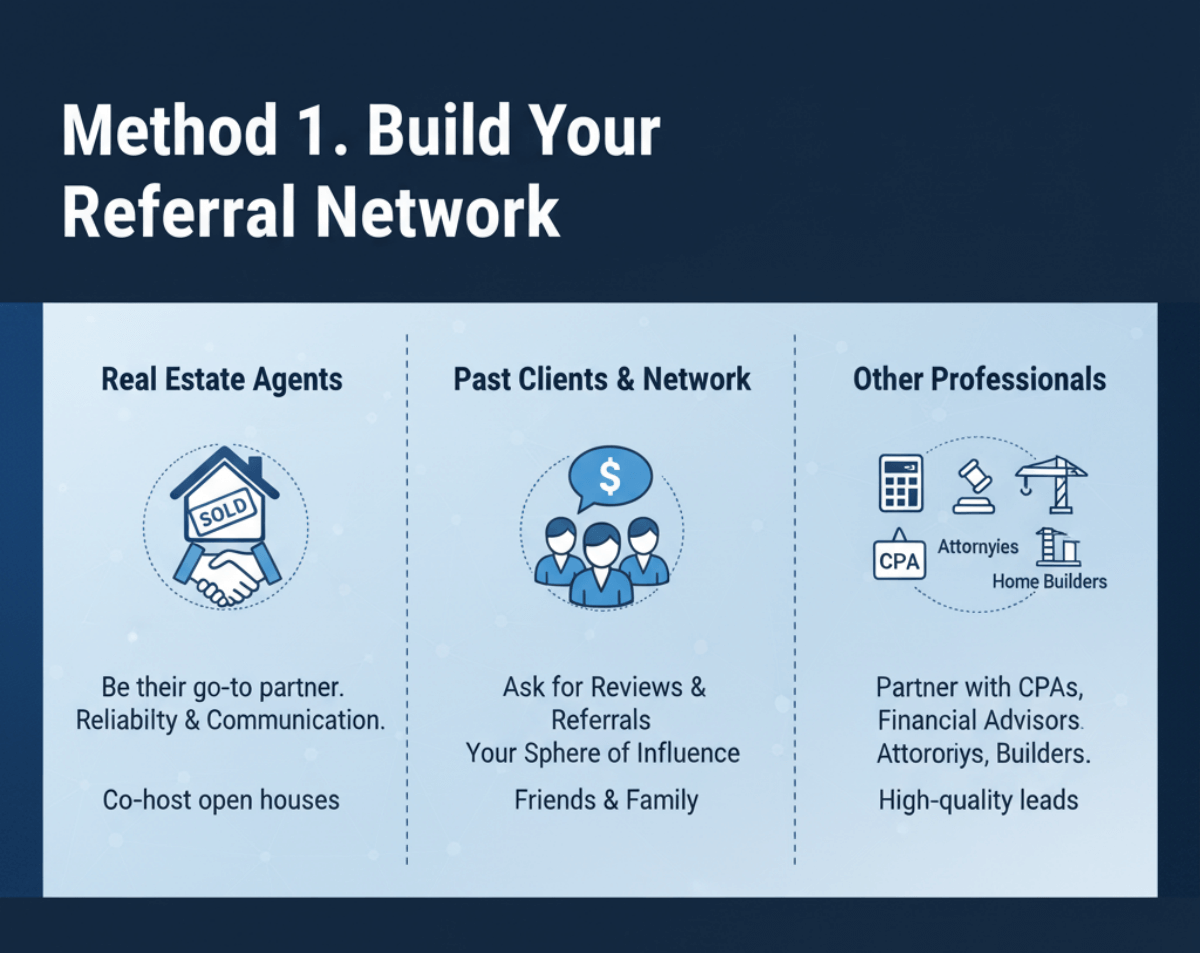
Method 1. Build Your Referral Network
Despite the rise of AI and automation, mortgage lending is still a deeply human business. People don't just want a loan — they want to trust the person handling the biggest debt of their life. Building a referral network is about planting seeds. It takes longer than purchasing mortgage leads, but what grows from it costs nothing but time and effort.
Real Estate Agents
Real estate agents have traditionally been the gatekeepers of purchase business, but here's where most new LOs go wrong: they call an agent and basically ask for a handout — "Got any buyers I could pre-qualify?" That approach gets ignored fast, because every agent already has a lender they trust. Your job is to earn a seat at the table, not ask for one.
Value comes before value is exchanged. Agents worry about exactly one thing: a deal collapsing right before closing. Be the loan officer whose pre-approvals actually hold up. Send a quick update every Tuesday so the agent never has to chase you for a status check. Offer to co-host an open house or split the cost of a marketing flyer. Five to ten agents who trust you completely will bring you more business than a hundred who barely remember your name.
There's also a structural shift worth understanding. Since the National Association of Realtors settlement reshaped how commissions work, buyers now sign a written agreement with their agent before they ever tour a home, and commission gets negotiated directly instead of showing up automatically in the MLS listing. That means agents are having harder conversations with their clients about fees, and they're leaning more on loan officers who can explain financing options clearly to nervous buyers. It's also opened the door with listing agents, who historically had thinner relationships with LOs than buyer's agents did. If you've only ever chased buyer's agents, this is a good time to widen the net.
Past Clients & Network
Your sphere of influence and your past clients are the lowest-hanging fruit in the entire business, and most loan officers still let it rot on the vine. It's easy to close a loan, shake hands, and never call that person again. That's a mistake, because someone you already helped is your most credible salesperson — but only if you actually ask.
I use one script consistently, and I say it during the "you're clear to close" call, right when the client is happiest: "It's been a pleasure helping you get here. My business runs entirely on people like you. If a friend or family member is thinking about buying, would you be comfortable introducing us?" Beyond past clients, don't ignore your everyday circle — your dentist, your kid's soccer coach, the barista who makes your coffee every morning. If the people you see weekly have no idea you work in mortgages, you're quietly leaving money on the table.
Other Professionals
While most LOs fight over the same handful of agents, the sharper ones diversify. Partnering with CPAs and financial advisors can produce some of your cleanest files. A client referred by a financial advisor typically shows up with organized finances, solid credit, and documented assets already in order — a world away from the messier leads you'll pull off the internet.
Don't overlook divorce attorneys either. It's an uncomfortable topic, but divorce frequently triggers a refinance to buy out a spouse or a fresh home purchase altogether. Being the calm, competent expert during that stressful moment builds real loyalty. Local home builders are worth cultivating too — they need a preferred lender who understands new construction timelines, and locking in that relationship can mean an entire subdivision's worth of loans.
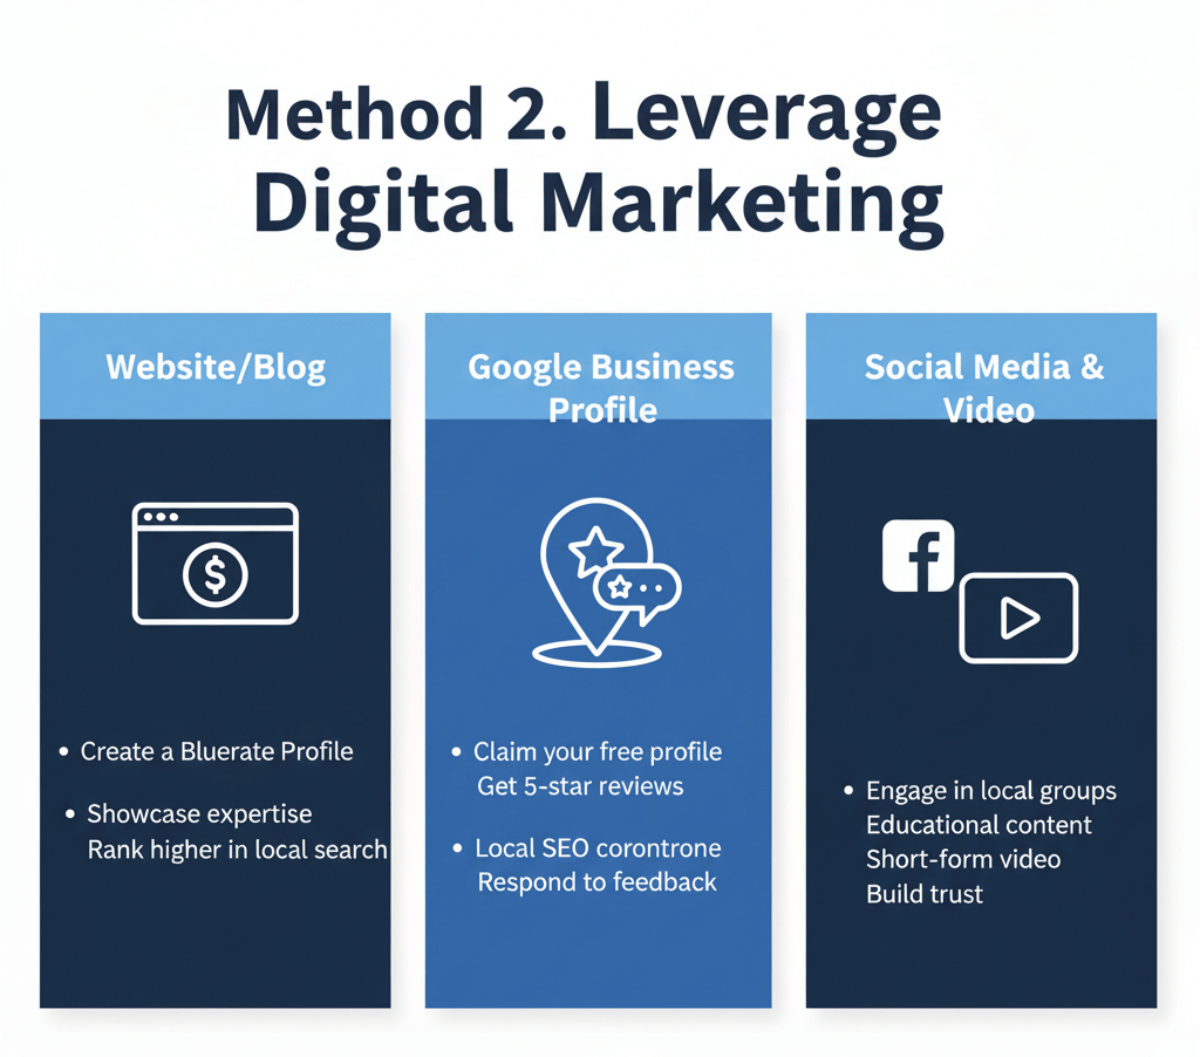
Method 2. Leverage Digital Marketing
By 2026, being invisible online is basically being invisible, period. Referrals are wonderful, but they don't scale on their own. To reach the roughly nine out of ten homebuyers who start their search on a screen, you need a real digital presence.
Website/Blog
A personal brand starts with a website, but let's be honest — building one from scratch is expensive and painfully hard to rank on Google. You could sink thousands into a custom site that nobody ever finds. This is exactly why I point new LOs toward Bluerate.
Bluerate is a marketplace built specifically to connect borrowers with loan officers. Rather than fighting an uphill SEO battle alone, you can set up a free profile page that functions as a real microsite — your photo, your bio, your expertise, no coding required. Because Bluerate invests heavily in its own SEO, your profile often ranks for local searches like "loan officer in [your city]" faster than a standalone site ever would. It also brings borrowers to you who are already searching for rates and guidance and can start a digital 1003 application right from your page, so your energy goes toward closing rather than website maintenance.
Google Business Profile
If someone hears your name, Googling you is their next move. An empty profile, or one with zero reviews, kills trust before you've said a word. Claiming your Google Business Profile costs nothing and remains one of the highest-leverage moves in local SEO.
Fill in every field — address, hours, phone number, and real photos of you, not stock images of houses. Reviews are the real currency here. Fifteen genuine five-star reviews will outperform thirty years of experience with zero digital footprint. Make requesting a review part of your closing routine, and respond to every review you get, good or bad, so it's obvious you're paying attention.
Social Media
You don't need influencer-level followers, just a consistent presence. LinkedIn works well for professional networking — connecting with agents, CPAs, and recruiters, and sharing rate updates or industry commentary.
For reaching actual borrowers, Facebook and Instagram do the heavier lifting. Join local groups — "Moms of Chicago," "First-Time Buyers of Florida," whatever fits your market — and resist the urge to post "Call me for low rates!" Instead, watch for someone asking, "Does anyone know a good lender?" and reply with something genuinely useful before sliding into their DMs. Share content that teaches rather than sells: three mistakes first-time buyers make, or how to buy with student loan debt still on the books. Be the helpful neighbor, not the pushy salesperson.
Video Marketing
Video closes the trust gap faster than almost anything else. When someone sees your face and hears your voice, they feel like they already know you — no professional studio required, just your phone.
Stick to short-form content for TikTok and Reels, and answer the questions borrowers ask you every single day: rent versus buy, what DTI actually means, how credit scores get calculated. Simplify without dumbing down. If you're camera-shy, record your screen instead and narrate over a rate sheet or a chart. The goal is teaching, not performing — people buy from whoever taught them something first.
Email Marketing
Most leads you generate aren't ready to buy today. They might be six to twelve months out. If you go quiet, they'll forget you exist and call whoever happens to be in front of them when they're finally ready. That's what email is for.
Skip the generic newsletter that just recaps interest rates. Send home maintenance tips, neighborhood trends, or local market news instead — content tied to their actual life stage. Segment your list, since renters need different messages than past clients who might be candidates for a refinance. Staying consistently useful is what keeps you top of mind until the trigger moment arrives.
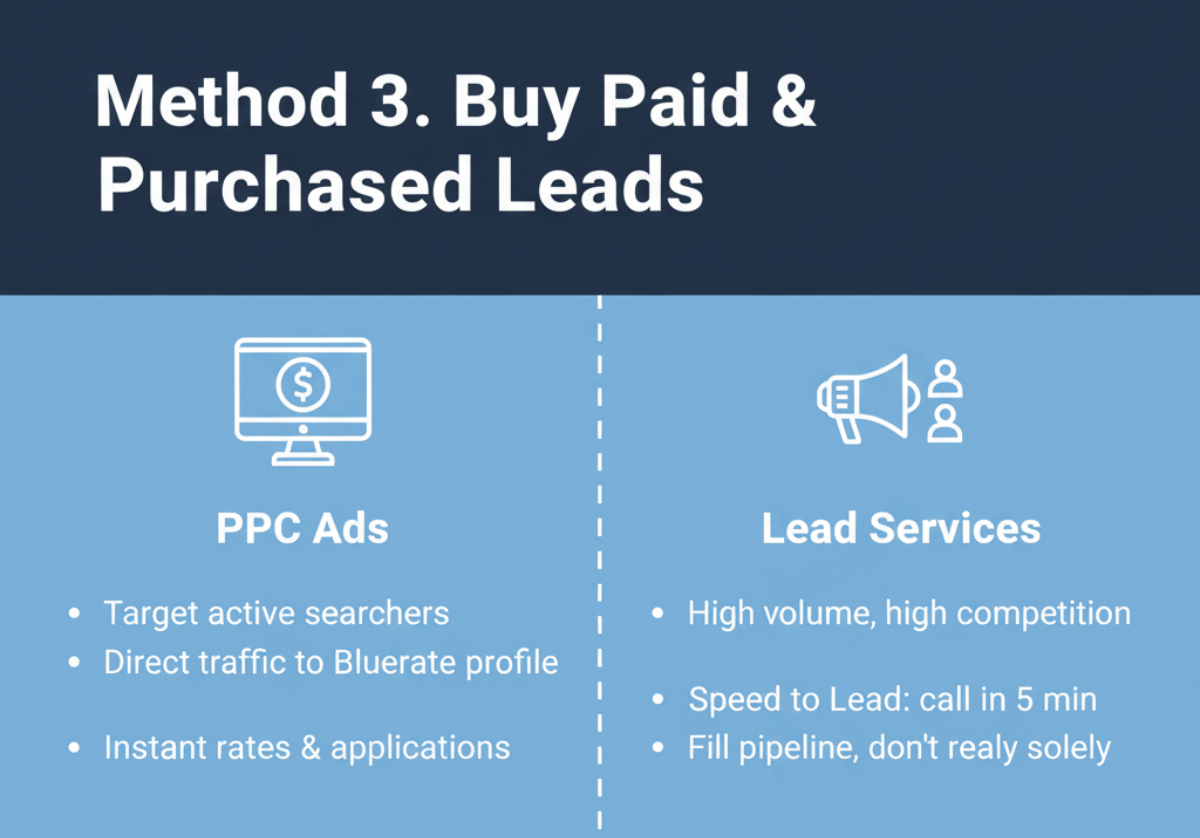
Method 3. Buy Paid & Purchased Leads
Paid leads are often called the fast lane, and they can be — but the lane has potholes. With the right follow-up system, paid strategies bring immediate volume. Without one, they bring immediate regret.
PPC Ads
Pay-per-click ads let you target people actively searching for a mortgage right now, but sending that traffic to a generic homepage wastes the click. Borrowers want answers immediately, not a contact form.
This is another spot where a Bluerate profile earns its keep. Point your Facebook or Google ad traffic there instead of a static landing page, and visitors can use built-in tools like personalized rate quotes or a digital 1003 application on the spot. Letting someone see real numbers or start an application the moment they click converts far better than a form that just says "someone will call you soon."
Lead Services
Services like Zillow or LendingTree can hand you volume fast, but volume isn't the same as quality — these leads are frequently sold to several lenders at once, so you're racing the clock from the moment they land.
Speed genuinely decides the outcome here. Research out of MIT's Sloan School found that leads contacted within five minutes are 21 times more likely to turn into a qualified opportunity than leads contacted after thirty minutes, and yet a separate audit of more than two thousand firms by Harvard Business Review found the average company still takes 42 hours to make that first call. Every minute you wait is a minute your competitor might not. Expect thick skin to be part of the job too — internet leads run colder and more price-sensitive, so calling a hundred of them to land two or three closings isn't unusual. Treat this channel as a way to fill gaps in your pipeline, not your only source of business, or you'll spend your career racing rivals to the bottom on rate.
One more thing worth knowing before you buy: not every purchased lead comes with proper consent to be called. Under the Telephone Consumer Protection Act, a lead needs documented, specific consent before you can legally contact them, especially if you're using any kind of automated dialer. A generic checkbox buried in a form's fine print usually doesn't cut it. Before you buy from any vendor, ask for their consent documentation, and keep records of it yourself — a CRM that logs every interaction and stores that paperwork will save you a serious headache if a lead ever disputes being contacted. This isn't legal advice, so when in doubt, loop in your compliance team, but it's worth knowing the risk exists before you dial the first number.
It's also worth tailoring your approach by loan type. A DSCR or non-QM lead usually needs a loan officer who can speak fluently about alternative qualification paths, not just standard conventional guidelines, while an FHA lead often has more questions about down payment assistance and mortgage insurance. Knowing the guideline nuances of the product you're selling, not just generic sales scripts, is often what separates a converted lead from a wasted phone call.
How to Score and Qualify a Mortgage Lead?
Not every lead deserves the same amount of your time, and figuring that out early saves hours you'd otherwise waste. A few quick signals tell you a lot: has the person already talked to a real estate agent, or are they just browsing? Do they have a rough sense of their credit score and how much they've saved for a down payment? Are they hoping to buy in the next few months, or just testing the waters a year out?
I usually ask two or three quick questions on the first call — timeline, credit range, and whether they're pre-approved anywhere else — before deciding how much energy to invest. A lead with a clear timeline and reasonable credit deserves a same-day follow-up plan. Someone who says "just looking, maybe next year" still deserves a polite response, but they belong in your email nurture sequence rather than your daily call list. Sorting leads this way early keeps your best opportunities from getting buried under leads that were never going to close this quarter.
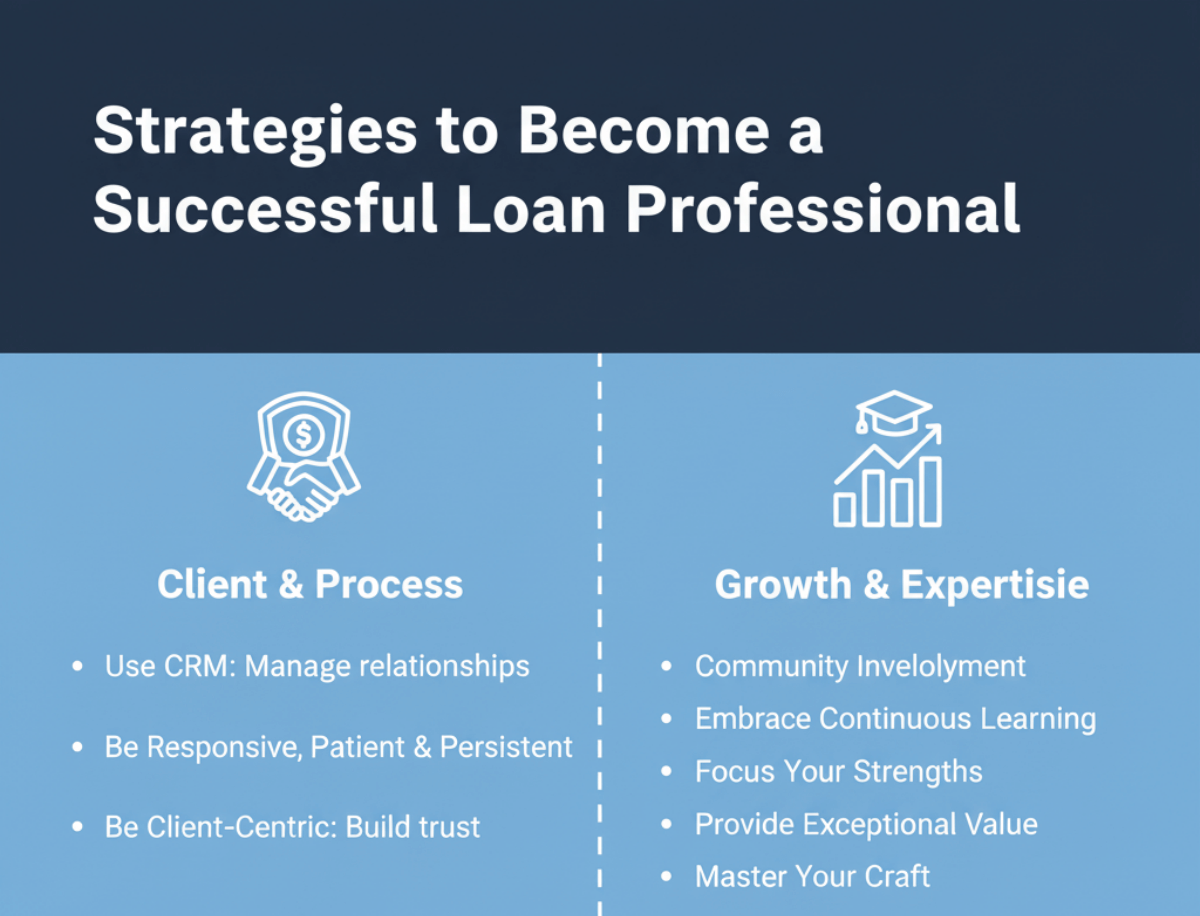
Strategies to Become a Successful Loan Professional
Getting the lead is only step one. Converting it into a closed loan, efficiently and without burning yourself out, is where the real money is made. Here's how to master the craft.
Use CRM
You can't run a pipeline off sticky notes or a spreadsheet — leads slip through, follow-ups get forgotten, and paperwork piles up fast. A dedicated mortgage CRM solves this, and I'd point you toward Zeitro specifically. Unlike a generic CRM built for any industry, Zeitro is built around how mortgage files actually move — document collection, organization, and communication, all in one place. When a borrower dumps fifty disorganized PDFs into your inbox, Zeitro's AI document review tools can sort and verify them automatically, so you spend your time selling instead of playing file clerk.
Community Involvement
Building real authority in your market means showing up in person. Host a first-time homebuyer seminar at the local library. Sponsor a Little League team. Show up at a food bank drive. People trust someone they've seen give back, not just someone running ads. Once you're a familiar face, you stop being "the mortgage guy" and start being a neighbor who happens to do mortgages for a living.
Be Responsive, Patient, and Persistent
Buying a home is stressful, and your responsiveness becomes the borrower's emotional anchor. Answer texts quickly, even if it's just "in a meeting, calling you within the hour." Be patient with questions you've answered a hundred times before — this is likely their first time navigating any of it. And stay persistent, because a "no" today is often a "yes" in six months. Most loan officers give up after one call, but the real money tends to show up on the fifth, sixth, or seventh follow-up.
Be Client-Centric
Put the borrower's financial wellbeing ahead of your commission, every time. If a refinance doesn't make sense because the break-even point is ten years out, say so. If stretching their budget for a bigger house is risky, tell them that too. You might lose a deal today, but the honesty builds a reputation nothing can touch. Clients can sense when someone's chasing a commission, and they gravitate toward the ones who clearly aren't.
Embrace Continuous Learning
Guidelines, rates, and regulations shift constantly in this business, so staying a student of the craft isn't optional. Join a professional group like the Association of Independent Mortgage Experts, or your local broker association. Find a mentor who's weathered a market downturn or two. Attend webinars on new loan products whenever you can. The more scenarios you understand, the more deals you'll close without hesitation.
Focus on Your Strengths
You don't need to excel at everything. If video terrifies you but you're a natural at coffee meetings with agents, lean into that. If you're introverted but good with data, put your energy into SEO and paid ads instead. Look back at where your last six months of closings actually came from, and pour more effort into that specific channel rather than copying someone else's playbook that doesn't fit your personality.
Provide Exceptional Value
Education sells better than persuasion ever will. A confused borrower doesn't sign anything. Take the time to explain the real difference between FHA and conventional financing, or why paying points might actually make sense for their situation. Offer a total cost comparison instead of just quoting a rate. When you hand someone real clarity instead of a sales pitch, a 0.125% rate difference elsewhere stops mattering as much — they'll stay with you because you made the process make sense.
Master Your Craft
Here's the biggest obstacle for anyone new to this business: confidence. A complicated scenario shows up — say, a self-employed borrower with a 650 credit score — and you freeze, telling them you'll check and get back to them. That hesitation is exactly where deals go to die.
This is where Zeitro Strata AI changes the equation. It's an AI guideline assistant trained on guidelines from dozens of lenders across conventional, FHA, VA, and non-QM programs, and every answer comes with a citation you can actually check, so you're never guessing. Instead of digging through PDF handbooks or waiting on an account executive to call back, you can ask something specific — "Can I use twelve months of bank statements for a borrower with a 650 score?" — and get a sourced answer in seconds instead of the thirty minutes manual guideline lookups used to take. That kind of speed lets you answer with real authority on the spot, which is often the difference between keeping a nervous borrower engaged and watching them go find another loan officer who sounded more confident.
Frequently Asked Questions
How do loan officers get their first clients?
Most new loan officers start with their existing network — friends, family, past coworkers — before layering in real estate agent partnerships and a basic online presence. It rarely happens through one channel alone; it's usually a slow combination of relationships and visibility.
What's the fastest way to get mortgage leads without spending money?
Referrals cost nothing but time. Asking every satisfied client for an introduction, showing up in local Facebook groups, and claiming a free Google Business Profile are the three highest-leverage moves that don't require a marketing budget.
Is buying mortgage leads worth it?
It can be, but only with a fast, disciplined follow-up system and a clear understanding of TCPA consent requirements. Purchased leads convert at a lower rate than referrals, so budget for volume and treat it as one channel among several rather than your entire strategy.
How much do mortgage leads typically cost?
Costs vary widely by lead type, loan product, and exclusivity. Shared leads sold to multiple lenders cost less per lead but convert at a lower rate, while exclusive or live-transfer leads cost more upfront but usually convert better.
What should I say when I call a new mortgage lead?
Keep it short, confirm they actually filled out the form (some leads are accidental clicks), ask about their timeline, and offer one clear next step, like a quick pre-qualification call, rather than launching into a rate pitch.
Conclusion
Success in this business isn't a sprint, and there's no single trick that fills your pipeline overnight. It takes a hybrid approach — the human side, built on genuine relationships with partners and past clients, combined with the digital side, built on visibility and the right technology. A strong personal brand on Bluerate brings organic traffic your way, while tools like Zeitro and Zeitro Strata AI handle the guideline research and file management that used to eat your entire day. That combination frees you up to focus on what actually matters: the people in front of you. Stop chasing low-quality leads, and start building something that lasts.